
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Novavax (NVAX) Stock Looks Fully Priced On Its Current Sales Base
Novavax has seen sharp swings in investor sentiment over the past few years, yet the latest share price level raises a straightforward question. Given where the stock trades today, are the company’s current and potential sales enough to back up that valuation?
- Over the past 5 years, Novavax shareholders have seen the stock fall 92.4%, which puts the spotlight firmly on whether the revenue base can now support the current market value.
- The business remains heavily tied to turning its product pipeline into recurring commercial revenue. This can shape how much investors are really paying for each dollar of sales and how that may evolve over time.
- The analysts covering Novavax have run their own numbers. See what analysts think Novavax's shares could be worth.
For investors, the debate is whether Novavax’s current share price is properly aligned with the scale and quality of the sales the company is generating and can reasonably grow into.
If you want to stress test whether Novavax’s US$12.56 share price and sales profile feel reasonable, compare it with 27 high quality undervalued stocks as a broader reference point.
Has Novavax Run Too Far on Sales?
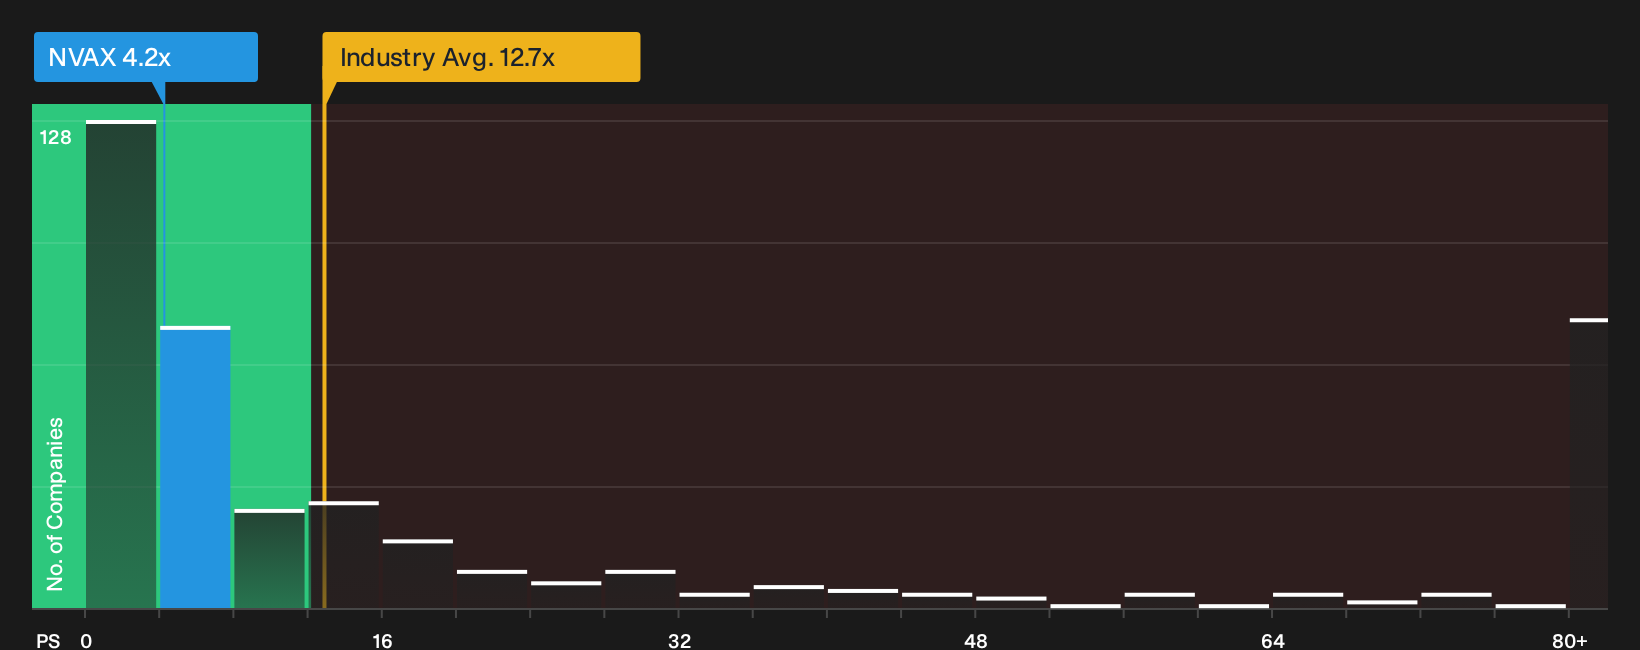
P/S is a useful lens for Novavax because earnings and free cash flow are still volatile, while revenue gives a clearer anchor for what investors are paying for the product portfolio today. On this measure, the stock trades on a P/S of 5.0x, compared with an average of 12.7x for the broader biotechs sector and 28.0x across its peer group.
The tailored fair multiple implied by the model sits below those broad benchmarks, and the current 5.0x level is above that reference point. On this framework Novavax screens as overvalued on its sales base. For anyone weighing an entry or adding to an existing position, the key question is whether the quality, durability and risk profile of those revenues justify paying more than the model suggests is appropriate. Explore the numbers behind Novavax's P/S valuation.
The Novavax Narrative: What Would Justify Today's Price?
Novavax’s valuation puzzle sets up the role of Simply Wall St Narratives. These short scenarios spell out what kind of growth, margins and earnings path would need to play out for the stock to be worth materially more or less than today’s price. Each one lays out the assumptions sitting behind its fair value view so you can track those against actual results over time on Simply Wall St’s Community page.
The Novavax community is split between those who see a licensing led, higher margin future and those who focus on concentration risk and execution questions.
Bull case: 9% undervalued
"Partnership with Sanofi has de-risked commercial execution for Nuvaxovid and opened doors for future milestone and royalty streams..."
Discover why this Narrative puts Novavax at 9% undervalued.
Bear case: 79% overvalued
"Heavy historical dependence on a narrow product portfolio, primarily COVID-19 and flu vaccines, magnifies Novavax's vulnerability to rapid market saturation..."
Explore why this Narrative puts Novavax at 79% overvalued.
Novavax’s price is only one piece of the decision
Valuation frames what you are paying today, but analyst projections for where Novavax could be a few years from now offer a separate reference point that can challenge or reinforce your view. Explore where analysts expect Novavax to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com