
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bandwidth (BAND) Holders Are Up 278% And The Market Still Has Not Settled It
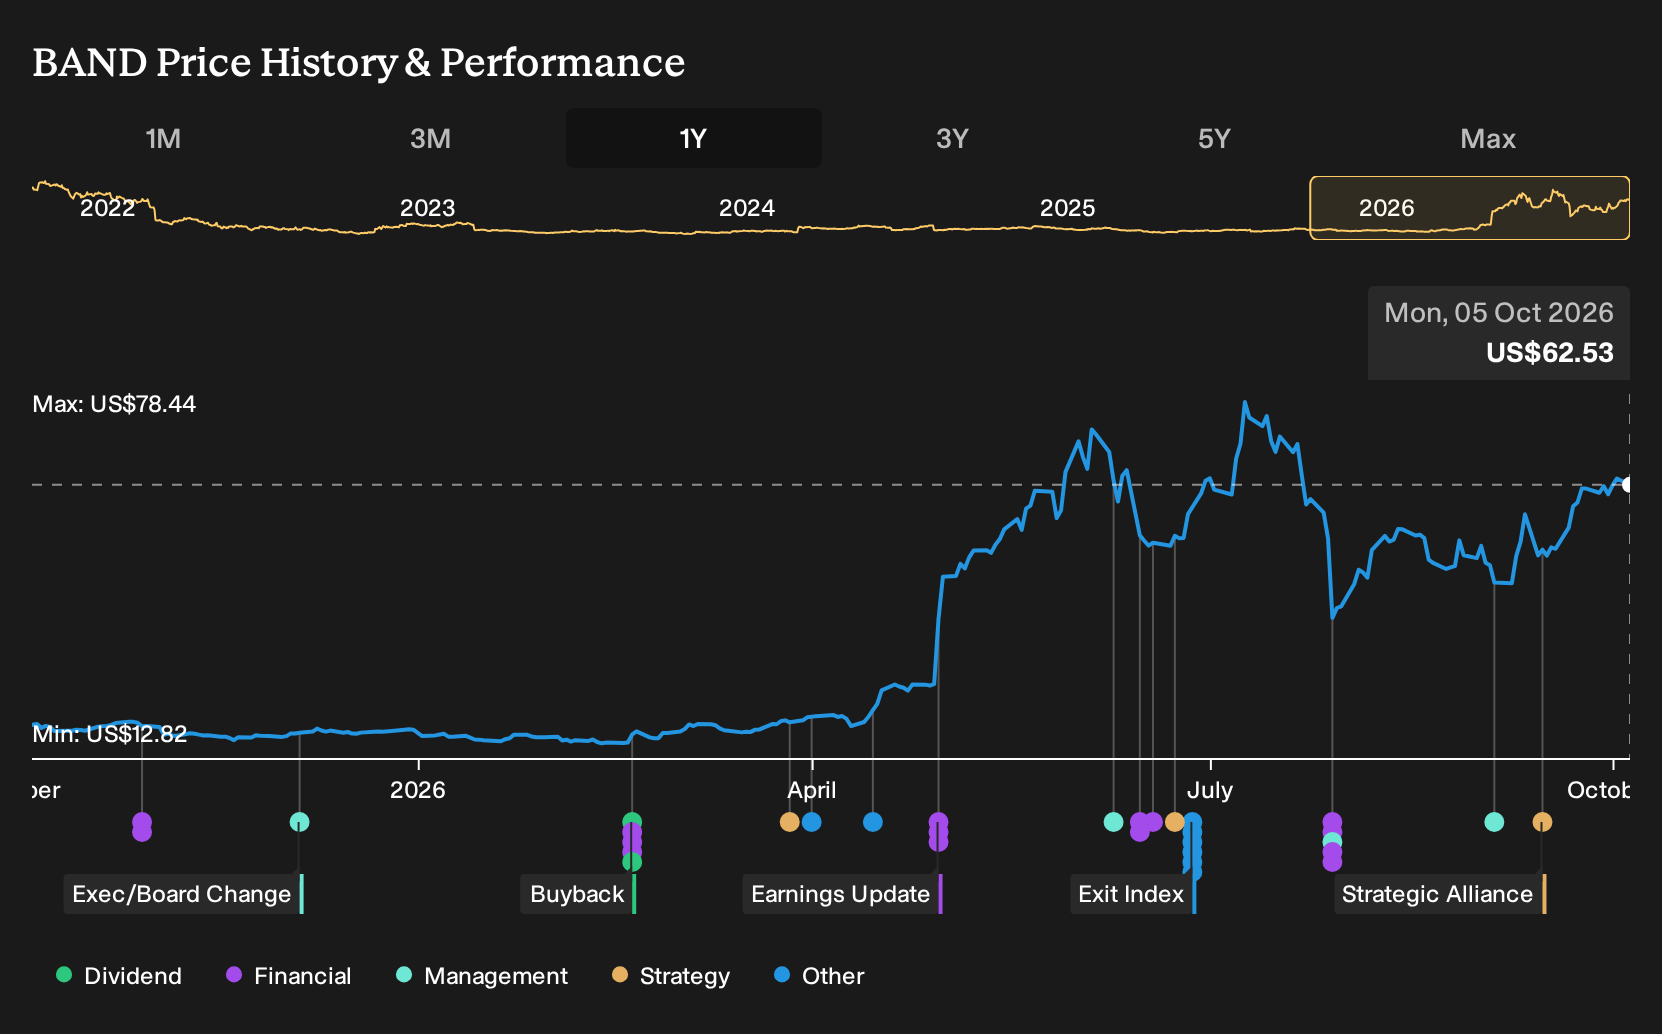
If you had picked Bandwidth on 5 October 2025 and simply held on, the outcome would have been hard to ignore. Holding Bandwidth over the past year would have returned 278.1%, including dividends. That result throws you back to the starting line. If you were making that choice then, what would you have focused on more: the bullish AI voice migration story, or the bear case around privacy rules, customer concentration, and legacy messaging drag?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Bandwidth has already moved. Pinpoint other ways to investigate the theme among 91 AI infrastructure stocks.
The Argument You Would Have Been Weighing Up On Bandwidth
The shares cost US$16.09 at the start of the period, and Bandwidth sat between two very different but credible stories about its future.
On the bullish side, the Fair Value was US$21.5, based on annual revenue growth of 9.2% and a shift to a 1.8% profit margin, with AI voice and enterprise cloud migration doing the heavy lifting.
The more cautious narrative pointed to a Fair Value of US$15, based on 7.8% revenue growth, a 1.5% margin, and pressure from legacy messaging, strict privacy rules, and customer concentration.
What The Evidence Did To The Bandwidth Argument
Bandwidth reported Q2 2026 revenue of US$219.9m and a net margin of 1.1%, up from a loss and a margin of 2.7% in Q2 2025. This supported the bullish focus on AI voice and higher profitability. A US$275m convertible note issue and relatively low gross margins around 38% kept pressure on the cautious case. Overall, the evidence cut both ways.
The hinge assumption here was that AI voice would translate into healthier earnings, not just headlines. For any other stock with an AI story, it may be useful to track whether net margin and absolute profit move in the same direction as the narrative about new products or contracts.
What Bandwidth's Price Now Asks You To Believe
Today Bandwidth trades at US$62.53, and the selected Narrative’s Fair Value sits below that market level. The Narrative frames this gap around pressure on legacy communication APIs, rising compliance burden, and the weight of customer concentration.
A buyer at today’s price is effectively assuming AI voice, Maestro and global expansion turn into durable, high quality earnings. The key question is how the risk of shrinking core usage revenue and heavier regulation shapes that bet.
"Proliferation of over-the-top messaging services and alternative communication platforms like Teams and WhatsApp continues to erode the relevance and demand for traditional telephony APIs and SMS/MMS, placing downward pressure on Bandwidth's core usage-based revenue and undermining long-term top-line growth. Increased regulatory scrutiny and the tightening of global privacy laws such as GDPR and CCPA will drive sustained increases in compliance costs and restrict Bandwidth's ability to innovate around customer data, shrinking operating leverage and ultimately compressing net margins."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 24% below our estimate - targets data centre demand for GPU racks with a controlled software ecosystem.
- Company 2 - 42% below our estimate - rides a backlog of large digital display projects amid uneven earnings and expenses.
- Company 3 - 27% below our estimate - expands high horsepower capacity for data centre power projects while containing tech losses.
Those are three of them. See all 27 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com