
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
SLB (SLB) Wins Fresh Energy Contracts, Is It Still 19% Below Fair Value?
SLB (SLB) is back in focus after its OneSubsea joint venture won a subsea systems award for ExxonMobil’s Rovuma LNG project in Mozambique, along with fresh multi year work in Saudi Arabia and Oman.
These contract wins arrive after a choppy few weeks for SLB. The 30 day share price return is down 12.57%, while the 90 day move is up 8.32% and the year to date gain is 25.07%.
Scan beyond SLB and review a curated set of energy and infrastructure players through the 39 power grid technology and infrastructure stocks that could also be moving on large project pipelines and capacity build outs.
SLB is winning sizeable contracts while the share price has pulled back over the past month. Is the recent slide pointing to softer conviction in the business, or has sentiment simply run ahead of a valuation reset?
Most Popular Narrative: 19% Undervalued
SLB last closed at $50.28, while the most followed narrative assigns a fair value of $62.41 based on a 7.63% discount rate. That gap rests on the idea that higher margin digital, production focused and data center work will reshape the earnings mix.
Rapid scaling of SLB’s Data Center Solutions business, backed by a backlog that underpins an annualized revenue run rate exceeding US$2 billion by the end of 2027 and medium term targets of US$4.5 billion to US$5.0 billion of data center revenue and US$700 million to US$800 million of adjusted EBITDA in 2028 after the Kelvion acquisition, introduces a large, capital light revenue stream that can add meaningfully to consolidated revenue, EBITDA and cash generation.
See why 160 investors see SLB as 19% undervalued.
Result: Fair Value of $62.41 (UNDERVALUED)
Still, the SLB narrative can be knocked off course if Middle East activity remains constrained or if the planned data center build out delivers weaker economics than expected.
Find out about the key risks to this SLB narrative.
Another View On SLB’s Valuation
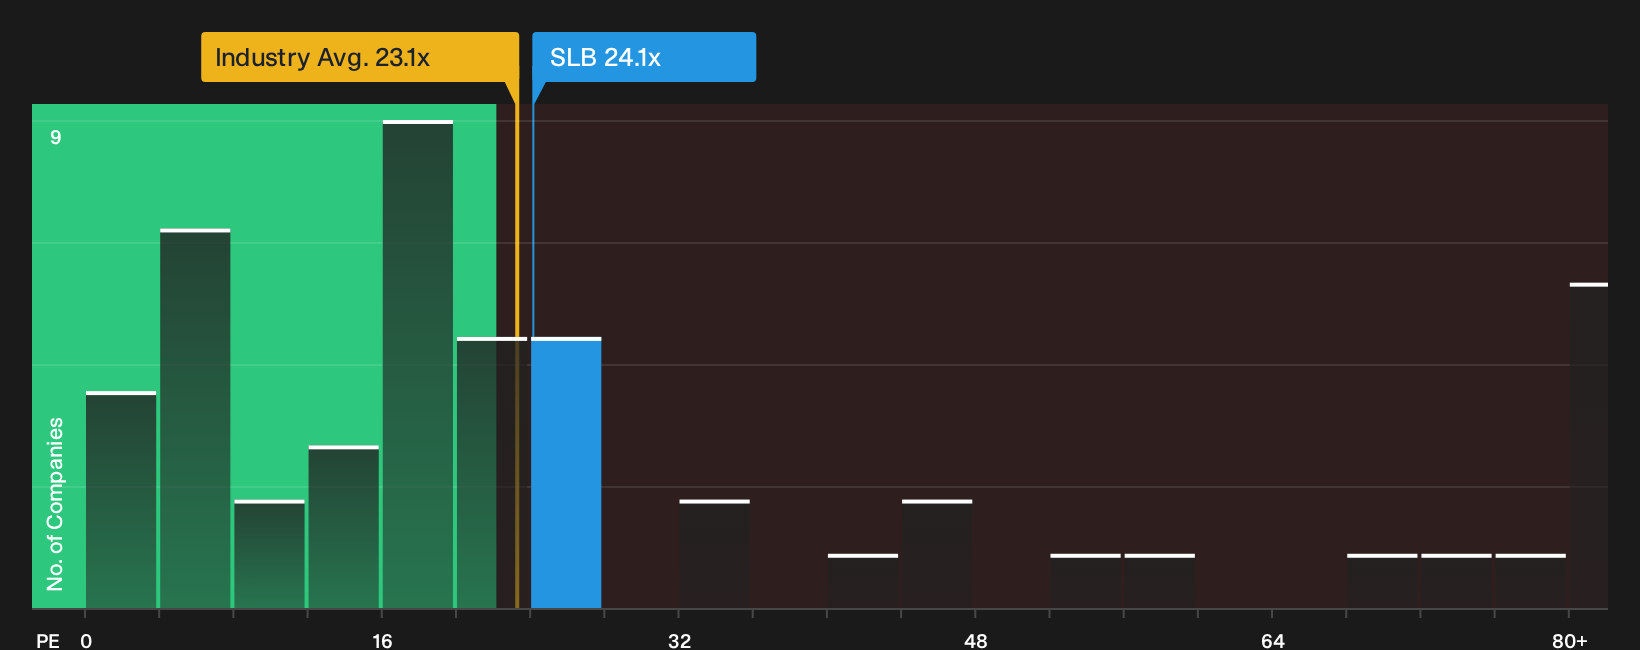
The story looks different when shifting from the cash flow driven fair value to a simple P/E check. SLB trades on 24.1x earnings, which is above both its 22.6x fair ratio and the US Energy Services sector at 23.1x. That richer multiple can limit upside if expectations cool.
For investors who lean on earnings based yardsticks rather than long term cash flows, the gap between the current 24.1x P/E and the 22.6x fair ratio can indicate less of a safety buffer if sentiment weakens, particularly when peers are at 23.1x. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on SLB so far and the story is still forming. Move quickly, review the numbers yourself, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond SLB?
If SLB has your attention, do not stop there. Broader opportunities often emerge when you compare a few different angles at once.
- Target quality at a discount by scanning companies that screen as 27 high quality undervalued stocks before the crowd fully focuses on them.
- Strengthen your income stream by reviewing a curated set of 7 dividend fortresses that aim to combine yield with resilience.
- Protect your downside by concentrating on 31 resilient stocks with low risk scores that may support steadier returns when conditions turn choppy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com