
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Brady (BRC) A Bargain After An 82% Five Year Return?
Brady has delivered a strong stretch of returns, and the share price moves now raise a straightforward question for you as an investor. Is the current US$85.41 price tag adequately backed by the earnings power of the business?
- Brady has returned 82.0% over the past 5 years. This puts real pressure on the question of whether its current earnings profile can carry that kind of share price progress.
- The company relies heavily on converting its identification and workplace safety products into steady profit. The durability of those earnings and cash flows may support or limit how much investors are prepared to pay for each dollar of income.
- There is a second opinion on Brady worth weighing. See what analysts think Brady's shares could be worth.
The issue now is whether Brady's current earnings justify today's valuation or leave the stock pricing in more than the business is delivering.
If you are questioning whether Brady's recent 82.0% five year return is fully earned by its profits, you might also want a wider watchlist built from 27 high quality undervalued stocks.
Is Brady a Bargain on Earnings?
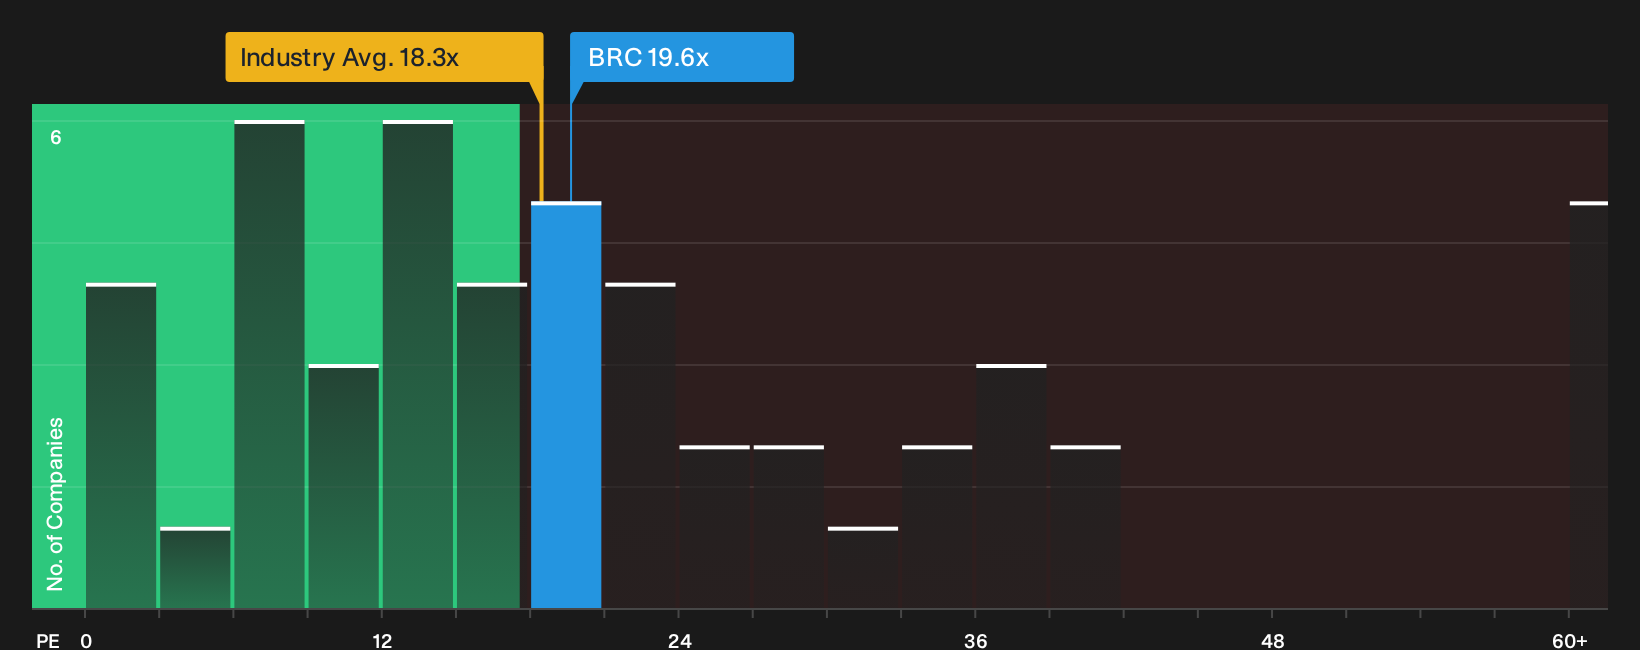
The P/E ratio is a decent starting lens for Brady because earnings are a key anchor for how investors value its steady label and safety products business. Right now the stock trades on a P/E of 19.6x, compared with an industry average of 18.3x for Commercial Services. That points to investors paying a bit more for each dollar of Brady earnings than for the sector overall.
Against closer peers, where the typical P/E is 15.0x, the stock carries a clearer premium. The modelled fair P/E multiple suggests Brady trades below the level that would usually match its mix of profitability, size and risk, so the current valuation still screens as undervalued on this framework even with that premium to the sector and peer group. Explore the numbers behind Brady's P/E valuation.
The Brady Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Brady. They spell out which paths for revenue, margins and earnings would need to play out for the current share price to look either conservative or stretched, and each one is framed as a clear, testable view on Brady's business that you can watch over time, rather than a single frozen fair value snapshot on Simply Wall St's Community page.
A clear, written Narrative on Brady right now gives you a concrete, number driven view of where its growth, margins and execution need to go to support the current P/E premium. It sets out the assumptions behind that profile in advance so you can track, over time, whether Brady's actual results keep backing the price you are being asked to pay.
Share your own Narrative for Brady and set out the assumptions behind your valuation.
One more Brady factor that could matter just as much as the P/E
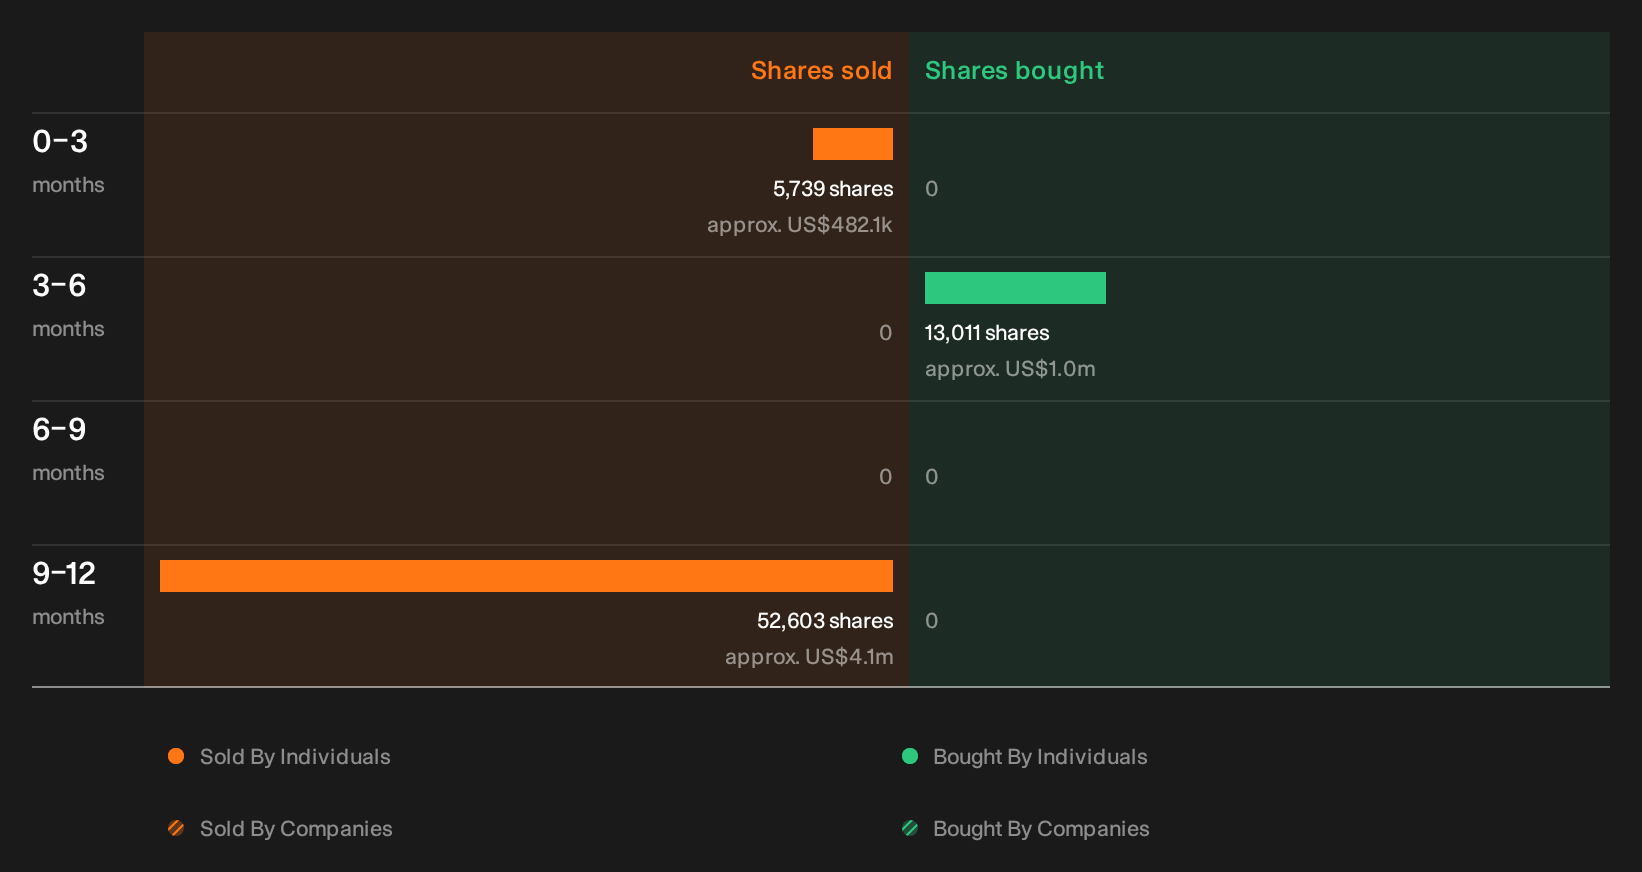
Before closing the book on Brady, it is worth knowing that recent trading by directors and senior executives has been flagged by our checks, with the individuals involved, the size of those trades and what they might signal still left for you to review. See the recent insider selling flagged for Brady.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com