
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is On Holding (ONON) Undervalued Following Reaffirmed 2026 Guidance And Q3 Sales Targets?
On Holding (NYSE:ONON) is back in focus after management reiterated earnings guidance for fiscal 2026 and outlined constant currency net sales growth targets for the third quarter, while also elevating Laura Miele to Lead Independent Director.
Recent trading has started to tilt more positive for On Holding, with a 3.34% 1 day share price return and a 13.90% 30 day share price return, even though the share price is still down 32.10% year to date and the 1 year total shareholder return is down 25.11%. The 3 year total shareholder return is up 26.51%, suggesting short term momentum is rebuilding after a weaker stretch.
Scan for other consumer brands that combine strong revenue growth with recent share price pressure by starting with our hand picked 19 high quality undiscovered gems aligned with On Holding's profile.
On Holding now sits in an awkward middle ground, where double digit revenue and earnings guidance meets a share price still working off earlier losses. Is the latest rebound a verdict on the business, or on changing sentiment around the stock as valuation comes into focus next?
Most Popular Narrative: 27% Undervalued
On Holding's most followed narrative pegs fair value at $43.44 against a last close of $31.88, highlighting a clear gap between market price and that framework for the brand's long term plan.
The acceleration in DTC (Direct-to-Consumer) and e-commerce channels, with DTC reaching new highs (41.1% of sales in Q2 and up 54% YoY), gives On more control over brand, pricing, and customer data while increasing gross and EBITDA margins. This is seen as an operational catalyst likely to further expand profitability as DTC continues its mix shift.
See why 119 investors see On Holding as 27% undervalued.
Result: Fair Value of $43.44 (UNDERVALUED)
Still, the bullish script for On Holding can unravel quickly if premium pricing begins to face real resistance or if U.S. wholesale softness lingers longer than expected.
Find out about the key risks to this On Holding narrative.
Another View: On Holding Through The P/E Lens
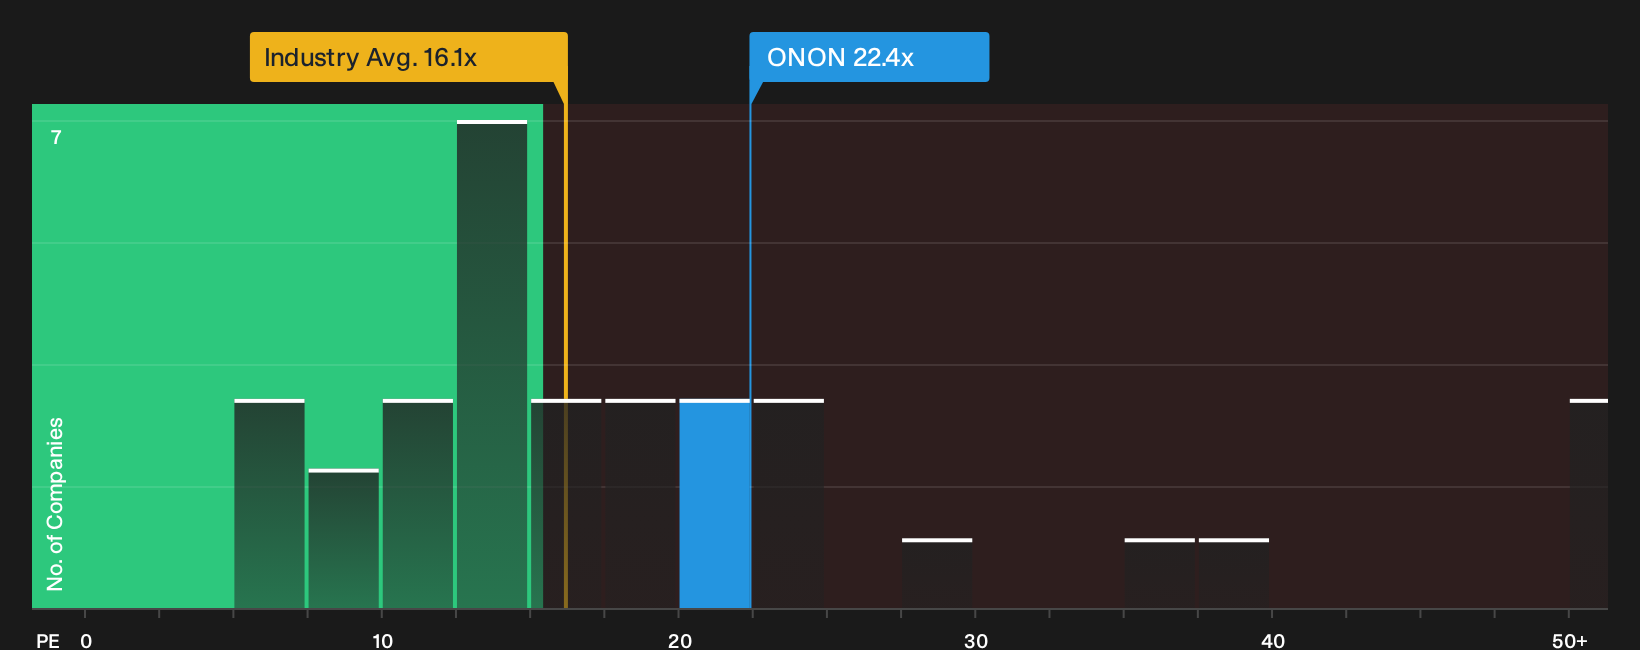
There is a catch. On Holding trades on a P/E of 22.3x, which is higher than the US Luxury group at 16.1x, its peer average at 14.9x, and even above a fair ratio of 22.1x. That points to less margin for error if the story stumbles.
For a closer look at how this pricing gap compares with industry peers and the fair ratio the market could move toward, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
That mix of cautious optimism and valuation questions will only get you so far, so move fast and test the assumptions against your own research. For a quick way to see what the current optimism is based on, start with the 3 key rewards.
Hunting For More On Holding Style Ideas?
If On Holding's setup has your attention, do not stop here. Use the same curiosity to scan fresh ideas that might fit your next move.
- Target resilient performers by zeroing in on companies in our 31 resilient stocks with low risk scores that score well on stability and downside protection.
- Spot potential mispricings early and pressure test your watchlist against the 27 high quality undervalued stocks before prices move away from you.
- Go beyond the obvious and surface potential future leaders by working through the 19 high quality undiscovered gems while they are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com