
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Turkish Bank Stocks Retail Investors Are Watching As Inflation Cools
Turkish inflation finally slipping back below 30% has shifted the conversation from sheer survival to selective opportunity, and that matters for anyone watching local banks and financial stocks. Changing price pressures and interest-rate expectations can quickly reshape which businesses look resilient and which look fragile. This article walks through three Turkish financial stocks exposed to this macro reset, explaining how the same inflation story could help or hurt each one.
The banks covered below are only a small sample, and the broader screen surfaced 21 more Turkish domestic financial companies with equally compelling stories that are not unpacked in this article. To see the full picture, head straight into the Turkish domestic banks and financials screener to identify, filter, and analyze the highest conviction ideas across this universe.
Albaraka Türk Katilim Bankasi (IBSE:ALBRK)
Overview: Albaraka Türk Katilim Bankasi is a Turkish participation bank offering Sharia-compliant financing, deposits, payments, insurance, and digital banking services closely tied to the domestic economy.
Operations: Albaraka Türk Katilim Bankasi generates TRY 43b from Commercial and Corporate, TRY 31b unallocated, TRY 27b from Treasury, and TRY 10b from Retail segments.
Market Cap: TRY 22.1b
Albaraka Türk Katilim Bankasi gives direct exposure to Türkiye’s domestic credit cycle through participation banking, with activities funded and lent in local currency. The stock trades on a P/E of 2.4x against a Turkish market average of 14.3x, while maintaining a reported ROE of 28.93%, so investor attention naturally turns to what happens when one unseen pressure on that profitability shifts.
When a 2.4x P/E and 28.93% ROE start to look out of sync, the DCF valuation analysis for Albaraka Türk Katilim Bankasi can show whether Albaraka Türk Katilim Bankasi’s earnings power is being mispriced.
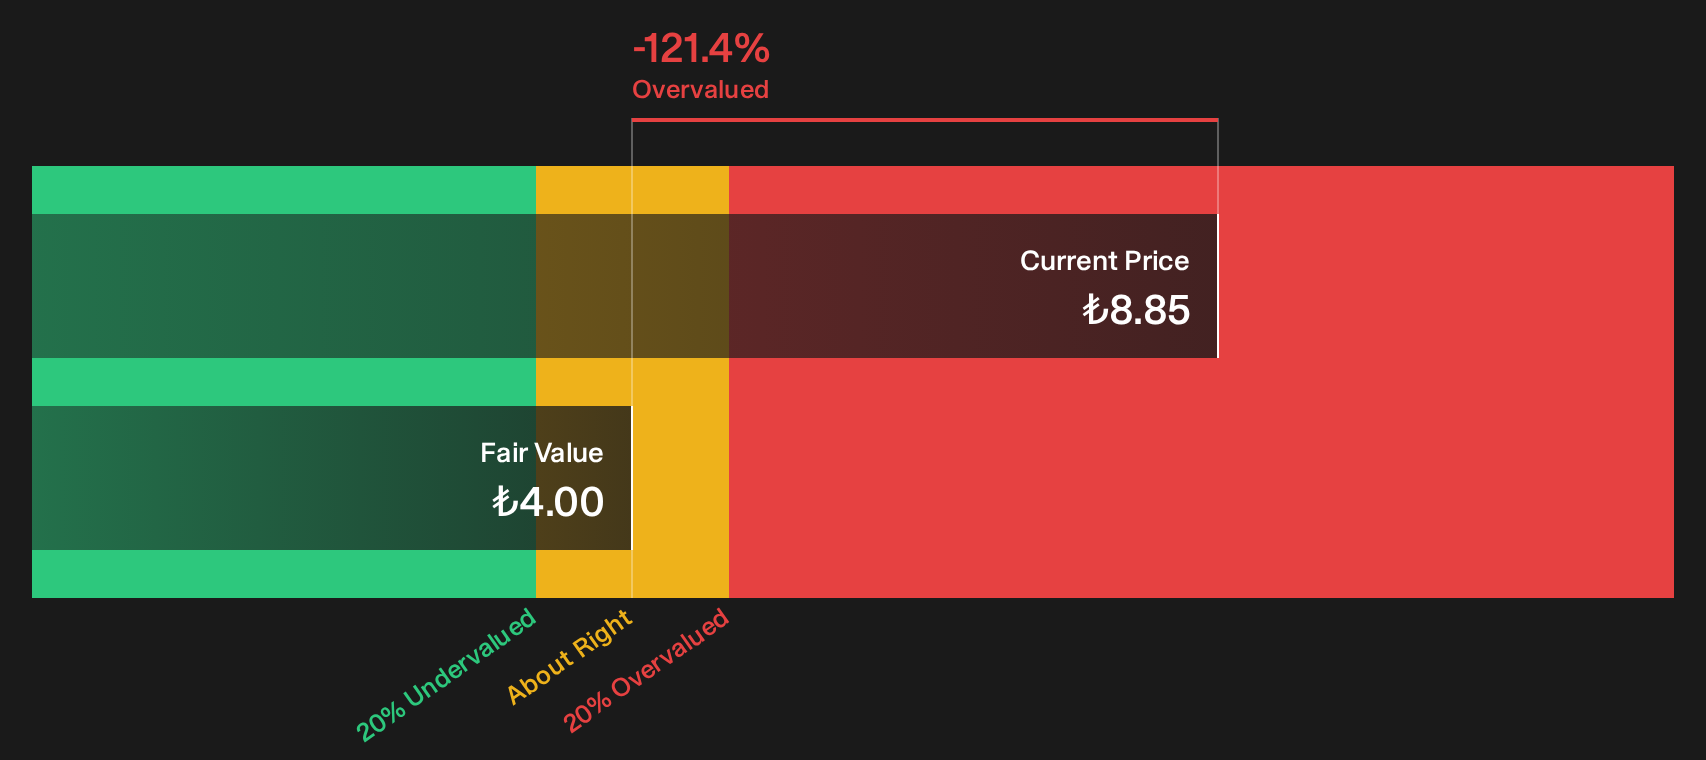
Türkiye Halk Bankasi (IBSE:HALKB)
Overview: Türkiye Halk Bankasi is a large state-owned Turkish bank providing deposits, lending, payments, investment products, and digital services across the domestic economy.
Operations: Türkiye Halk Bankasi generates TRY 255.4b from Treasury and Investment activities, TRY 70.3b from Integrated banking, and TRY 6.9b from Other operations.
Market Cap: TRY 321.7b
For a screener built around Turkish domestic banks and financials, Türkiye Halk Bankasi matters because its balance sheet and earnings are tightly linked to how Türkiye’s interest-rate cycle and inflation story filter through the real economy.
"The heavy tilt toward securities, which account for almost 28% of total assets with a growing share of fair value through P&L instruments, leaves earnings more exposed to changes in interest rates and valuation methods. This can introduce higher volatility in revenue and net income."
What happens to Türkiye Halk Bankasi’s margins if one key macro assumption about that interest-rate path quietly shifts direction?
If that shift is what worries you, read the full narrative for Türkiye Halk Bankasi to see how Türkiye Halk Bankasi’s earnings profile could be masking both risk and upside.

Türkiye Sinai Kalkinma Bankasi (IBSE:TSKB)
Overview: Türkiye Sinai Kalkinma Bankasi is a Turkish development and investment bank financing long term domestic projects, tightly linked to local macro conditions.
Operations: Türkiye Sinai Kalkinma Bankasi generates TRY 11.6b from Investment Banking, TRY 6.7b from Corporate Banking, and TRY 6.2b from other activities.
Market Cap: TRY 28.1b
For a screener built around Turkish domestic banks and financials, Türkiye Sinai Kalkinma Bankasi matters because it channels wholesale funding directly into Turkey focused lending, just as inflation and rate expectations start to reset.
"Expanding climate, green recovery and earthquake related funding lines from DFIs, much of it Treasury guaranteed and still undisbursed, should translate into higher FX loan volumes and fee generating mandates, supporting revenue growth and earnings visibility."
What really moves margins for Türkiye Sinai Kalkinma Bankasi now is how one unseen pressure on its funding costs and project pipeline evolves.
That quiet funding pressure is exactly why reading the full narrative for Türkiye Sinai Kalkinma Bankasi can show where Türkiye Sinai Kalkinma Bankasi might be accelerating or quietly stalling next.

Seeking Alternatives Beyond Turkish Banks?
Fresh ideas move first. By the time the crowd wakes up, the early entry points are already dropping away. Scan these curated lists while it matters and act now.
- Spot cash generative operators before momentum really builds by running through the list of solid balance sheet and fundamentals (207 results) curated from businesses with clean finances and room to move.
- Consider structural demand for critical materials by checking the 33 best rare earth metal stocks packed with producers positioned around key supply bottlenecks while they are still under the radar for now.
- Explore the next power build out by using the 39 power grid technology and infrastructure stocks focused on companies exposed to grid upgrades, electrification, and steady infrastructure rollouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com