
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hemlo Mining (TSX:HMMC) Is Back In Focus, What Is The Market Weighing?
Event driven look at Hemlo Mining shares
Hemlo Mining (TSX:HMMC) has put a refined regional exploration plan at the center of its story after recent work reclassified the Hemlo deposit as an Archean porphyry epithermal gold molybdenum system.
On the market, Hemlo Mining’s share price has pulled back sharply in the short term, with a 7 day share price return of 14.63% down and a 30 day share price return of 29.82% down, even though the year to date share price return is 12% up and the 3 year total shareholder return is very large. However, the 5 year total shareholder return is 50.22% down, which points to long term investors sitting on mixed outcomes as sentiment cools following earlier gains.
Compare Hemlo Mining's event driven setup with a curated group of producers and developers by scanning our 36 elite gold producer stocks for potential next ideas in the gold space.
Hemlo Mining has shifted its geological story while the share price has already cooled sharply. Is most of the rerating already in the rear-view mirror, or does the current valuation still leave meaningful upside on the table?
Price-to-Earnings of 71.5x: Is it justified for Hemlo Mining?
Valuation has shifted faster than the story for Hemlo Mining, with the stock trading on a P/E of 71.5x against a CA$5.60 last close and sitting well above both its sector and peer benchmarks.
The P/E ratio compares what investors are paying for each dollar of net profit. For a gold producer like Hemlo Mining, a high multiple often signals that the market is giving a lot of credit to forecasts or one off events rather than current earnings power.
Forecasts in the data point to earnings growth expectations and a DCF output that suggests the current price sits well below an estimated future cash flow value of CA$40.39. That kind of gap can mean investors are pricing in the early stages of a profitability story and treating recent profitability and forecast growth as a justification for paying up today. Yet the same P/E of 71.5x is very strong compared to both the Canadian Metals and Mining industry average of 15.5x and the peer average of 23.2x, while also sitting far above an estimated fair P/E of 25.8x that the market could move towards as sentiment and forecasts adjust.
Explore the SWS fair ratio for Hemlo Mining.
Result: Price-to-Earnings of 71.5x (OVERVALUED)
To put that in context, the SWS DCF model currently estimates a future cash flow value of CA$40.39 per Hemlo Mining share, which is far above the CA$5.60 last close.
This approach projects future cash flows and discounts them back using a required rate of return, aiming to capture both forecast growth and the time value of money. For a miner that has only recently become profitable and carries large one off items, cash flow based work like this can help frame where the underlying asset might sit over a full cycle rather than only on the latest reported earnings.
Look into how the SWS DCF model arrives at its fair value.
Still, Hemlo Mining’s high P/E and reliance on a single flagship asset mean any disappointment in exploration outcomes or commodity prices could quickly challenge this valuation story.
Find out about the key risks to this Hemlo Mining narrative.
Another view on Hemlo Mining’s value
The P/E story paints Hemlo Mining as expensive, yet the SWS DCF model points the other way. At a CA$5.60 share price against an estimated future cash flow value of CA$40.39, that framework labels the stock as undervalued. Which lens should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
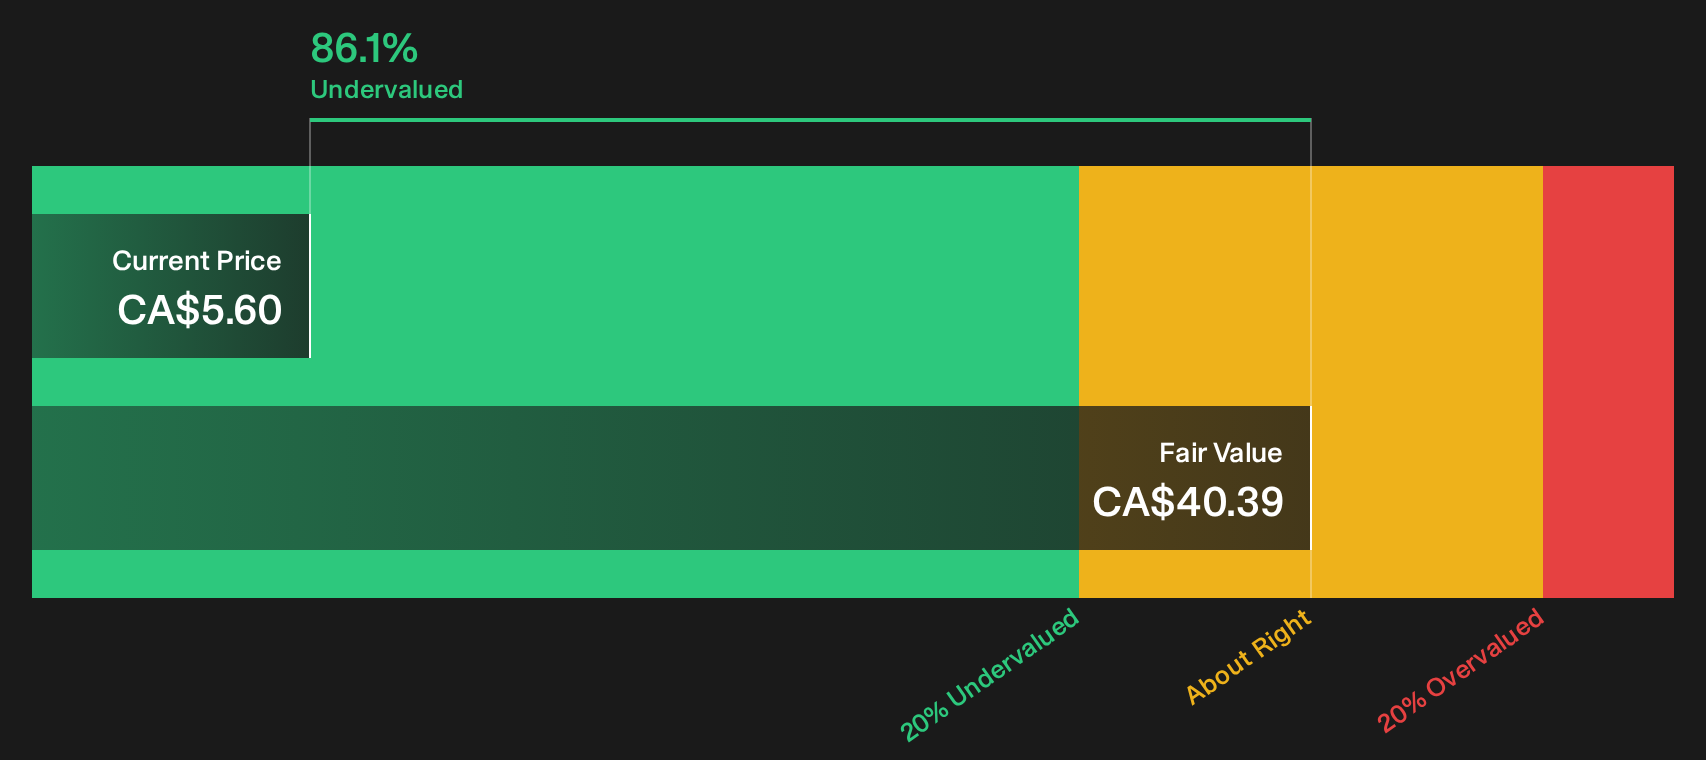
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hemlo Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by how mixed the setup for Hemlo Mining feels after all of this. Act quickly, stress test the numbers, and let the data shape your own conviction by weighing the 4 key rewards and 2 important warning signs.
Ready for more ideas beyond Hemlo Mining?
If Hemlo Mining feels hard to pin down, you may want to cast a wider net with ready made stock ideas that match different goals, risk levels, and income needs.
- Look for potential mispriced opportunities by reviewing a focused list of quality companies that still look cheap using the 7 high quality undervalued stocks.
- Strengthen the defensive side of your holdings by checking companies with healthier finances through the list of solid balance sheet and fundamentals (7 results).
- Build a cash flow oriented watchlist by scanning higher yielding opportunities across markets with the 1 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com