
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Two Stories Ran On Sarepta Therapeutics. Only One Held Up
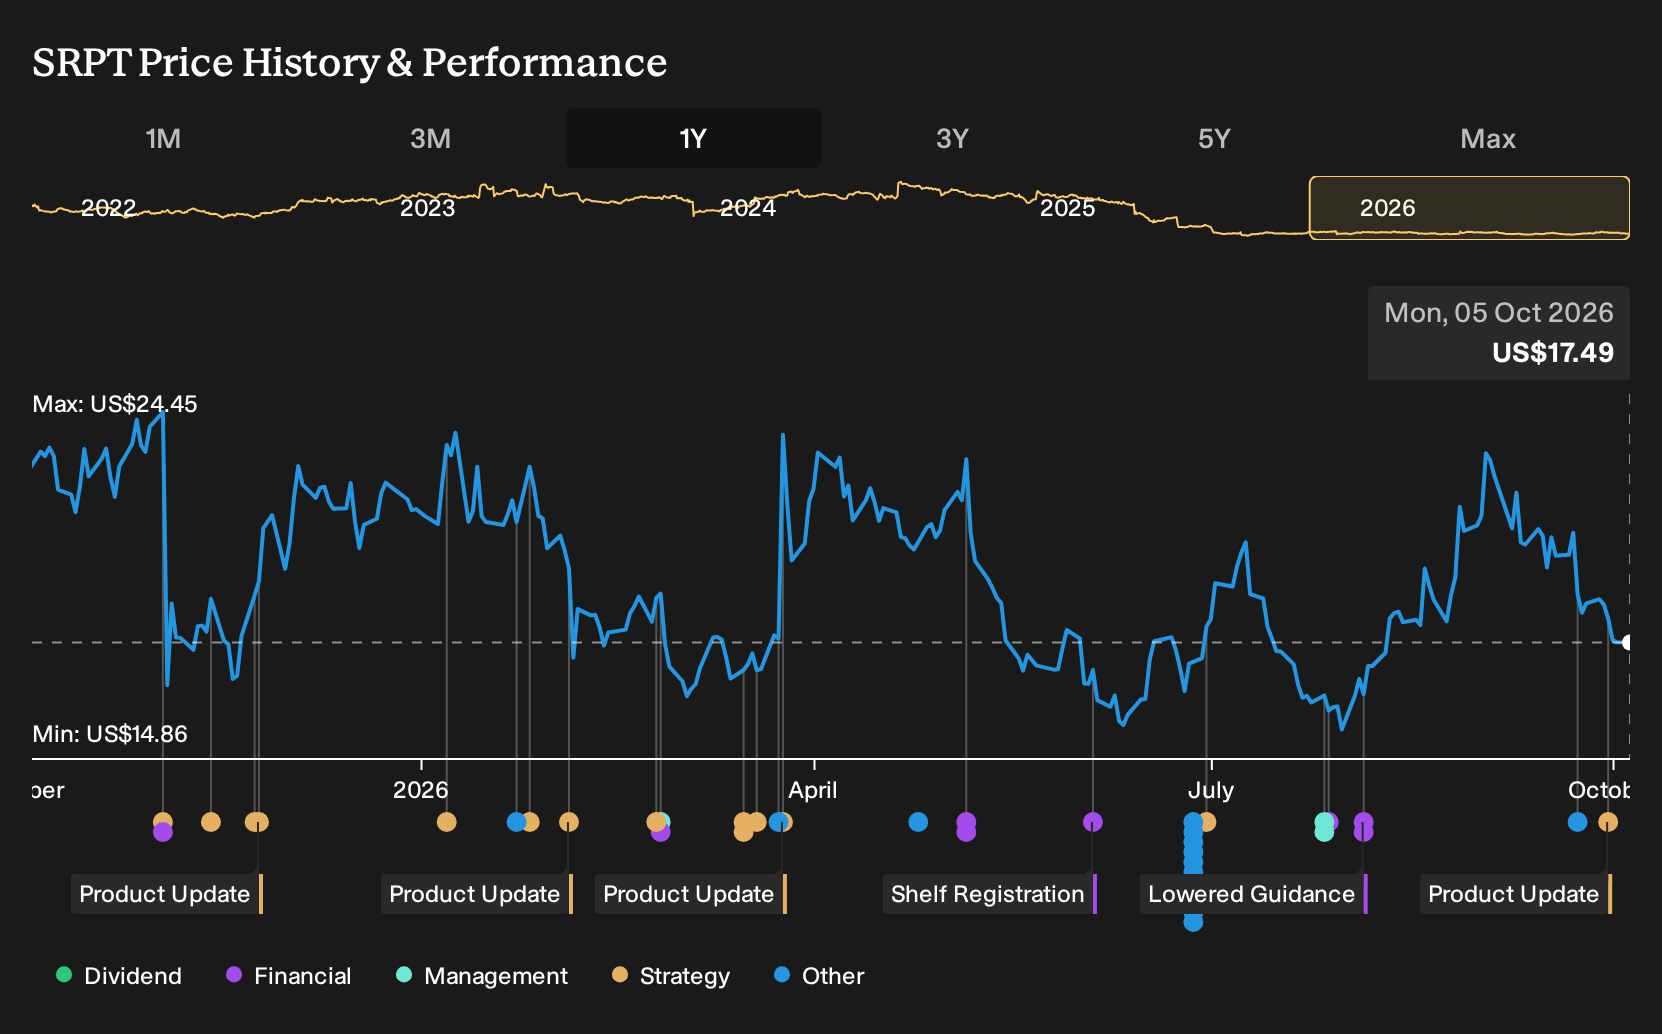
If you had looked at Sarepta Therapeutics on 5 October 2025 and decided against owning it after reading the competing bullish and bearish cases, the last twelve months played out in a way that might feel like risk you sidestepped. For Sarepta Therapeutics shareholders, the loss over the past year was 24.8%, including dividends. With that decline now on the scoreboard, which earlier warning sign or optimistic assumption would you go back and interrogate most closely?
The move put Sarepta Therapeutics in the middle of this trade. Scan 33 healthcare AI stocks for other companies exposed to it.
The Argument Sarepta Therapeutics Investors Were Really Weighing
The shares cost US$22.64 at the start of the period, and anyone looking at Sarepta Therapeutics then had to choose between two sharply different stories built on the same gene therapy platform.
The bullish side saw a Fair Value of US$55.9, a price level implied by its more optimistic assumptions, and leaned on expanding genetic testing, strong ELEVIDYS insurance coverage, and broader infusion networks to support revenue growth and margin improvement.
The bearish narrative pointed to a Fair Value of US$5, again just an implied price from its own model, and focused on safety concerns after an ELEVIDYS related patient death, as well as ongoing infusion delays and regulatory scrutiny as key risks.
What The Evidence Did To The Sarepta Therapeutics Debate
Sarepta Therapeutics delivered Q2 2026 revenue of US$401.3 million and a net loss of US$4.9 million, which challenged the bullish margin story. Net margin moved from 32.2% in Q2 2025 to a 1.2% loss, so profitability progress that optimistic investors expected did not show up in these figures. The evidence supported the cautious case.
The lesson is simple. When a thesis leans heavily on future margin expansion, keep checking net margin in each report against that promise rather than only watching top line or guidance.
What Sarepta Therapeutics Buyers Are Really Pricing In Now
Sarepta Therapeutics now trades at US$17.49, and the selected Narrative argues that its Fair Value sits above the current price. The focus is less on headline returns and more on whether a cash generative Duchenne portfolio can support an expanding pipeline.
The Narrative leans on cash flow, siRNA data and ELEVIDYS risk mitigation as the core pillars. For the recent fall to look like an opening rather than a warning, a buyer today would need to believe those programs progress well enough for that cash engine and pipeline to hold together.
"Sarepta Therapeutics is using a cash flow positive Duchenne muscular dystrophy portfolio, with Q2 2026 product gross margins of 75% and non GAAP operating income of US$86 million, to self fund pipeline work and potentially support future earnings and cash generation without relying on new equity."
One Narrative disagrees with today's price. → See where this Narrative says Sarepta Therapeutics should trade
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 22% below our estimate - positions critical chips and software for secure, scalable digital infrastructure performance.
- Company 2 - 45% below our estimate - wins satellite connectivity contracts supporting defense, public networks and digital inclusion.
- Company 3 - 41% below our estimate - grows a multi-service finance app where user engagement deepens payments and lending.
That is three of the list. See every one of the 27 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com