
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Leidos (LDOS) Stock May Be A Bargain Following Raised Guidance
Leidos Holdings has seen its share price under pressure over the past year, and the gap between that market slide and the company’s earnings now raises a simple question about what you are paying for at today’s level.
- The stock is down 39.0% over the past 12 months, which puts the focus squarely on whether that drop matches what the business is earning.
- Fresh contract wins in defense and new AI driven cyber tools may support expectations for future profit streams, which matter directly for how investors judge its current earnings multiple.
- Your read on Leidos Holdings is one view; the desks covering it have another. See what analysts think Leidos Holdings's shares could be worth.
The issue now is whether the current price of Leidos Holdings is adequately supported by the earnings the company is producing today.
If you want more context around Leidos Holdings and its recent share price decline, it can help to compare its earnings story with companies screened for 27 high quality undervalued stocks
Is Leidos Holdings a Bargain on Earnings?
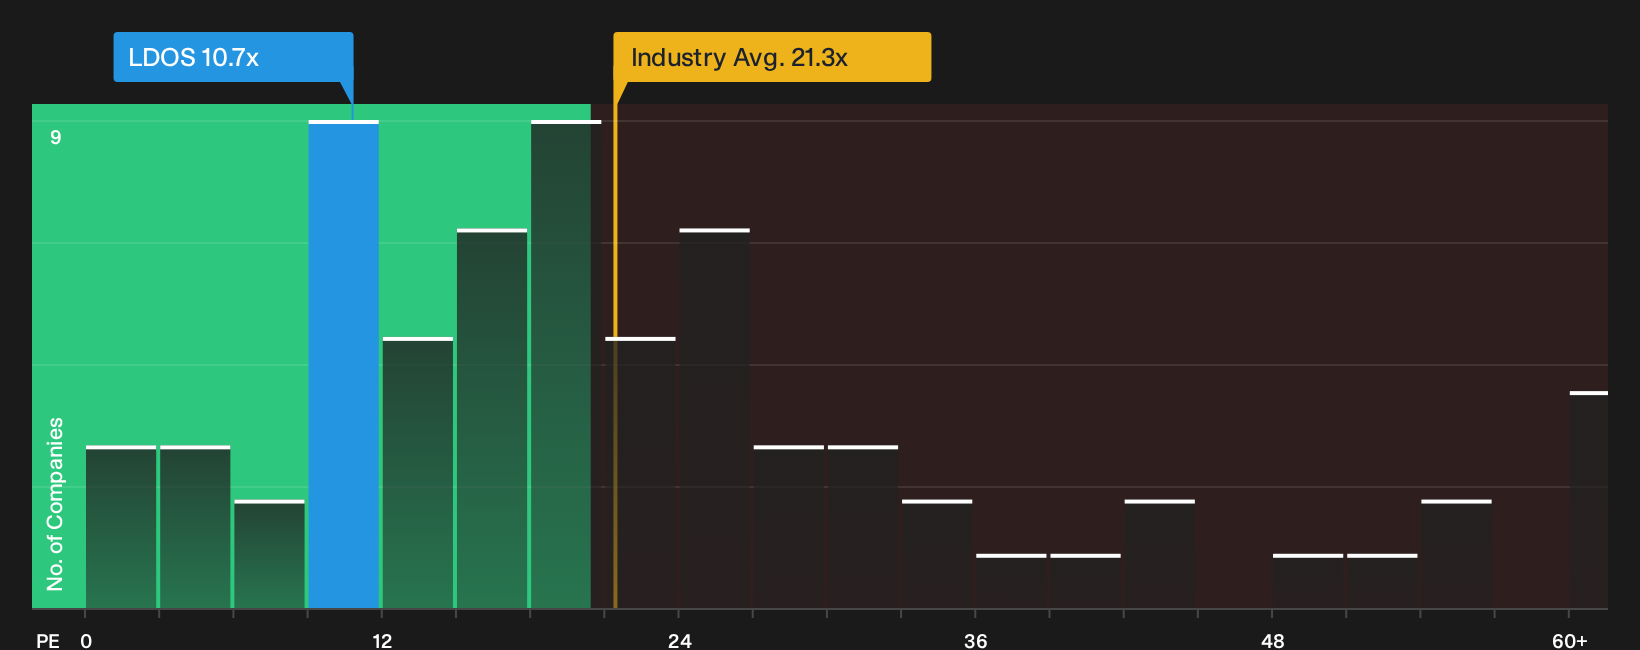
The P/E ratio fits Leidos Holdings because earnings are a key lens for a contract driven defense and technology group. On that yardstick, the stock trades on about 10.9x earnings, compared with an industry average of roughly 21.3x and a peer group sitting near 30.6x. A tailored fair P/E for Leidos that blends its margins, growth profile, size and risk comes out higher than where the shares trade today, so the current multiple sits on the discounted side of that range.
Because the Q2 2026 update flagged solid revenue growth and fresh defense contract wins, this lower P/E suggests the recent share price slide has pushed Leidos Holdings to a level where earnings are valued more cautiously than both sector norms and that model driven benchmark. For readers, the question is whether those contracts and new AI driven cyber tools can sustain the profit base that this multiple is putting a relatively modest tag on right now. Explore the numbers behind Leidos Holdings's P/E valuation.
The Leidos Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Leidos Holdings leaves off. They spell out which assumptions on future growth, profit margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Rather than a single P/E or model output, each narrative lays out its own set of expectations so you can compare those inputs with the actual results as they arrive.
One of the top community narratives on Leidos Holdings: 24% undervalued
"The current valuation implies the market is not fully crediting Leidos for its cash generation, low capital intensity, and large awarded pipelines…"
Discover why this Narrative puts Leidos Holdings at 24% undervalued.
Leidos Holdings investors still have one more big question to answer
Price and current earnings only tell part of the story for Leidos Holdings. Professional analysts have mapped out where they think this business could be several years from now, and that track is worth comparing with today’s market view. Explore where analysts expect Leidos Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com