
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Monadelphous Group Early Buyers Had To Back And It Was Not The Easy Case
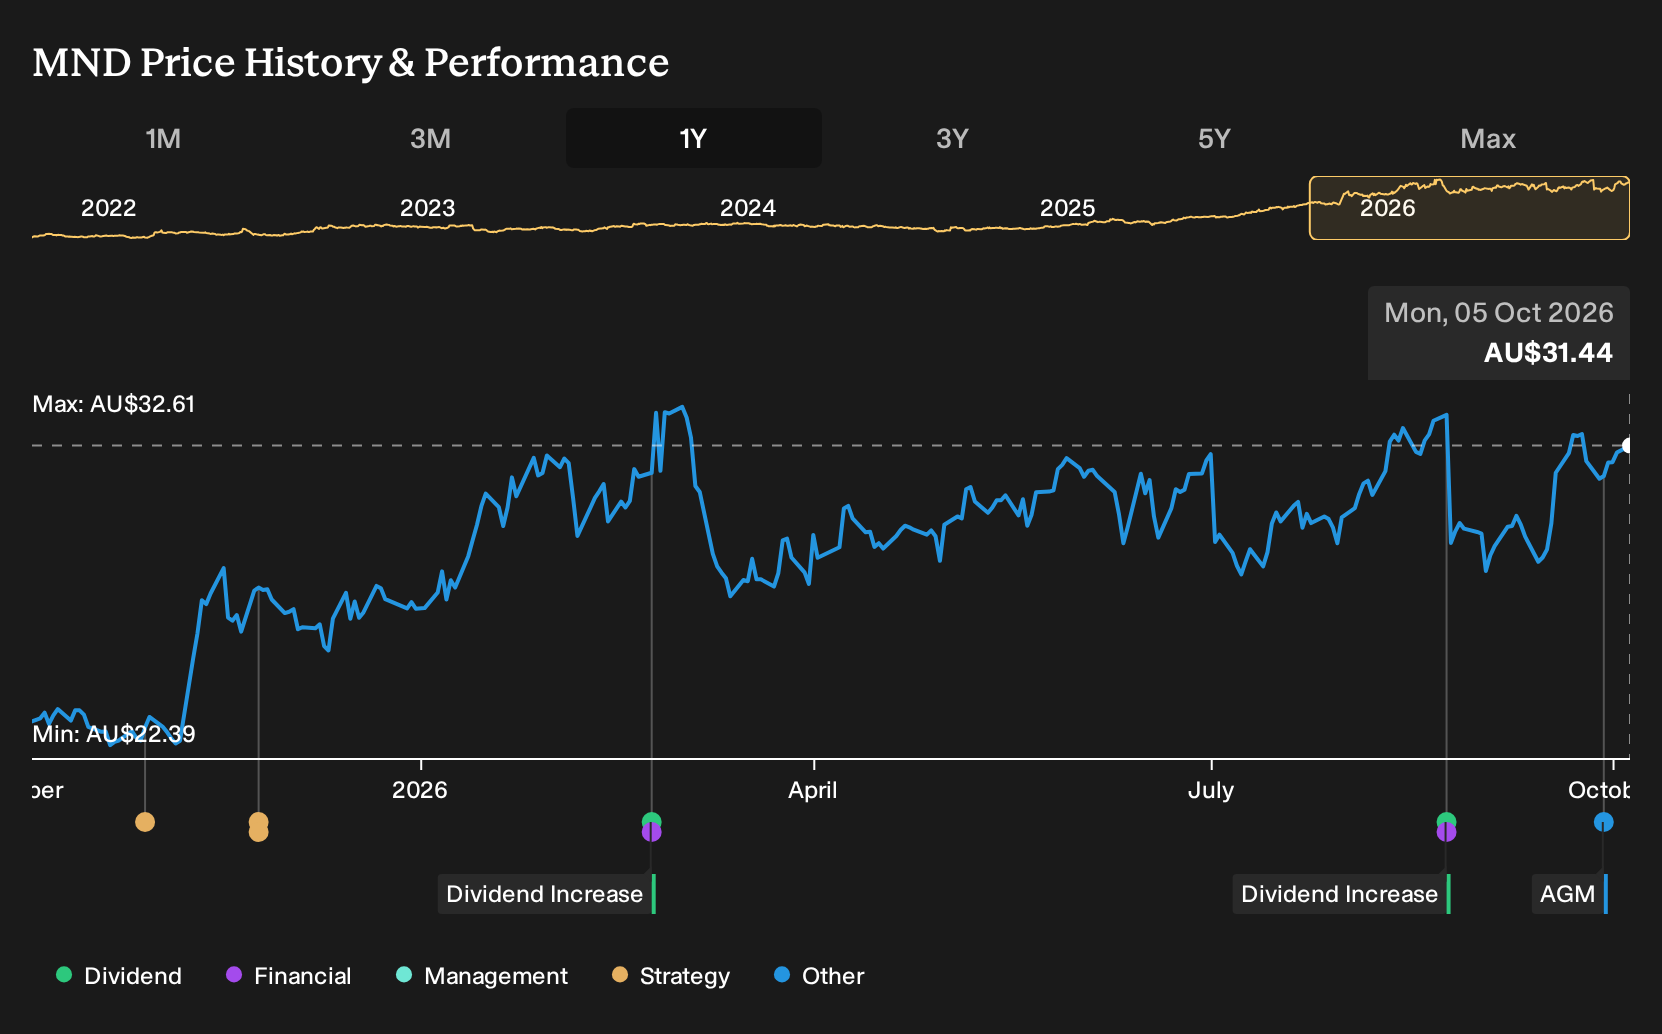
Investors who held Monadelphous Group over the past year are up 40.5%, including dividends. If you had been weighing a purchase on 5 October 2025, you were looking at analysts split between an upbeat A$24.4 view and a far more cautious A$15.95, both tied to very different revenue and margin assumptions. With that kind of gap on record, which early clues around decarbonisation work, contract density, and wage pressure would have mattered most to you?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Monadelphous Group is not the only name tied to this theme. Zero in on 40 power grid technology and infrastructure stocks and compare how each one is priced.
What Monadelphous Group Investors Were Really Arguing About
The shares cost A$23.05 at the start of the period, which put Monadelphous Group between two very different yet plausible stories about its future.
On the upbeat side, the bull narrative put Fair Value at A$24.4, leaning on an assumption that revenue could grow 10.5% a year with profit margins edging up to 4.0% as decarbonisation and minerals demand supported contract density.
The bear case argued for Fair Value of A$15.95. That view rested on slower 3.9% revenue growth and margins easing to 3.5% as wage pressure, thinner tenders, and client concentration weighed on earnings quality.
What The Results Changed For Monadelphous Group
The headline development was the A$380 million Brigalow peaking plant award, which backed the bull case that Monadelphous Group could deepen its role in energy transition projects and lift contract density. Reported figures pulled in the same direction. Revenue moved from A$1,138.7 million in H2 2025 to A$1,356.9 million in H2 2026, while net margin shifted from 3.6% to 4.6%, so the evidence supported the optimistic case.
The central assumption that needed testing was whether higher margin decarbonisation and infrastructure work would actually show up in reported profitability. For a different contractor, you would track the mix of new energy and resources awards by size and then compare net margin and absolute profit a year later to see if the promised uplift is visible in the numbers.
What Today's Monadelphous Group Price Already Assumes
At A$31.44, Monadelphous Group trades above this Narrative's Fair Value estimate. The Narrative treats this as a gap between firm business progress and richer market expectations.
A buyer today is effectively assuming current contract momentum and earnings quality can hold or improve. How do client concentration, labour costs, and tender scarcity affect that assumption?
"Shifting energy markets, labor shortages, and escalating compliance demands are compressing margins and shrinking core opportunities, threatening operational efficiency and profitability. Dependence on a small group of major clients and a limited pipeline of large projects heightens risk of revenue stagnation and vulnerability to investment cycles."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 24% below our estimate - tightens inventory controls and upgrades distribution networks to bolster cash generation.
- Company 2 - 48% below our estimate - expands specialist maintenance crews as aging and new heavy equipment increase servicing needs.
- Company 3 - 23% below our estimate - integrates a major acquisition while modernising mines and processing plants for efficiency.
That is three of the list. See every one of the 5 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com