
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Limited 14 Year Bourbon Release Just Shift Brown Forman's (BF.B) Investment Narrative?
- Brown-Forman released a 14-year-old, high-proof single barrel bourbon in 2026, drawn from 99 carefully selected barrels and bottled by hand with detailed barrel and warehouse information on each bottle.
- The tightly curated 99 barrel lot and handcrafted presentation underline Brown-Forman’s focus on higher value, premium whiskey offerings rather than simple volume expansion.
- We will now assess how Brown-Forman’s limited 14 year single barrel bourbon release could influence the broader investment narrative around premiumization.
Scan for other premium spirits companies emphasizing scarcity and craftsmanship by reviewing our curated 19 high quality undiscovered gems that echo Brown-Forman's high-end bourbon playbook.
Brown-Forman Investment Narrative Recap
To own Brown-Forman, you need to believe its focus on premium spirits, global reach and cash generation can offset softer demand in some mature markets and pressure in tequila. The 14 year single barrel fits that story, but on its own does not change near term expectations for flat organic net sales or the guided 3% to 5% decline in organic operating income for fiscal 2027.
The key short term swing factor still looks like execution in emerging markets and ready to drink offerings, which have been supporting diversification. The biggest risk remains prolonged weakness in developed international regions, combined with margin headwinds from higher cost whiskey inventory and the drag from the shrinking used barrel and bulk business.
The new 14 year single barrel aligns closely with Brown-Forman’s push toward super and ultra premium spirits. That push sits alongside ready to drink innovation and smaller pack formats that aim to keep brands like Jack Daniel’s accessible while protecting average selling prices and, over time, helping gross margins absorb category and mix pressure.
For catalysts, investors are still watching whether emerging markets growth and ready to drink volumes can balance soft full strength spirits trends, tequila trade downs and weaker used barrel revenue. The limited release reinforces Brown-Forman’s premium credentials, but the bigger operational test remains execution on volume, mix and cost control across the global portfolio.
Brown-Forman's current analyst script points to revenues of US$4.2b and earnings of US$816.5m by 2029, based on a 2.3% yearly increase in revenue and an earnings uplift of about US$95m from the current US$721.0m level.
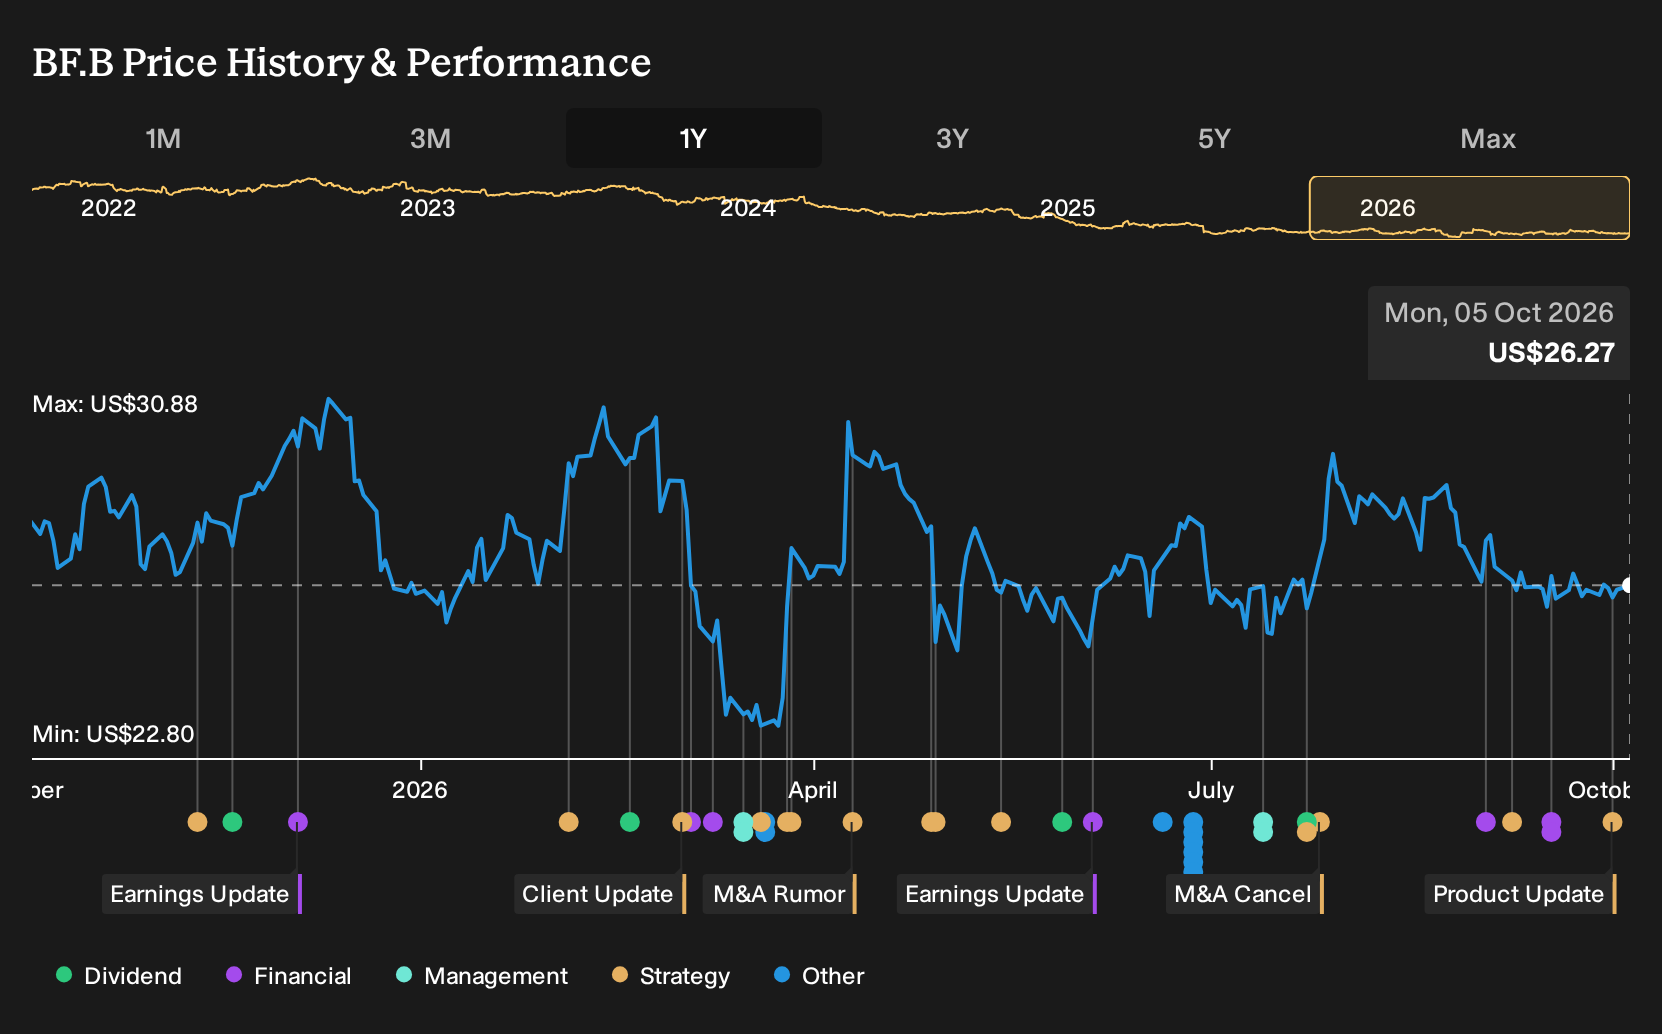
Discover why Brown-Forman's fair value indicates an 8% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view says the real swing factor for Brown-Forman is not premium launches like this 14 year single barrel, but pressure on high margin tequila. The lowest analysts were pencilling in revenues of about US$3.9b and earnings near US$725.8m by 2029. That is much more cautious. Opinions differ widely, so explore multiple narratives that may shift as this release filters into forecasts.
Explore 4 other Brown-Forman fair value estimates, including one that suggests as much as 21% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Brown-Forman research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Brown-Forman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brown-Forman's overall financial health at a glance.
Looking For More Ideas Beyond Brown-Forman?
If the Brown-Forman story has you thinking more broadly about quality, pricing power and balance sheet strength, it can help to line it up against a wider pool of potential opportunities using the Simply Wall St Screener.
- For investors who care most about resilient businesses and capital preservation, filter for 31 resilient stocks with low risk scores that may better match a steady, sleep-at-night style portfolio.
- If dependable cash returns appeal to you, focus on income opportunities across markets by scanning our curated 7 dividend fortresses that meet a 5%+ yield hurdle.
- When you want to prioritize financial robustness first, build a shortlist from a list of solid balance sheet and fundamentals (25 results) and then compare those candidates to Brown-Forman on quality and consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com