
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Drawing Fresh Attention To BridgeBio Pharma (BBIO)?
BridgeBio Pharma (BBIO) has become a focus for many biotech investors after two clinically focused updates. Fresh FORTIFY Phase 3 data for BBP-418 and new acoramidis real-world results arrived within days of each other.
Against this clinical backdrop, BridgeBio Pharma’s share price has softened recently, with a 30-day share price return down 10.14% and a 90-day share price return down 13.68%, even as total shareholder return over 1 year is 23.15% and over 3 years is very large at 162.59%. This points to longer term momentum that contrasts with near term caution around how new data and regulatory milestones might reshape the risk profile.
Spot 19 high quality undiscovered gems that, like BridgeBio Pharma after these data releases, could see sentiment shift quickly as pipelines mature and real-world evidence builds.BridgeBio Pharma now trades at a steep implied discount to both analyst targets and intrinsic value estimates after the recent pullback. Is that a genuine margin of safety or a fair price for elevated clinical and regulatory risk?
Most Popular Narrative: 169% Overvalued
BridgeBio Pharma closed at $67.25, while the most followed narrative pegs fair value at $25.00, which implies a very large premium to that estimate and frames the current pullback as only a partial reset.
The "BridgeBio Commercial Bonanza" is priced for perfection, treating the upcoming Acoramidis launch as an automatic cash cow while ignoring a brutal multi-front commercial dogfight. Here is why the market is mispricing the structural hurdles for BBIO:
See why 4 investors see BridgeBio Pharma as 169% overvalued.
Result: Fair Value of $25.00 (OVERVALUED)
Still, BridgeBio Pharma could see this bearish script unravel if Acoramidis uptake outpaces expectations or if additional BBP-418 data shifts perceived competitive pressure.
Find out about the key risks to this BridgeBio Pharma narrative.
Another View On BridgeBio Pharma’s Value
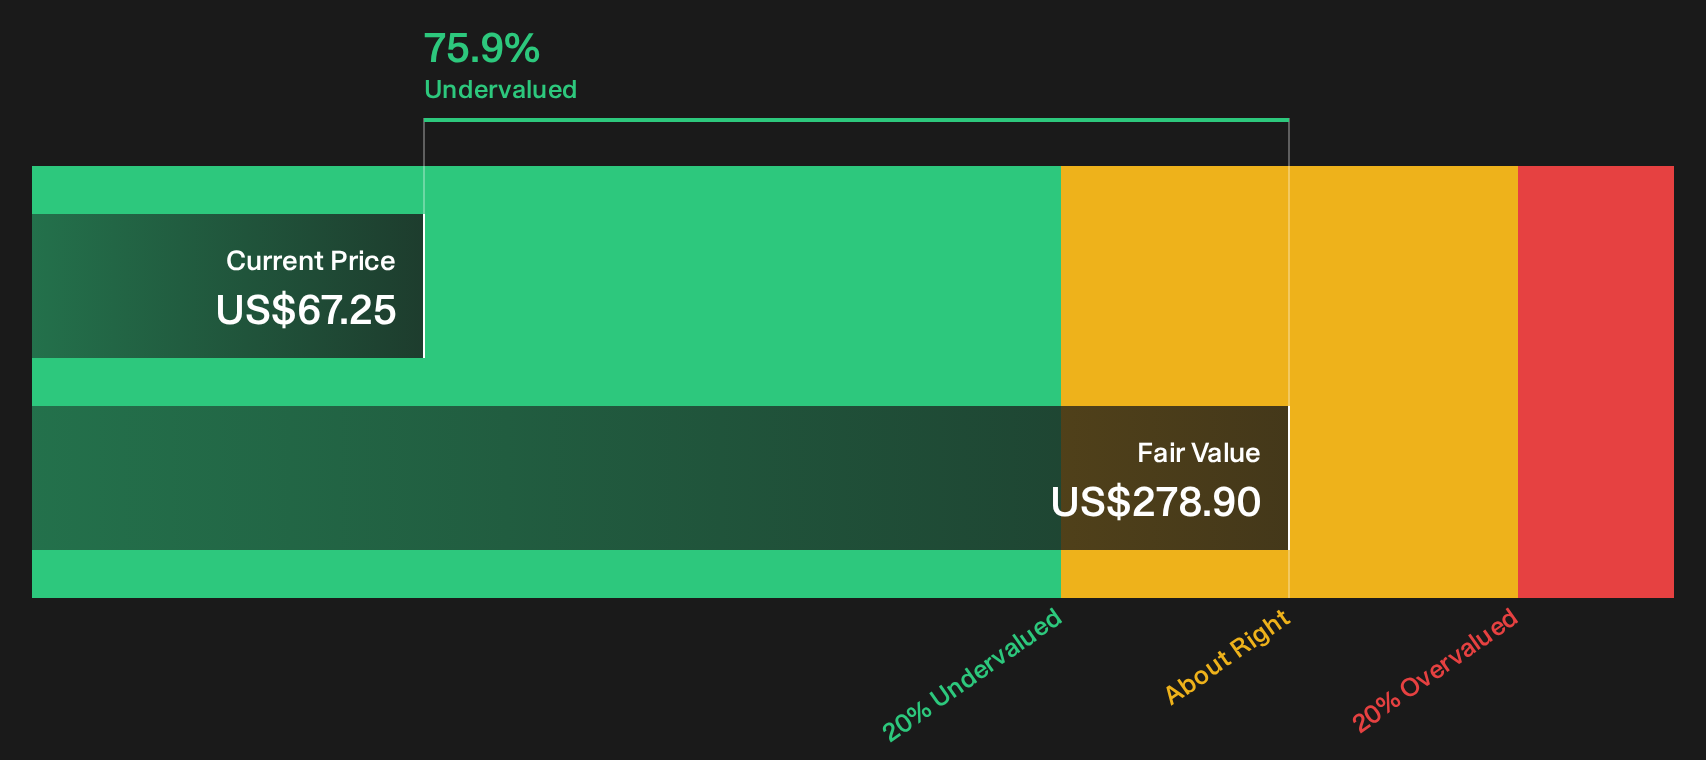
The narrative calling BridgeBio Pharma 169% overvalued sits uncomfortably next to our DCF model. That model values future cash flows at $278.90 per share, which is very far above the current $67.25 price and framed as trading 75.9% below fair value.
If a cash flow based estimate points to a large discount while a story driven fair value flags excess optimism, the real question is which set of assumptions you trust more when clinical risk, competition and funding needs are all in play.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed sentiment on BridgeBio Pharma after these valuation clashes makes sense, so act while the data is fresh and study both sides of the thesis by weighing 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond BridgeBio Pharma?
BridgeBio Pharma is only one opportunity. Widen the lens now and let fresh ideas compete for a place in your portfolio before the next move arrives.
- Target steady compounding potential by reviewing 31 high quality undervalued stocks that pair compressed valuations with solid underlying fundamentals.
- Prioritize sleep-at-night resilience through the 31 resilient stocks with low risk scores and keep your downside profile front and center.
- Strengthen portfolio quality by scanning the list of solid balance sheet and fundamentals (25 results) so your capital works inside sturdier financial structures.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com