
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Trump Looks Set to Give Vistra Stock a $4 Billion Boost
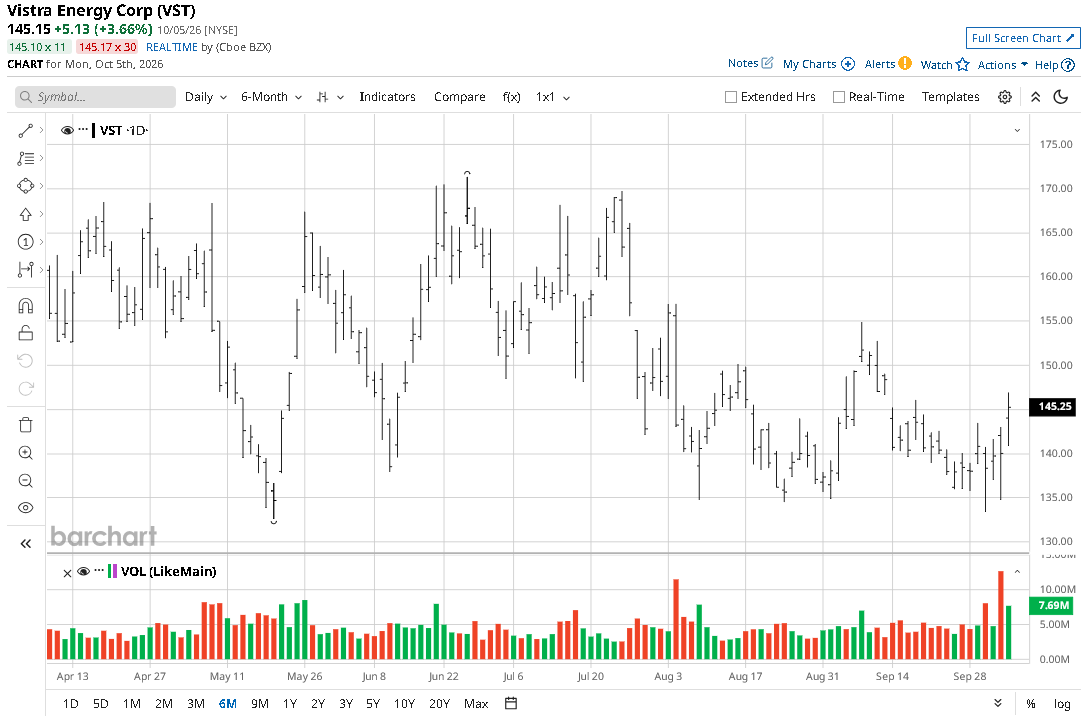
Vistra (VST) stock opened in the green on Monday following reports that President Donald Trump's administration is finalizing a massive federal support package for the clean energy company. Chris Wright, U.S. Energy Secretary, is set to visit its Perry Nuclear Power Plant to officially announce up to $4.2 billion in government-backed loans aimed at upgrading three of VST’s nuclear facilities.
Despite today’s rally, Vistra stock is trading about 12% below its price at the start of this year.
Why the Federal Loan Matters for Vistra Stock
The prospective federal loan facility aligns with President Trump’s aggressive push to quadruple overall U.S. nuclear energy capacity to 400 gigawatts by 2050. By offering low-cost government financing to upgrade Vistra’s nuclear fleet, including the Perry facility and additional assets in Ohio and Pennsylvania, the White House aims to secure reliable, base-load power for critical domestic infrastructure.
For VST shares, this subsidized capital is constructive as it de-risks expensive plant modernization projects, reduces debt-refinancing pressures, and strengthens long-term cash flow visibility without diluting existing shareholders.
A 0.63% dividend yield makes the clean energy stock even more attractive as a long-term holding.
VST Shares Are Attractively Priced in Late 2026
Vistra shares remain one of the premier beneficiaries of the rapidly growing AI power demand.
As hyperscalers continue to seek long-term power purchase agreements (PPAs), the firm’s diverse portfolio — spanning nuclear, solar, and energy storage — provides a resilient hedge against volatile spot-market pricing.
In fact, Vistra has already secured massive, multi-year agreements with Meta (META) and Amazon (AMZN), which is partly why high-profile names like Nancy Pelosi and Peter Thiel are currently invested in it.
Investors should also note that VST is currently trading at a forward price-to-earnings (P/E) ratio of under 16x, which makes it significantly cheaper to own than rival Constellation Energy (CEG) at about 21x.
Wall Street Remains Bullish on Vistra
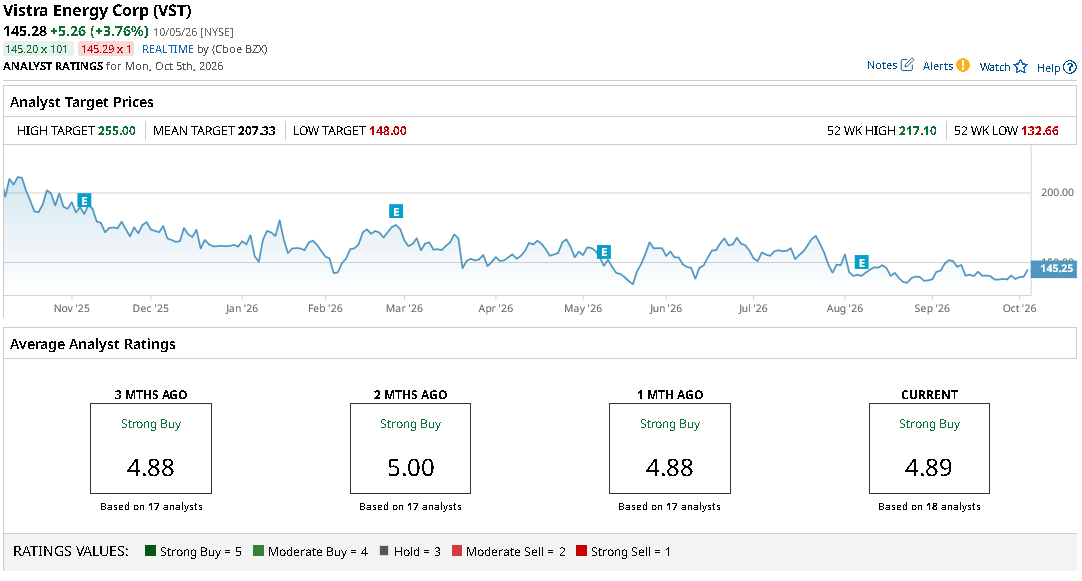
Wall Street analysts also remain bullish as ever on VST stock for the remainder of 2026.
The consensus rating on Vistra sits at “Strong Buy” currently, with the mean price objective of about $338 indicating potential upside of more than 25% from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.