
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Did The Market Misjudge About South Indian Bank?
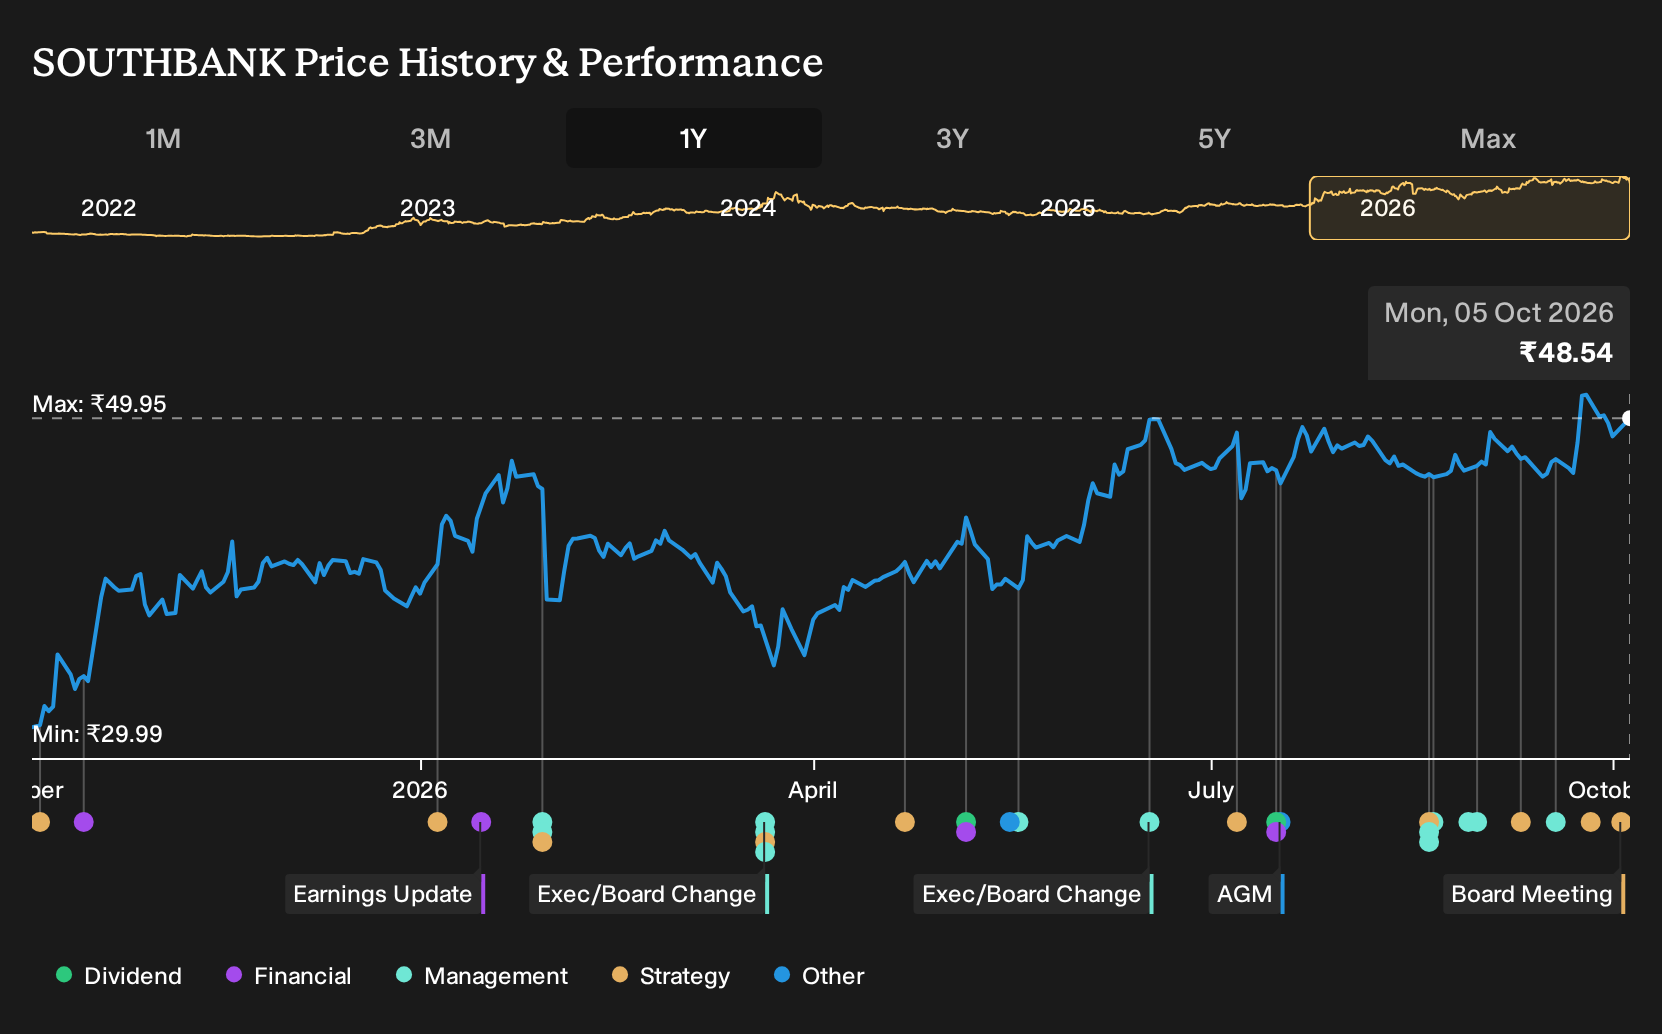
If you only glanced at South Indian Bank’s latest figures, the story might look straightforward. Investors who held South Indian Bank over the past year are up 63.4%, including dividends. That gain came while analysts were split between a bullish digital lending and MSME expansion pitch and a much more cautious view focused on fintech competition and regulatory cost. If you had been deciding back in October 2025, what exactly in that messy record would have justified taking the risk?
If the move has made South Indian Bank harder to judge, start where the gap is still open and scan 189 high quality undervalued stocks.
The Two South Indian Bank Stories Investors Had In Front Of Them
The shares cost ₹29.78 at the start of the period, and anyone looking at South Indian Bank then was really choosing between two very different but plausible stories.
On the optimistic side, the view that “Digital Lending And MSME Focus Will Expand Opportunities” argued that a Fair Value of ₹35.57, or what the stock might be worth if its thesis played out, reflected faith in new digital lending platforms and expansion into MSME and retail credit outside Kerala.
The camp that believed “Fintech Disruption And Compliance Burdens Will Cripple Future Performance” pointed to a Fair Value of ₹25, based on worries that slower digital transformation would leave the bank exposed to fintech competition and higher regulatory costs that could pressure profitability.
What The Results Changed For South Indian Bank
The clearest new fact was the Q1 2027 report. South Indian Bank booked total revenue of ₹13,199.7m and net income of ₹3,776.6m, up from ₹12,150m and ₹3,221.7m a year earlier, with net margin moving from 26.5% to 28.6%. That combination of higher profit and fatter margin indicated a more favorable profitability picture.
The takeaway is simple. When a thesis hangs on better economics from digital and MSME lending, you track net margin and absolute profit in each result and see whether both move together or drift apart.
What South Indian Bank’s Price Already Builds In
South Indian Bank now trades at ₹48.54. The selected Narrative places its Fair Value above that level and ties the gap to a push beyond its Kerala and Tamil Nadu base, along with new fee streams from credit cards and wealth management.
As a buyer today, you would be judging whether South Indian Bank can grow a younger, nationwide customer franchise fast enough to support that higher figure.
"Business Prospects: Plans to enter new business segments, including the launch of credit cards and a wealth management division. Although the bank currently has co-branded credit cards, the plan is to also go solo."
One Narrative disagrees with today's price. → See where this Narrative says South Indian Bank should trade
Looking Beyond South Indian Bank
Once you have an opinion on South Indian Bank, the next step is context. You can compare it with a larger lender built around cross border wealth.
That institution leans on fee income from investment and insurance products. It also runs a wealth arm that manages client assets globally.
The same themes you watch at South Indian Bank, such as demand for savings and protection products, appear there at greater scale.
If those flows change, the impact shows up in wealth fees, interest income and cost controls.
Comparing them side by side highlights how similar trends can shape very different banking models and clarify your own risk comfort.
One Narrative has already put a figure on it. → Uncover the company trading 23% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com