
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Security Driven Demand Might Change The Case For Investing In El Al Stock (TASE:ELAL)
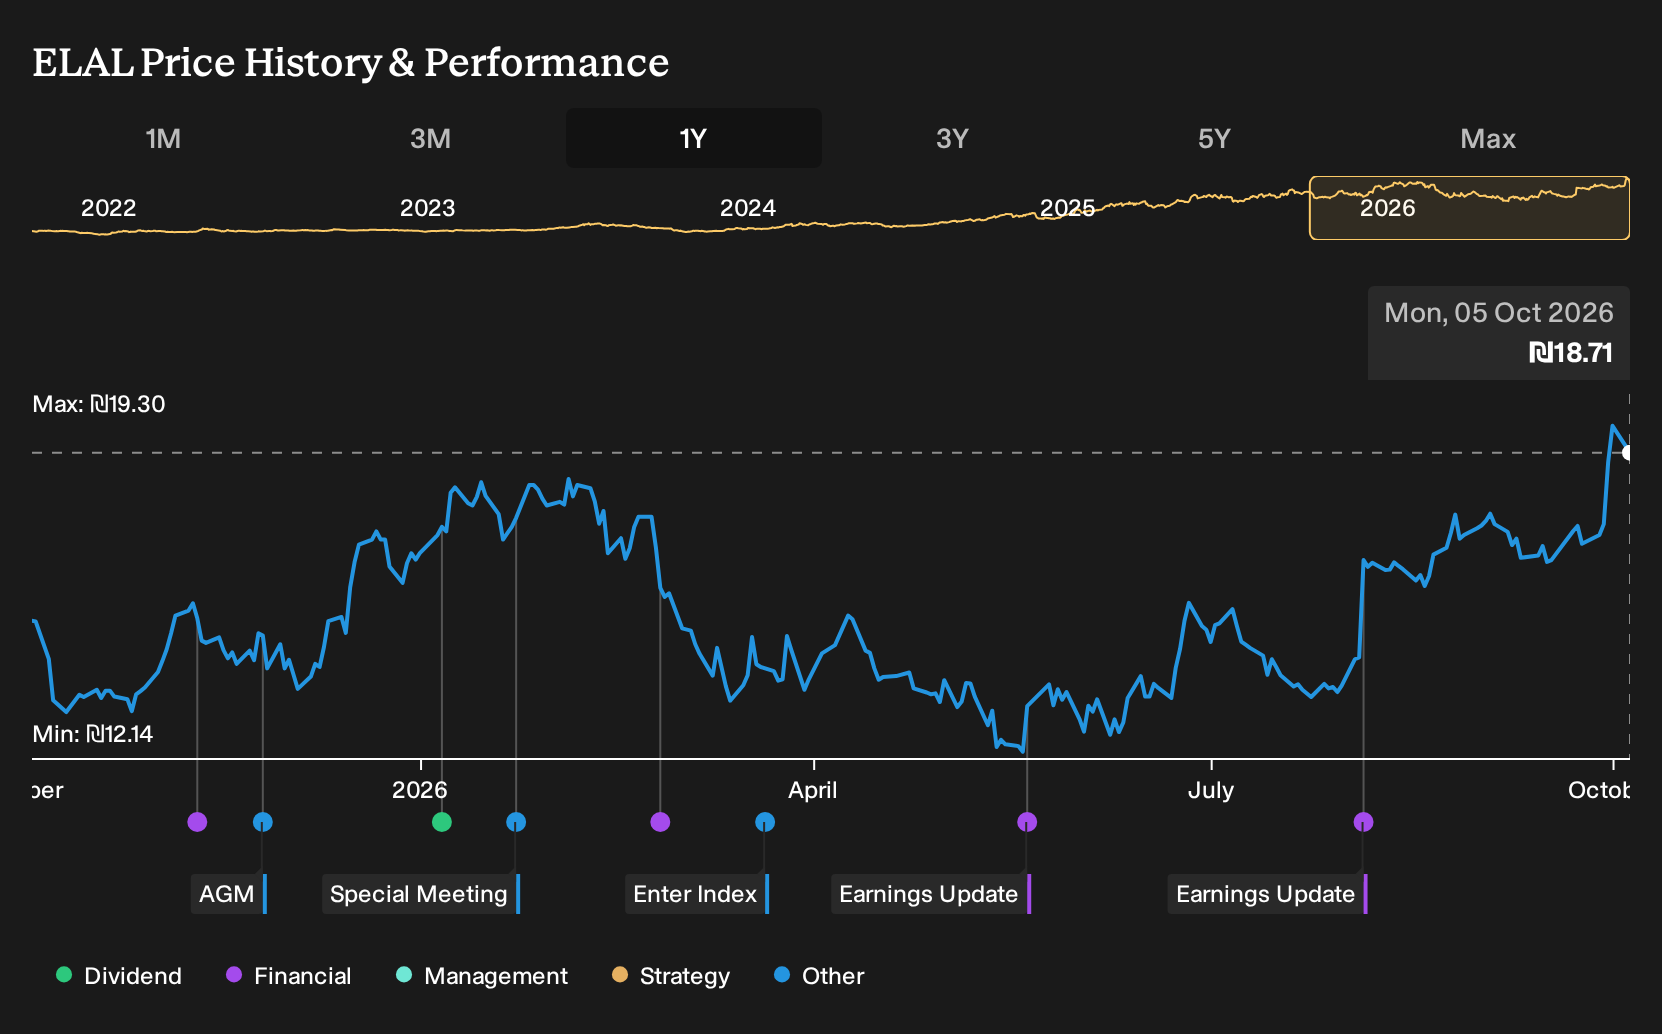
- El Al Israel Airlines is being considered for promotion to the flagship Tel Aviv 35 Index after a period of strong profitability, including a cumulative net profit of US$1.04b since October 2023, and increased traveler preference for Israeli carriers following a recent security incident involving flydubai.
- The carrier currently holds dominant market share on key routes, and the recent security event has reinforced local demand for its flights as travelers reassess perceived safety differences between Israeli airlines and foreign competitors, particularly Gulf carriers.
- We will now look at how El Al Israel Airlines’ potential Tel Aviv 35 inclusion might reshape the investment narrative around its demand profile.
Scan how investors are reacting to El Al Israel Airlines’ security premium and index story, then contrast it with a curated group of 226 resilient stocks with low risk scores that are riding similar demand for perceived resilience.
What Is El Al Israel Airlines' Investment Narrative?
To own El Al Israel Airlines, you need to believe the recent security premium is more than a passing reaction and that the carrier can convert it into steady passenger volume and pricing power. The flydubai incident has clearly pushed more local travelers toward Israeli carriers in the near term, which supports aircraft utilization and load factors. Index inclusion in the Tel Aviv 35, if it happens, would mainly affect trading liquidity and fund flows, not the underlying route economics.
The tougher questions sit in the mechanics of running a capital intensive airline while protecting profitability. El Al Israel Airlines earns most of its ₪3,474.1m revenue from passenger flights, with cargo and ancillary activities much smaller contributors, so any cooling in demand or yields hits fast. Net margins already compressed from 13.8% to 8.8% and earnings declined 35% over the past year, even as return on equity stayed high at 27.8%. The stock screens cheaply on several metrics, including an 11.8x P/E versus both local peers and a modelled future cash flow value, but that only matters if execution holds.
Even so, the real tension in the El Al Israel Airlines story is whether the same security driven demand that supports today’s numbers also magnifies the one risk that...
There's only one way to know the right time to buy, sell or hold El Al Israel Airlines. Head to Simply Wall St's company report for the latest analysis of El Al Israel Airlines's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider your own judgment.
- A great starting point for your El Al Israel Airlines research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for El Al Israel Airlines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate El Al Israel Airlines' overall financial health at a glance.
Looking For More Investment Ideas Beyond El Al Israel Airlines?
After forming a view on El Al Israel Airlines, it can help to compare that opinion with other potential opportunities that fit different risk and income profiles.
- If capital preservation and steadier balance sheets matter most to you, start by reviewing a list of solid balance sheet and fundamentals (207 results) that have historically kept financial risk in check.
- If income is your priority, compare El Al Israel Airlines with a curated group of reliable payers by scanning a focused set of 162 dividend fortresses that could complement your portfolio.
- If you prefer to hunt for underfollowed opportunities, widen the net with a hand picked pool of 615 high quality undiscovered gems that combine quality fundamentals with lower profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com