
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did Thyssenkrupp Nucera KGaA (XTRA:NCH2) Move Today?
Thyssenkrupp nucera KGaA (XTRA:NCH2) just landed a new chlor alkali technology contract in Northwest China with Hongniu Lanzhou Environmental Protection Technology, centered on its latest e BiTAC v7 electrolysis platform.
The Hongniu Lanzhou contract lands at a time when thyssenkrupp nucera KGaA’s share price has edged up over the past month, with a 1 month share price return of 6.78% and a 3 month share price return of 12.43%. However, the 1 year total shareholder return is still down 27.04% and the 3 year total shareholder return has fallen 51.62%, so recent momentum is improving off a weak longer term base around €8.50.
Scan beyond thyssenkrupp nucera KGaA and this new China contract by reviewing a curated set of industrial and infrastructure plays in the 40 power grid technology and infrastructure stocks.
For thyssenkrupp nucera KGaA, a 6.78% one month gain after heavy three year losses raises a simple tension: Is this just a catch up rally, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 21% Undervalued
On the most followed view, thyssenkrupp nucera KGaA screens as meaningfully cheaper than an implied fair value of €10.74, based on a discount rate of 6.53% and long dated hydrogen project assumptions.
The increasing volume of paid FEED (Front-End Engineering Design) and engineering contracts, especially in Europe, which remains the most active region for green hydrogen, signals forthcoming conversion into firm, large-scale orders within 6–12 months, offering improved medium-term revenue visibility. Expansion of the service and aftermarket business in the chlor-alkali segment (with rising orders from the Middle East, Central Europe, U.S., and China) is boosting recurring, higher-margin revenues, evidenced by the stable or growing EBIT in this segment, supporting gross margin expansion and enhanced earnings quality over time.
See why 13 investors see thyssenkrupp nucera KGaA as 21% undervalued.
Result: Fair Value of €10.74 (UNDERVALUED)
Still, soft green hydrogen order intake and the risk of project delays or cancellations could quickly weaken the bullish case for thyssenkrupp nucera KGaA.
Find out about the key risks to this thyssenkrupp nucera KGaA narrative.
Another View: thyssenkrupp nucera KGaA Looks Expensive On Sales
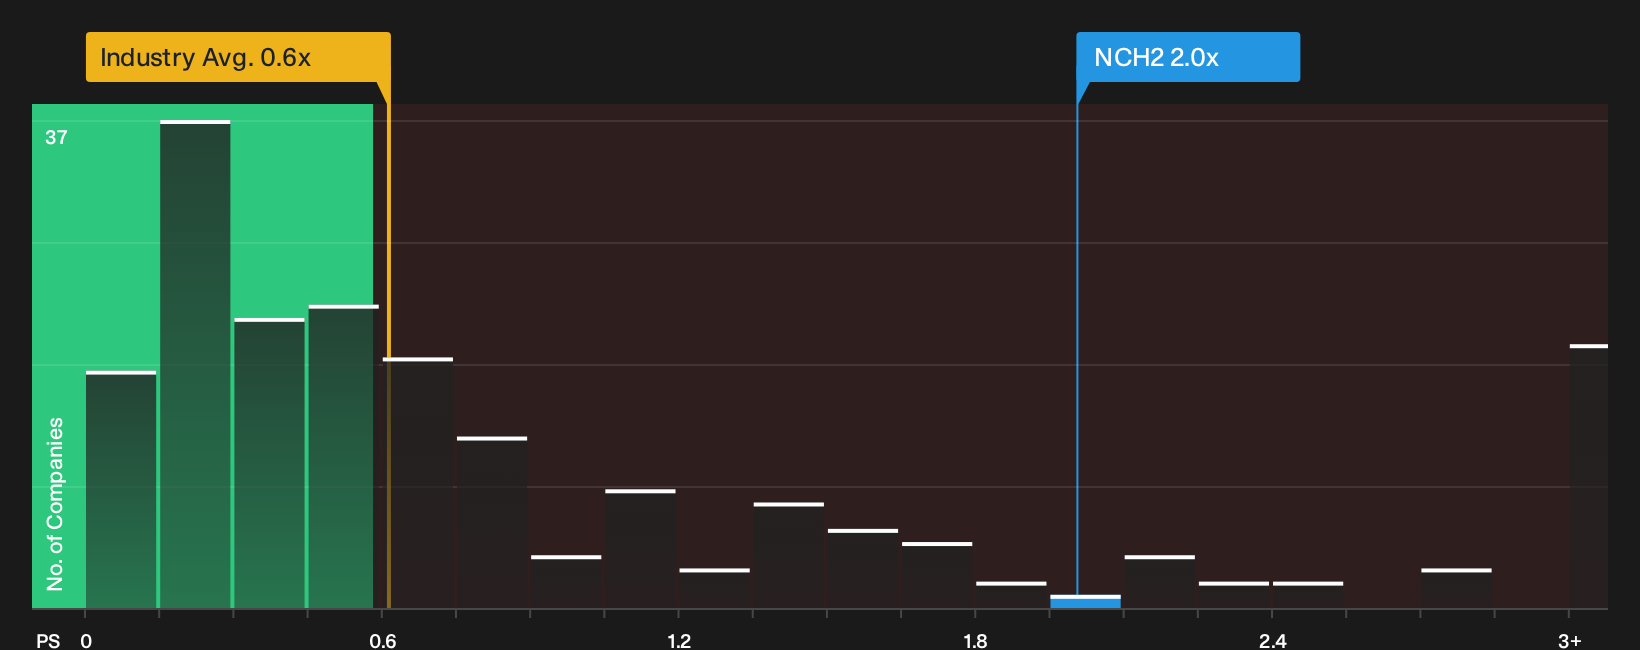
While the SWS DCF work suggests upside for thyssenkrupp nucera KGaA, the current P/S ratio of 2x paints a less generous picture. The stock trades above both European Construction peers at 0.6x and its own fair ratio of 0.5x. That gap signals valuation risk if sentiment cools.
Want to see how strongly this price case holds up when you break the numbers apart in more detail? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Optimism around thyssenkrupp nucera KGaA is clear in the valuation debate, so move quickly, inspect the data yourself and stress test every assumption. To see which potential upsides investors are focusing on, start with the 2 key rewards.
Ready for more ideas beyond thyssenkrupp nucera KGaA?
If you only stop at thyssenkrupp nucera KGaA, you risk missing other compelling setups that match your style, risk comfort, and time horizon.
- Target resilient opportunities by focusing on companies with stronger financial footing using the list of solid balance sheet and fundamentals (207 results).
- Hunt for value by scanning for attractively priced businesses with quality fundamentals in the 189 high quality undervalued stocks.
- Prioritise income and stability by checking out higher yielding candidates in the 162 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com