
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Has Amerigo Resources (TSX:ARG) Become Fully Priced On Chile Gains And Labor Progress?
Amerigo Resources stock reacts to Chile operations and labor progress
Amerigo Resources (TSX:ARG) moved higher after investors focused on recent operating results at its Minera Valle Central asset in Chile and the completion of labor negotiations that reduced near term operational uncertainty.
The recent 4.31% 1 day share price return and 11.18% 30 day share price return suggest buyers are leaning into the Amerigo Resources story, while the 99.78% year to date share price return and very large 5 year total shareholder return show how long term holders have already been rewarded.
Scan other copper exposed opportunities that are moving on operational catalysts and labor clarity with the 16 top copper producer stocks alongside Amerigo Resources.
Bulls point to Amerigo Resources’ strong Chile operations and significant recent run. Bears focus on revenue declining 16% and questions about how much is already reflected in the share price. The valuation work now has to pick a side.
Price-to-Earnings of 17.6x: Is it justified for Amerigo Resources?
Amerigo Resources closed at CA$8.95, and the current P/E ratio of 17.6x sits above the Canadian metals and mining industry average of 15.5x while remaining below the peer group average of 26.2x.
The P/E multiple compares the company’s share price with its earnings per share and gives you a quick read on how much investors are willing to pay for each dollar of profit. For a copper producer like Amerigo Resources, this yardstick often reflects how the market weighs factors such as earnings quality, balance sheet risk and exposure to a single asset or region.
Recent data paints an interesting split. ARG is described as expensive relative to the broader Canadian metals and mining group at 17.6x versus 15.5x, yet it is labelled good value against a closer peer set trading around 26.2x. With earnings growth over the past year reported at 259.1% and profit margins moving from 8.4% to 20.9%, the current valuation suggests investors are already paying up for that profitability and return on equity of 50.7%, while still assigning a discount to higher rated peers that may have more diversified operations or different risk profiles.
That tension becomes clearer once the discounted cash flow view is added. The SWS DCF model estimates Amerigo Resources’ future cash flow value at CA$3.99 per share, which sits well below the CA$8.95 market price and indicates the stock is trading materially above that specific cash flow based fair value estimate. The DCF approach projects future cash generation and then discounts those streams back to today using a required rate of return, which can be sensitive to assumptions about copper pricing, production volumes and required reinvestment at Minera Valle Central.
For a producer with earnings growing faster than the wider metals and mining industry and high reported returns on equity, it is not unusual to see multiples and intrinsic value models pointing in different directions. The current P/E of 17.6x implies the market is comfortable paying more than the sector average for today’s profitability, while the SWS DCF output of CA$3.99 signals a more conservative view on the durability and trajectory of those cash flows in Chile.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 17.6x (OVERVALUED)
Still, Amerigo Resources relies on a single Chilean operation and reported revenue declining 16%, so any disruption or weaker tolling terms could quickly challenge the current optimism.
Find out about the key risks to this Amerigo Resources narrative.
Another view on Amerigo Resources’ value
The P/E discussion presents Amerigo Resources as expensive versus the wider Canadian metals and mining group but cheaper than closer peers. Our DCF model offers a different perspective. On that framework, Amerigo Resources at CA$8.95 trades well above an estimated future cash flow value of CA$3.99 per share and screens as overvalued.
The SWS DCF model focuses on the cash Amerigo Resources is expected to generate rather than today’s earnings multiple. This means any pressure on Chilean volumes, tolling terms or costs would matter quickly. With revenue forecast to decline 16.4% per year over the next 3 years, how comfortable are you leaning on the higher market price instead of the lower cash flow estimate?
Look into how the SWS DCF model arrives at its fair value.
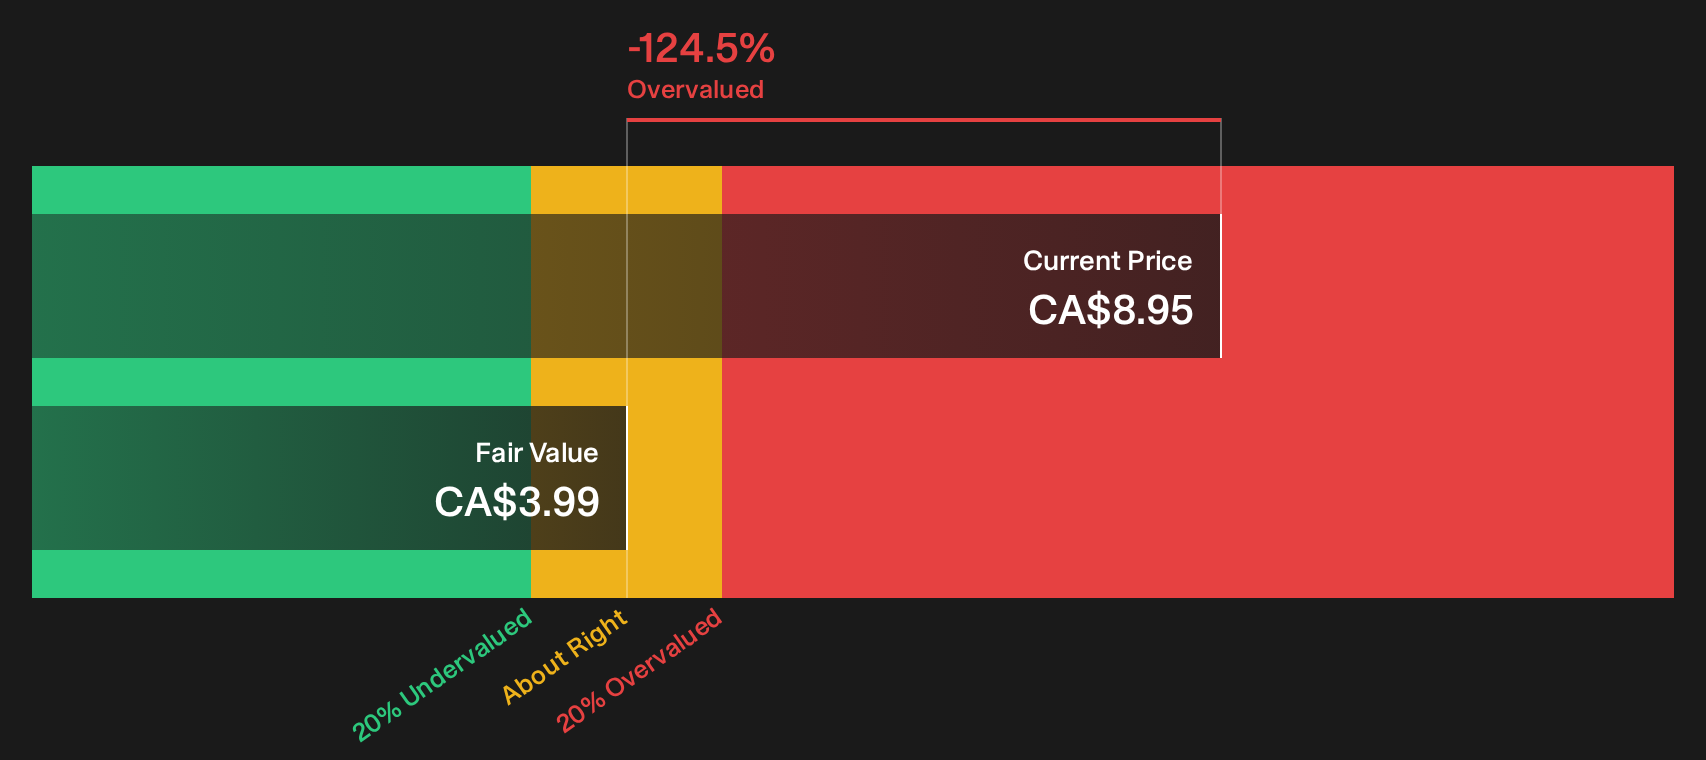
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amerigo Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Amerigo Resources is clearly split. If you want to move fast and build your own view instead of inheriting someone else's, start by weighing the 1 key reward and 2 important warning signs.
Looking for more Amerigo Resources style ideas?
If Amerigo Resources has you thinking bigger about your portfolio, do not stop at one ticker. Use the Simply Wall St screener to spot clear, data driven opportunities that others might miss.
- Target quality at a discount by scanning companies that combine resilient fundamentals with attractive pricing through the 6 high quality undervalued stocks.
- Build a steadier income stream by focusing on reliable payers and payout strength with the 1 dividend fortresses.
- Prioritise resilience by zeroing in on businesses with robust finances using the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com