
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hankyu Hanshin Holdings (TSE:9042) Just Gave Investors Something To Think About
What Hankyu Hanshin Holdings’ Expanded Buyback Means for Investors
Hankyu Hanshin Holdings (TSE:9042) has increased its share repurchase authorization by 4,500,000 shares for ¥20,000 million and extended the program to March 31, 2027, lifting the total plan to 12,000,000 shares for ¥50,000 million.
At a share price of ¥4,456, Hankyu Hanshin Holdings has delivered a year to date share price return of 10.85%. The recent 30 day share price return of 5.29% and 90 day share price return of 4.42% indicate momentum has cooled. The 5 year total shareholder return of 39.88% contrasts with a more modest 3.20% total shareholder return over the past year and a 2.97% decline over three years, which helps explain why an expanded buyback can be read as management trying to shift sentiment and perceived risk in shareholders’ favour.
See how Hankyu Hanshin Holdings’ buyback move compares with other companies showing potential value gaps in our curated list of 14 high quality undervalued stocks.
Recent returns suggest much of the easy gain may be behind Hankyu Hanshin Holdings, while the larger buyback hints that management sees more upside ahead. How does the current valuation compare with that message?
Preferred P/E of 12.8x: Is It Justified For Hankyu Hanshin Holdings?
On simple earnings terms, Hankyu Hanshin Holdings trades on a P/E of 12.8x, a level that sits below the broader JP market at 13.8x but above the JP Transportation industry at 11.6x. This points to investors paying a modest premium to sector peers while not stretching beyond the wider market.
The P/E ratio compares the current share price of ¥4,456 to the earnings generated per share. It reflects how much investors are willing to pay for each unit of profit. For a diversified group spanning rail, real estate, entertainment and logistics, earnings power matters more than pure asset value, which makes P/E a practical shorthand for how the market weighs the business mix and its profit profile.
Earnings grew by 20.9% over the past year and net profit margins improved from 5.8% to 6.6%. Forecasts point to earnings growth of 4.82% per year and revenue growth of 3.1% per year, both slower than the wider JP market. That combination can help explain why the P/E multiple is above the transportation industry average yet still below the estimated Fair P/E of 15.8x. This suggests the ratio could move closer to that fair level if the quality of earnings and consistency of results remain intact.
Against the transportation sector, the stock looks more expensive on current earnings. However, when compared with the market and an estimated Fair P/E of 15.8x, the pricing looks more restrained and leaves some room if sentiment toward Hankyu Hanshin Holdings trends toward that fair ratio.
Explore the SWS fair ratio for Hankyu Hanshin Holdings.
Result: Price-to-earnings of 12.8x (ABOUT RIGHT)
Still, if earnings growth slows from recent levels or the expanded buyback fails to lift demand, Hankyu Hanshin Holdings’ current P/E premium to its sector could compress.
Find out about the key risks to this Hankyu Hanshin Holdings narrative.
Another View On Hankyu Hanshin Holdings’ Value
The P/E check paints Hankyu Hanshin Holdings as reasonably priced, but the SWS DCF model tells a different story. On that cash flow based view, the estimated value sits at ¥2,781.83 per share, which is well below the current ¥4,456 level. That gap implies investors today are paying up for cash flows that the model values more conservatively.
For readers who want to see how that cash flow outcome is built line by line, and how sensitive it is to the assumptions baked in, Look into how the SWS DCF model arrives at its fair value.
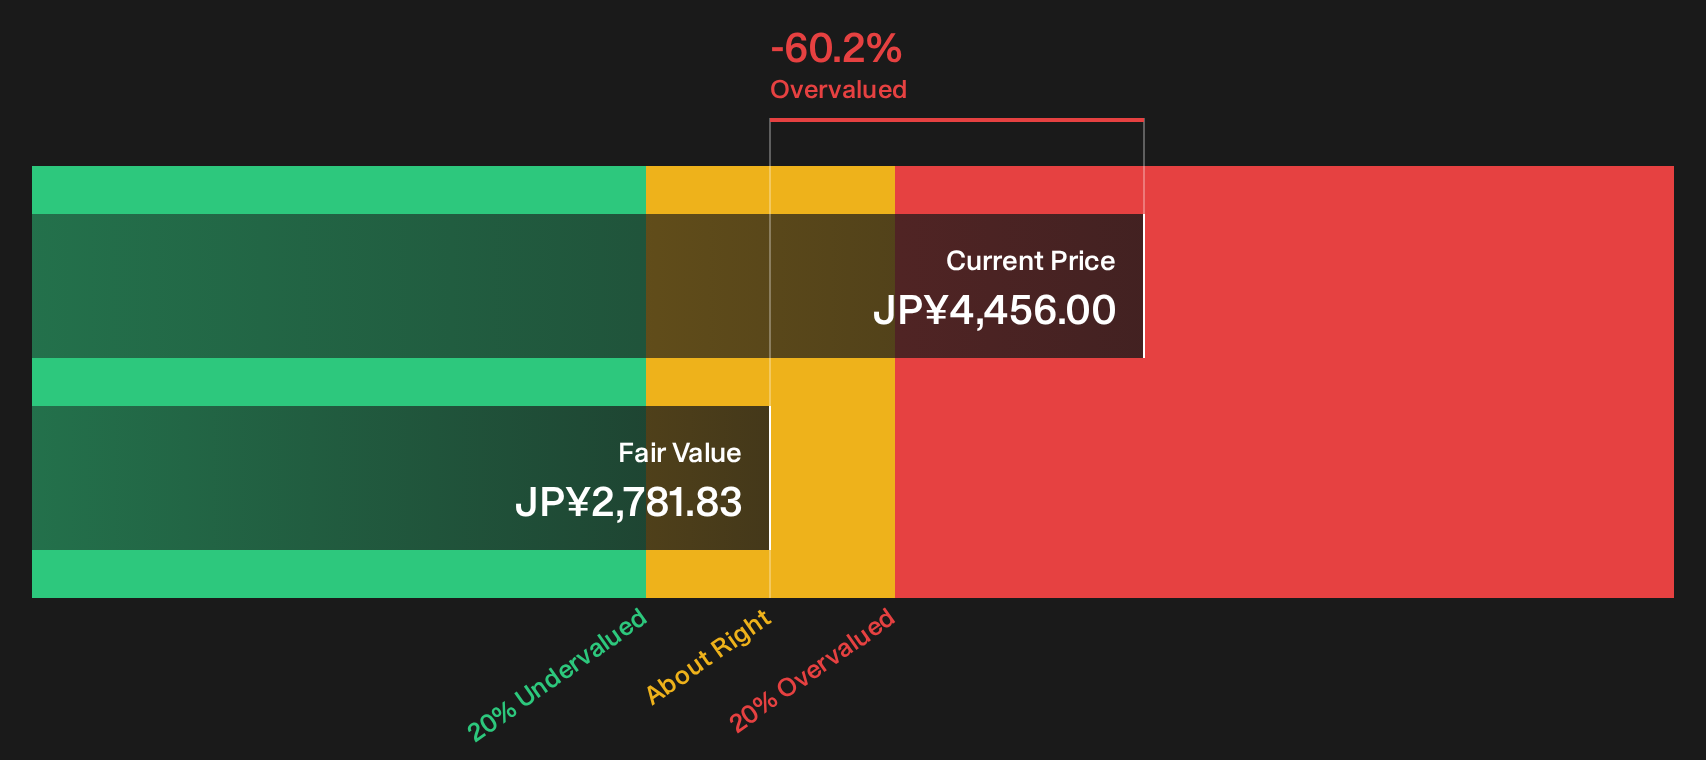
This raises a simple question for anyone assessing Hankyu Hanshin Holdings. Does the earnings based P/E comfort matter more, or does the DCF warning flag carry greater weight for your own risk tolerance?
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hankyu Hanshin Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hankyu Hanshin Holdings often create the most interesting setups, so move quickly, weigh the concerns against the positives, and check the 3 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Hankyu Hanshin Holdings?
If Hankyu Hanshin Holdings has sharpened your appetite for opportunities, do not stop here. Fresh ideas often emerge where valuation, quality and risk come together differently.
- Target resilient balance sheets and steady fundamentals by scanning companies in the list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio.
- Hunt for quality businesses that the market may be mispricing right now by reviewing the curated 14 high quality undervalued stocks.
- Spot potential future market favorites early by checking the 75 high quality undiscovered gems before other investors catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com