
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Turkey Inflation Cools and Turkish Bank Stocks Move Back Into Focus
Turkish inflation has slipped below 30% for the first time since 2021, and that cools the temperature on one of the hottest stories in emerging markets. Slower price pressure can reset how you think about risk, returns and timing, especially in rate sensitive equities. This article walks through three Turkish banks and real estate stocks from our screener that look positively exposed to this shift, and explains why the new data might matter for your portfolio.
The three Turkish banks and real estate stocks in this article are only a sample, and the full screen surfaced 8 more companies with equally compelling narratives that are not covered below. If you want to identify which rate sensitive plays line up with your own risk tolerance and macro view, go straight to the Turkish rate‑sensitive equities (banks and real estate) screener.
Turkiye Garanti Bankasi (IBSE:GARAN)
Turkiye Garanti Bankasi is one of Türkiye’s key rate sensitive banks, with a large retail and corporate loan book that channels changes in interest rates and inflation directly into households and businesses.
Turkiye Garanti Bankasi generates most of its TRY413.9b revenue from retail banking at about TRY233.7b and corporate banking at roughly TRY204.3b, with investment banking a smaller negative contributor, and the stock carries a market value of about TRY528.8b.
"Although Turkiye Garanti Bankasi still reports the highest NIM among major private peers with core NII growth in early 2026, higher than expected Central Bank funding costs and aggressive TL deposit pricing since March 2026 have already forced management to cut its 2026 NIM expansion expectation to only 20 to 40 basis points over 2025, which could leave future net interest income and earnings more exposed if funding pressure persists."
What happens if that single pressure point eases just as disinflation continues could make a meaningful difference to future profitability.
If that pressure starts to ease, the full full narrative for Turkiye Garanti Bankasi provides a detailed explanation of how Turkiye Garanti Bankasi could recalibrate earnings power, risk and optionality beyond headline NIM guidance.
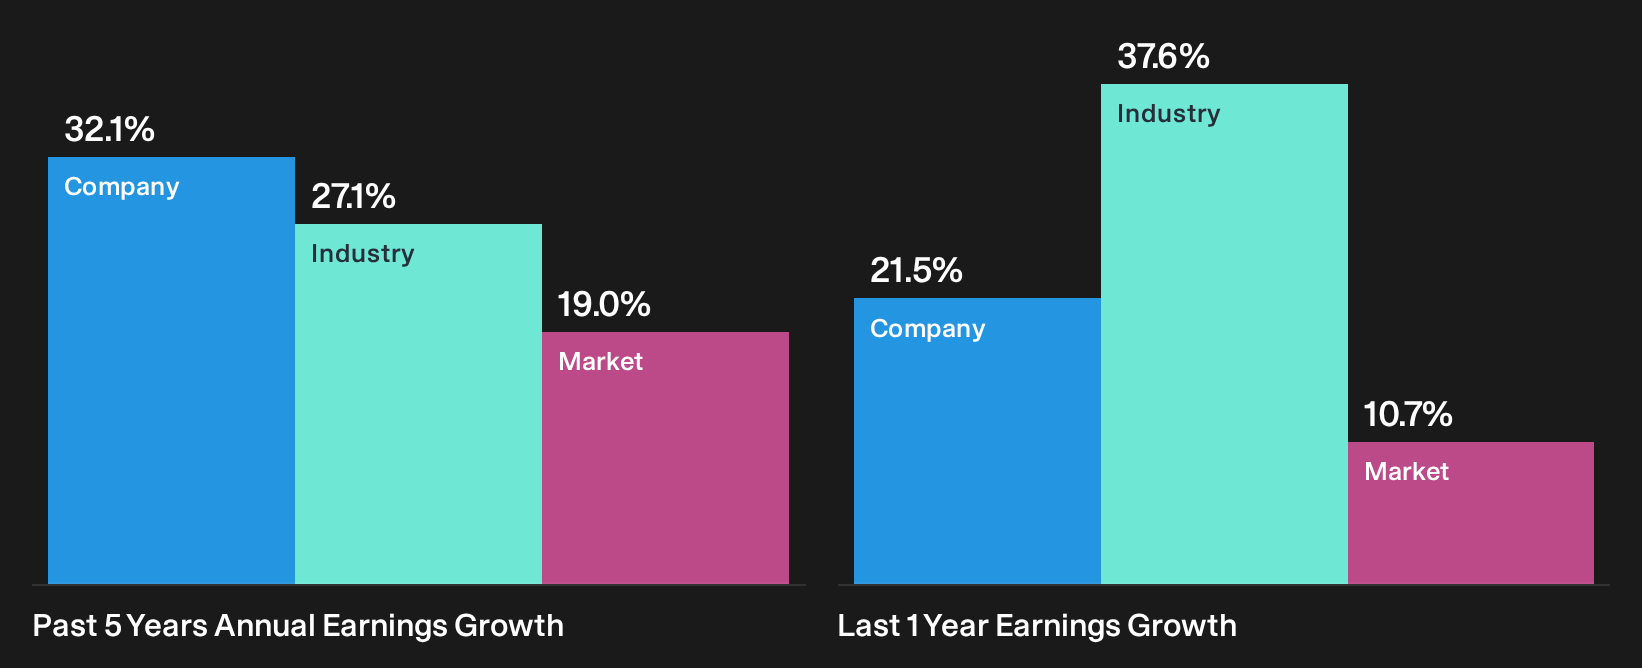
Yapi ve Kredi Bankasi (IBSE:YKBNK)
Yapi ve Kredi Bankasi is a large Turkish lender tied closely to the rate cycle, with retail and commercial credit across the country that pulls its earnings directly into the inflation and funding story investors care about in this screener.
Yapi ve Kredi Bankasi generates most of its TRY273.4b revenue from Retail Banking at about TRY114.0b, Commercial and SME Banking at roughly TRY67.8b, and Treasury and other activities near TRY51.7b, with a market value of around TRY295.1b.
For this rate sensitive theme, Yapi ve Kredi Bankasi matters because it is one of the main conduits between Turkish households, businesses, and the Central Bank’s policy choices. Shifts in inflation, loan demand, and deposit pricing can all feed quickly into profitability.
"Expansion in digital banking services and increased financial inclusion in Türkiye are expected to drive growth in the customer base, leading to higher deposit growth and greater cross-sell opportunities, which should support long-term revenue expansion."
The real test for that story comes if one quiet pressure on funding costs and loan pricing changes direction faster than investors expect.
If that inflection arrives sooner than the market prices in, the full narrative for Yapi ve Kredi Bankasi explains how Yapi ve Kredi Bankasi’s digital reach, funding mix and risk profile could be quietly decoupling.

Türkiye Vakiflar Bankasi Türk Anonim Ortakligi (IBSE:VAKBN)
Türkiye Vakiflar Bankasi Türk Anonim Ortakligi is closely linked to the Turkish rate sensitive environment, with a state connected balance sheet that channels shifts in inflation, funding costs and loan demand directly into corporate, SME and agricultural borrowers.
Türkiye Vakiflar Bankasi Türk Anonim Ortakligi focuses on corporate, commercial, SME and agricultural lending, while also offering retail and digital services, and reports around TRY196.5b from corporate and commercial banking plus TRY244.4b from treasury and investment activities, with a market value near TRY329.0b.
"Its state-backed position and diverse funding access support leadership in infrastructure and green financing, creating a differentiated revenue stream."
A single favorable shift in one key element of its funding costs could have a greater impact than the headline narrative implies.
That funding shift is exactly where the full narrative for Türkiye Vakiflar Bankasi Türk Anonim Ortakligi shows how Türkiye Vakiflar Bankasi Türk Anonim Ortakligi could turn state backing into accelerating, rate driven upside potential.

Curious About Fresh Alternatives?
New themes keep breaking out while older ideas lose momentum. Fresh screeners surface stocks still flying under the radar for now. Do not get caught dropping behind, get in early.
- Spot robust balance sheets before the crowd by reviewing the curated list of solid balance sheet and fundamentals (207 results), built to highlight financially steady businesses while that information still really matters.
- Review potential income opportunities by scanning the hand picked 162 dividend fortresses and see which high yield payers could help keep portfolios supported when prices move around.
- Explore long run infrastructure shifts by checking the focused 40 power grid technology and infrastructure stocks and track companies involved in grid upgrades while valuations still look fresh.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com