
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
First International Bank Of Israel (TASE:FIBI) Faces Class Action, Is The Stock Cheap?
The Central Lod District Court has allowed a class action to move ahead against First International Bank of Israel (TASE:FIBI) over alleged unjust enrichment related to unpaid interest on positive current account balances.
For investors, the lawsuit lands at a time when First International Bank of Israel’s share price has been under pressure in the short term, with the stock down over the past month and year to date. However, 1-year, 3-year and 5-year total shareholder returns remain positive and reflect longer term momentum that has not fully reversed.
Compare how this legal overhang stacks up against other banks by scanning a hand picked set of 226 resilient stocks with low risk scores that may offer a different balance of stability and downside risk.
First International Bank of Israel has a long established, diversified banking franchise. However, the share price has retreated in recent months and now carries a valuation discount flag. Do the current numbers justify that gap or overstate it?
Preferred P/E of 10.5x for First International Bank of Israel: Is it justified?
First International Bank of Israel trades on a P/E of 10.5x, close to both peers and the broader Asian banks group. This points to a valuation that is broadly in line with similar lenders rather than a clear bargain or premium based on this single metric.
The P/E ratio links what investors are paying today for each ₪1 of earnings. For a mature bank such as First International Bank of Israel, where earnings are already sizeable and growth expectations are not clearly defined in the data, P/E often reflects how the market weighs earnings quality, risk, and consistency more than rapid expansion.
Here, a few signals pull in different directions. Earnings quality is flagged as high, the SWS DCF model suggests the share price of ₪225.5 is trading below an estimated future cash flow value of ₪285.71, and earnings have grown by 12.2% per year over the past 5 years. At the same time, the latest year showed an earnings decline of 8.6%, profit margins eased from 33.7% to 31.6%, return on equity of 14.5% is described as low by the screening framework, and the dividend track record is labelled unstable.
Compared with the Asian banks industry average P/E of 10.2x, First International Bank of Israel screens as slightly expensive. This suggests the market is not aggressively discounting the recent earnings and margin softness relative to regional peers. Against a closer peer set where the average P/E is 10.6x, the stock is described as good value, which underlines how small shifts in comparator groups can change the conclusion and why investors often need to look beyond a single benchmark when judging whether the current earnings multiple feels reasonable for this bank.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 10.5x (ABOUT RIGHT)
Still, the class action over unpaid interest and any further pressure on First International Bank of Israel’s profit margins could challenge the current valuation narrative.
Find out about the key risks to this First International Bank of Israel narrative.
Another View: SWS DCF Model On First International Bank of Israel
A different lens tells a different story. The SWS DCF model values First International Bank of Israel at ₪285.71 per share compared with the current ₪225.5 price, implying the stock trades at a discount based on projected cash flows rather than reported earnings multiples.
That gap offers investors a simple question. Is the legal risk and recent earnings softness enough to keep the price below what the cash flow model suggests is a reasonable level, or is the market leaning too hard on short term concerns?
Look into how the SWS DCF model arrives at its fair value.
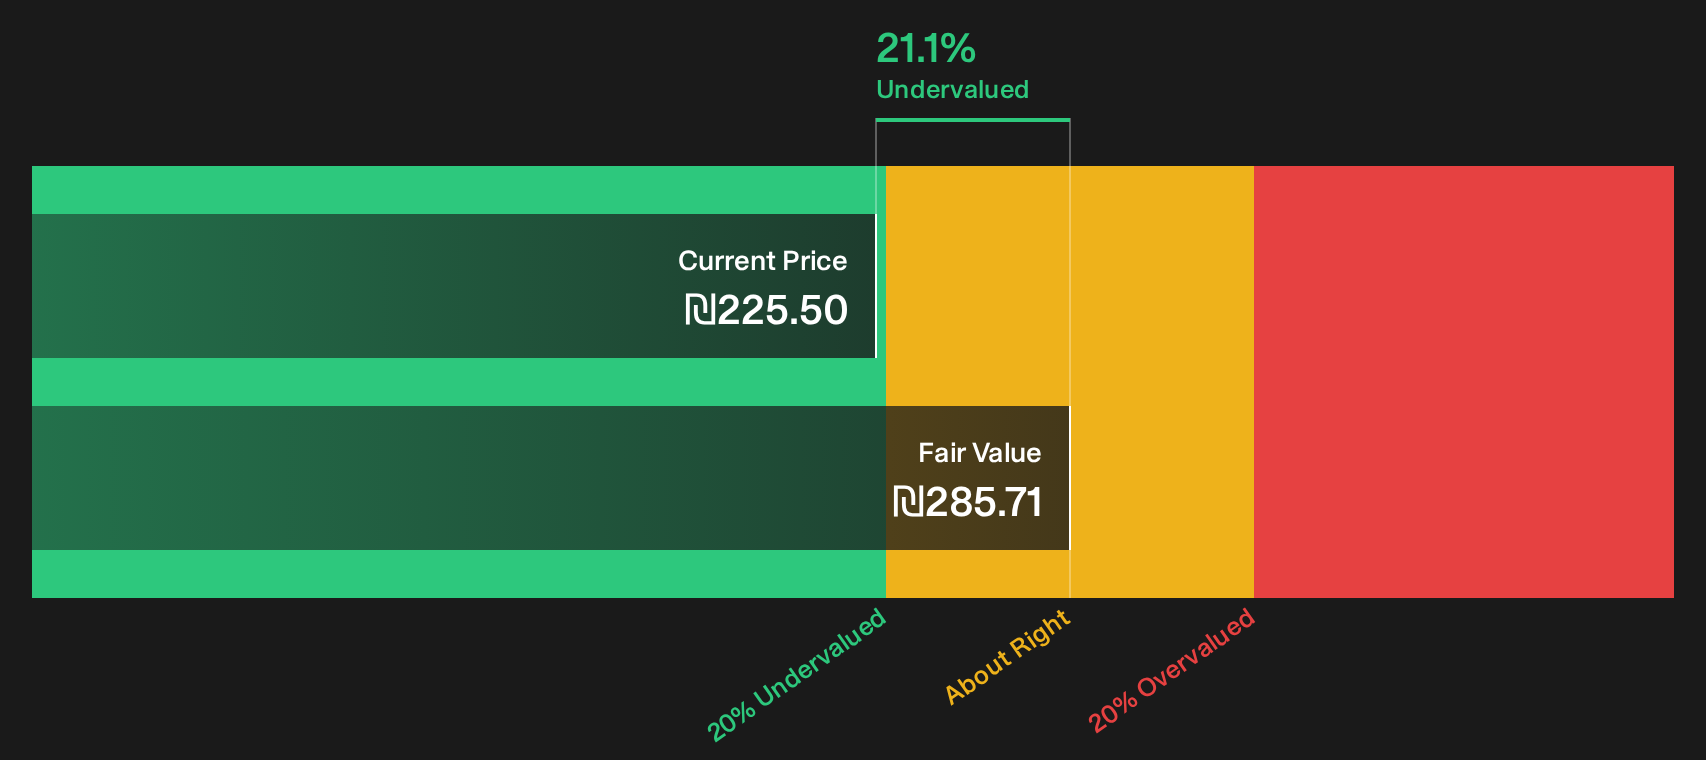
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First International Bank of Israel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 187 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on First International Bank of Israel’s risks and rewards can be confusing, so act while the details are fresh and test the numbers yourself. To weigh the trade off between potential upside and the legal and earnings questions still in play, start by reviewing the 1 key reward and 1 important warning sign
Looking for more investment ideas beyond First International Bank of Israel?
If First International Bank of Israel has sharpened your focus on risk, reward, and valuation, use that momentum and keep testing fresh opportunities with clear data on your side.
- Spot potential mispricings early by scanning a curated pool of 187 high quality undervalued stocks that pair stronger fundamentals with prices that screening models suggest are out of sync.
- Anchor your portfolio with income ideas by reviewing a shortlist of 162 dividend fortresses that combine higher yields with supporting fundamentals.
- Protect your downside by filtering for a list of solid balance sheet and fundamentals (207 results) that can help you focus on businesses with sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com