
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Growth Companies With Insider Ownership Up To 15%
The United States market has remained flat over the past week but has seen a 12% increase over the last year, with earnings projected to grow by 18% annually in the coming years. In this context, identifying growth companies with significant insider ownership can be advantageous as it often indicates strong confidence from those closest to the business.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Sable Offshore (SOC) | 11.6% | 108.7% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 14.4% | 56.4% |
| Himax Technologies (HIMX) | 29.1% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.2% |
| Dave (DAVE) | 16.7% | 24.1% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
Let's explore several standout options from the results in the screener.
Burke & Herbert Financial Services (BHRB)
Simply Wall St Growth Rating: ★★★★☆☆
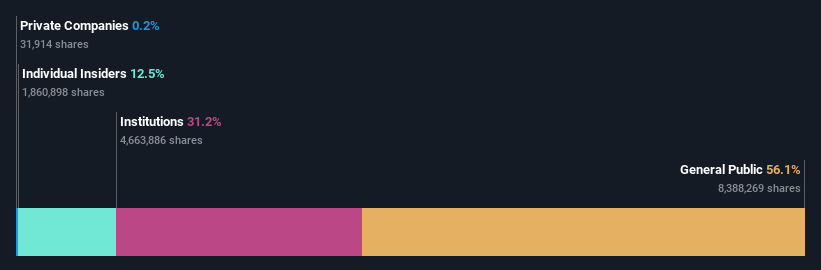
Overview: Burke & Herbert Financial Services Corp., with a market cap of $1.41 billion, operates as the bank holding company for Burke & Herbert Bank & Trust Company, offering a range of community banking products and services in the United States.
Operations: The company's revenue is primarily derived from its community banking segment, which generated $360.13 million.
Insider Ownership: 14.2%
Burke & Herbert Financial Services shows potential as a growth company with high insider ownership, despite recent insider selling. The company has announced a $100 million fixed-income offering and maintains an attractive dividend yield of 3.15%. While earnings are forecast to grow significantly at 41.5% annually, recent financial results show a decline in net income and EPS compared to the previous year. Revenue is expected to grow faster than the US market, but substantial shareholder dilution occurred recently.
- Dive into the specifics of Burke & Herbert Financial Services here with our thorough growth forecast report.
- The analysis detailed in our Burke & Herbert Financial Services valuation report hints at an inflated share price compared to its estimated value.
Pagaya Technologies (PGY)
Simply Wall St Growth Rating: ★★★★☆☆
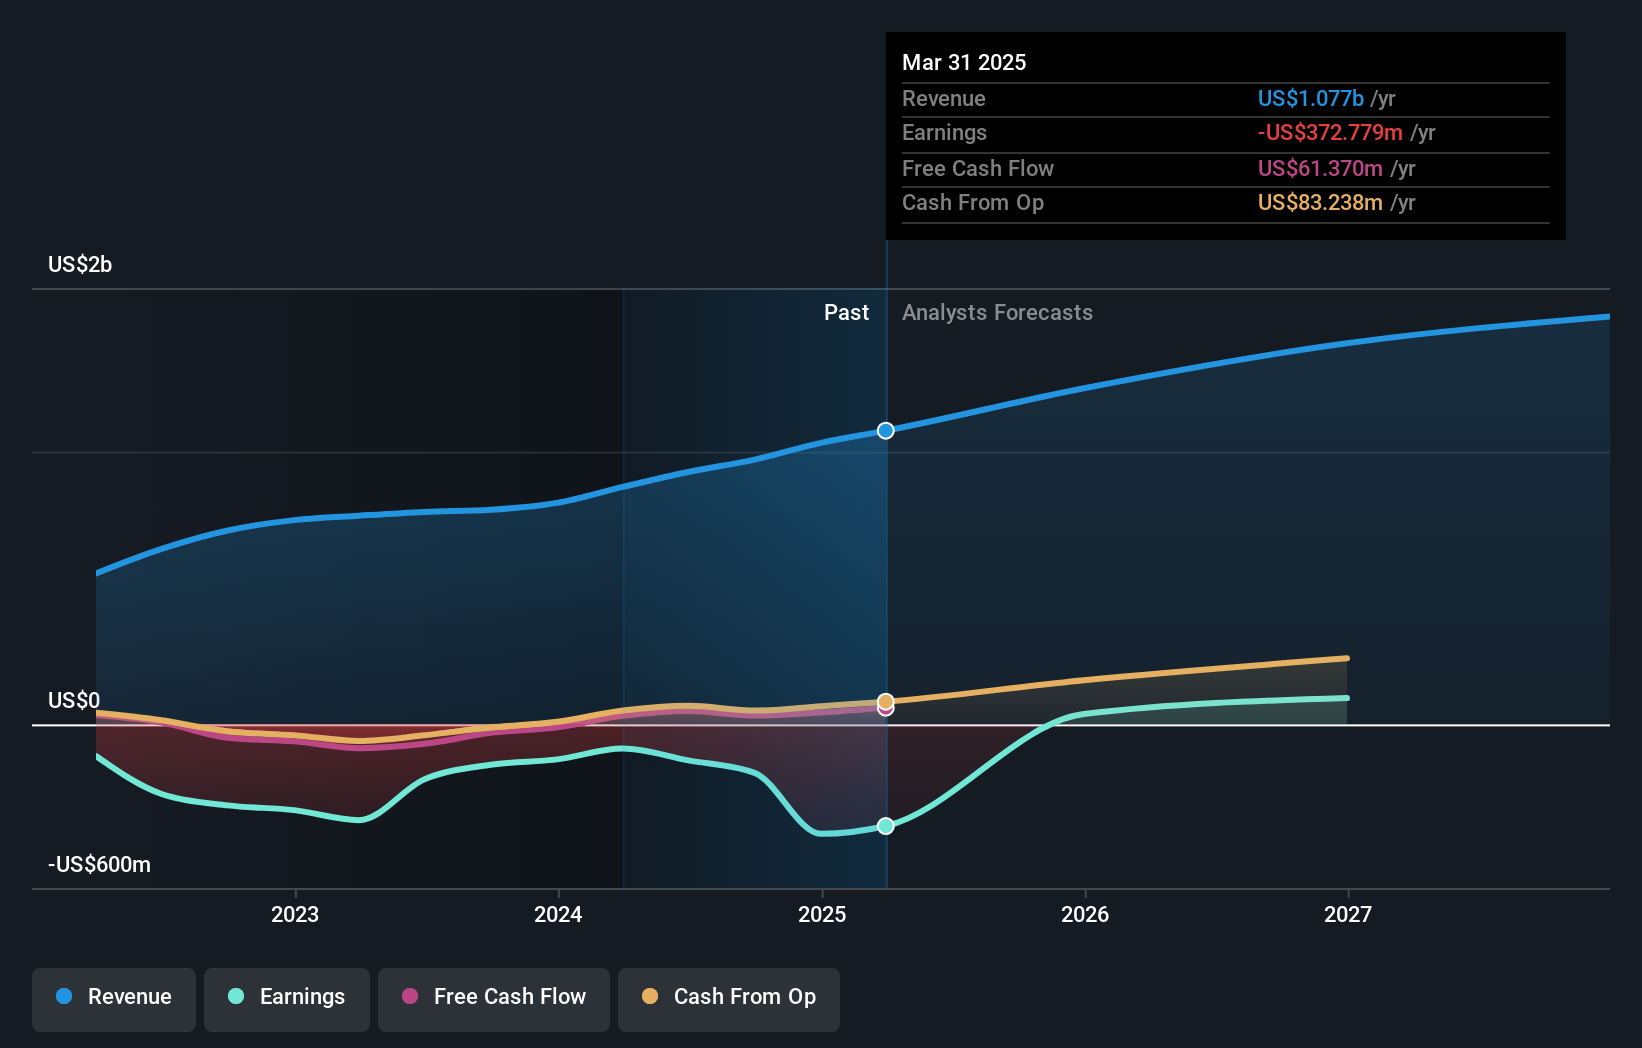
Overview: Pagaya Technologies Ltd. is a technology company that utilizes data science and proprietary AI-powered technology to enhance financial services for customers and investors in the United States, Israel, and the Cayman Islands, with a market cap of approximately $1.50 billion.
Operations: The company's revenue primarily comes from its Software & Programming segment, which generated approximately $1.39 billion.
Insider Ownership: 15.5%
Pagaya Technologies' growth potential is underscored by its strategic financial maneuvers, including a $700 million revolving credit facility to enhance loan origination. Despite slower revenue growth forecasts compared to the US market, earnings are expected to grow significantly at 36.2% annually. The company has seen more insider buying than selling recently, indicating confidence in its trajectory. Recent earnings reports highlight increased revenue and net income year-over-year, supporting Pagaya's expansion efforts in the fintech space.
- Unlock comprehensive insights into our analysis of Pagaya Technologies stock in this growth report.
- Our valuation report here indicates Pagaya Technologies may be undervalued.
Coastal Financial (CCB)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Coastal Financial Corporation, with a market cap of $614.05 million, operates as the bank holding company for Coastal Community Bank, offering a range of banking products and services to consumers and small to medium-sized businesses in Washington's Puget Sound region.
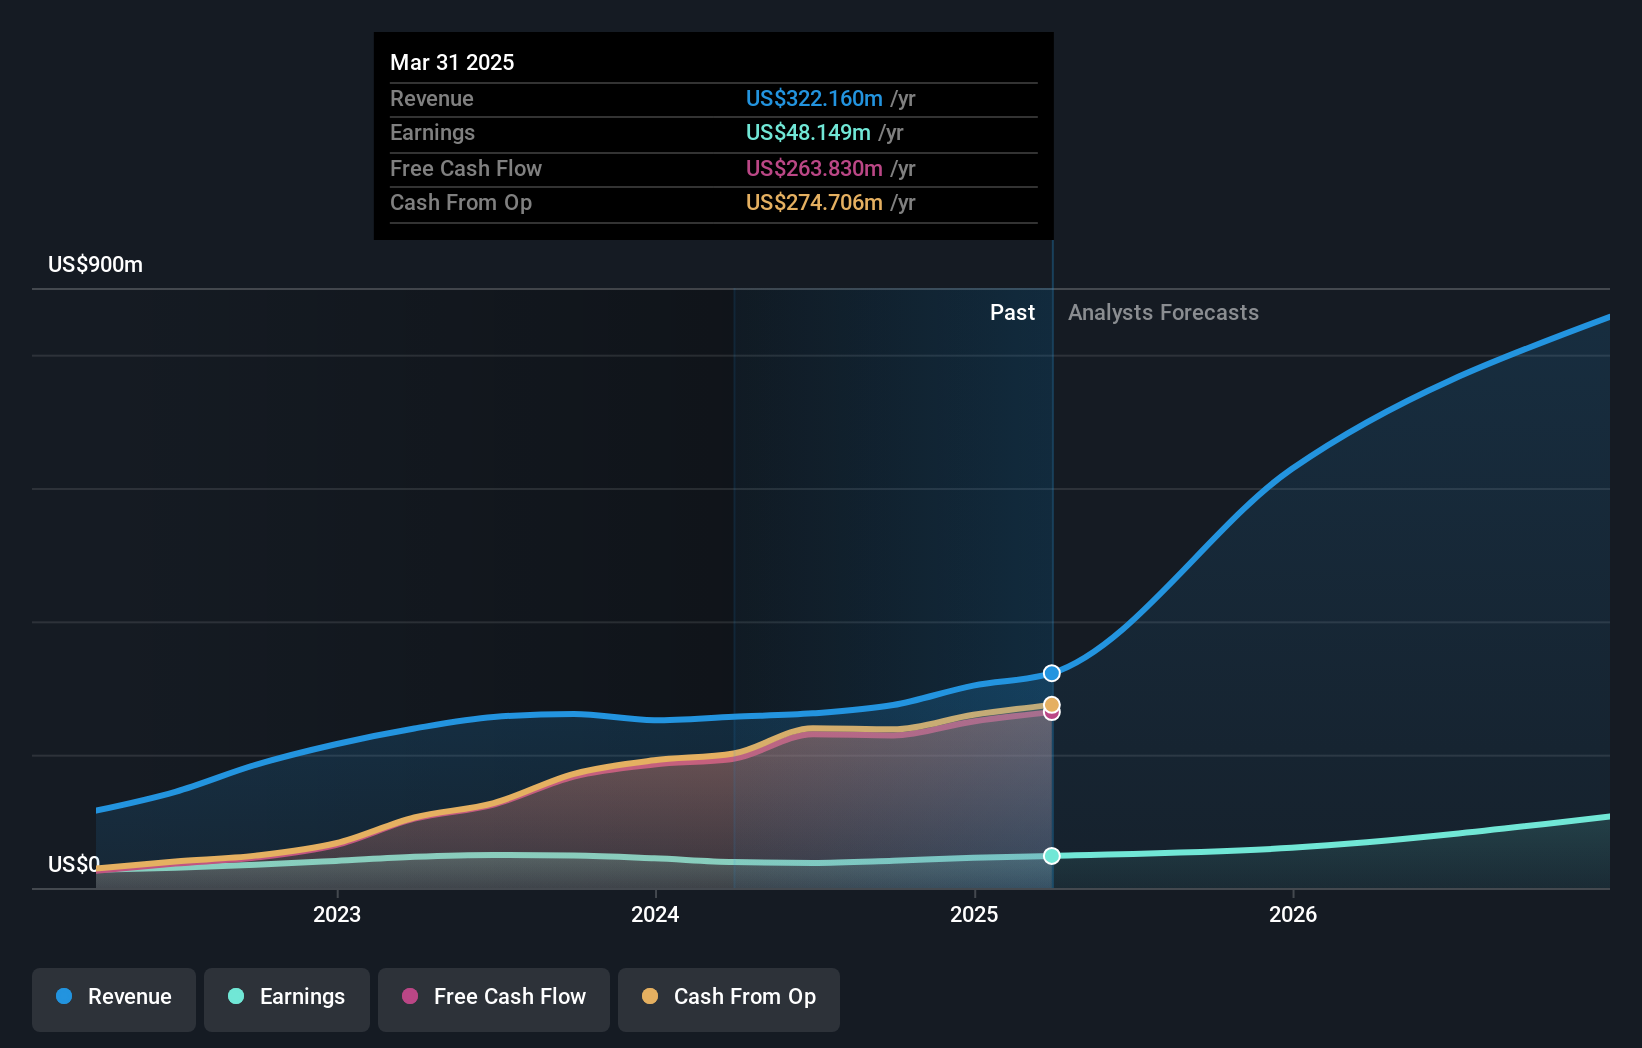
Operations: The company's revenue is primarily derived from three segments: CCBX ($248.41 million), Community Bank ($95.80 million), and Treasury & Administration ($17.81 million).
Insider Ownership: 13.8%
Coastal Financial is poised for substantial growth, with revenue expected to increase by 32% annually, outpacing the US market. Insider confidence is evident through significant recent purchases and no notable sales. However, a class action lawsuit raises concerns about the company's risk management practices, particularly regarding its CCBX business. Despite these challenges, Coastal trades 44% below its estimated fair value and analysts project a 27% price increase. The company aims to become profitable within three years amidst high earnings growth forecasts.
- Take a closer look at Coastal Financial's potential here in our earnings growth report.
- According our valuation report, there's an indication that Coastal Financial's share price might be on the cheaper side.
Taking Advantage
- Gain an insight into the universe of 183 Fast Growing US Companies With High Insider Ownership by clicking here.
- Looking For Alternative Opportunities? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com