
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Honeywell International's Quarterly Earnings Preview: What You Need to Know
Charlotte, North Carolina-based Honeywell International Inc. (HON) provides industrial automation, building automation, and energy and sustainability solutions businesses. Valued at $67.8 billion by market cap, its business is aligned with powerful megatrends – automation and energy transition, underpinned by its Honeywell Accelerator operating system and Honeywell Forge IoT platform. The diversified industrial conglomerate is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Thursday, Oct. 22.
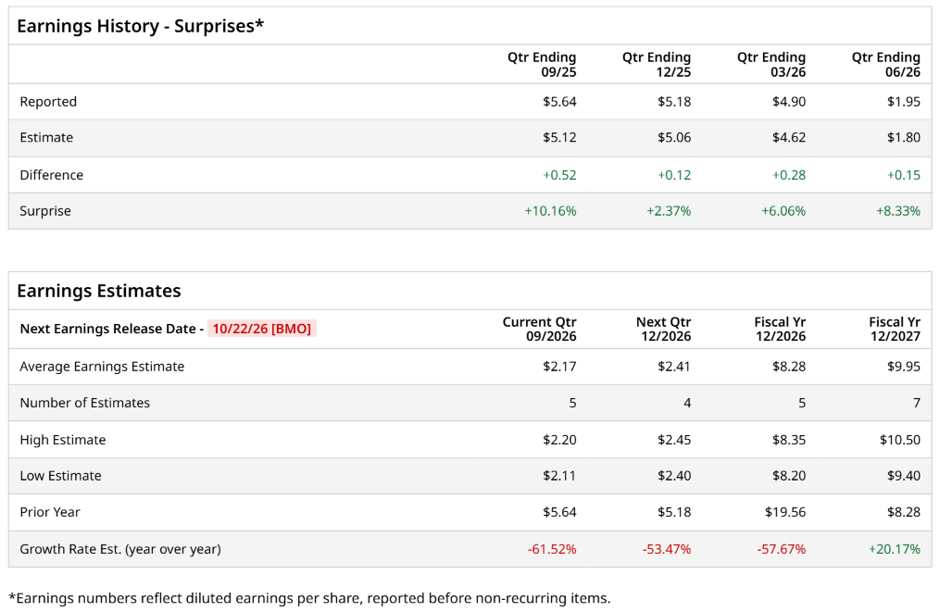
Ahead of the event, analysts expect Honeywell International to report a profit of $2.17 per share on a diluted basis, down 61.5% from $5.64 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Honeywell International to report EPS of $8.28, down 57.7% from $19.56 in fiscal 2025. However, its EPS is expected to rise 20.2% year over year to $9.95 in fiscal 2027.
HON stock has underperformed the S&P 500 Index’s ($SPX) 15% gains over the past 52 weeks, with shares up 2.9% during this period. Similarly, it underperformed the State Street Industrial Select Sector SPDR ETF’s (XLI) 10% gains over the same time frame.
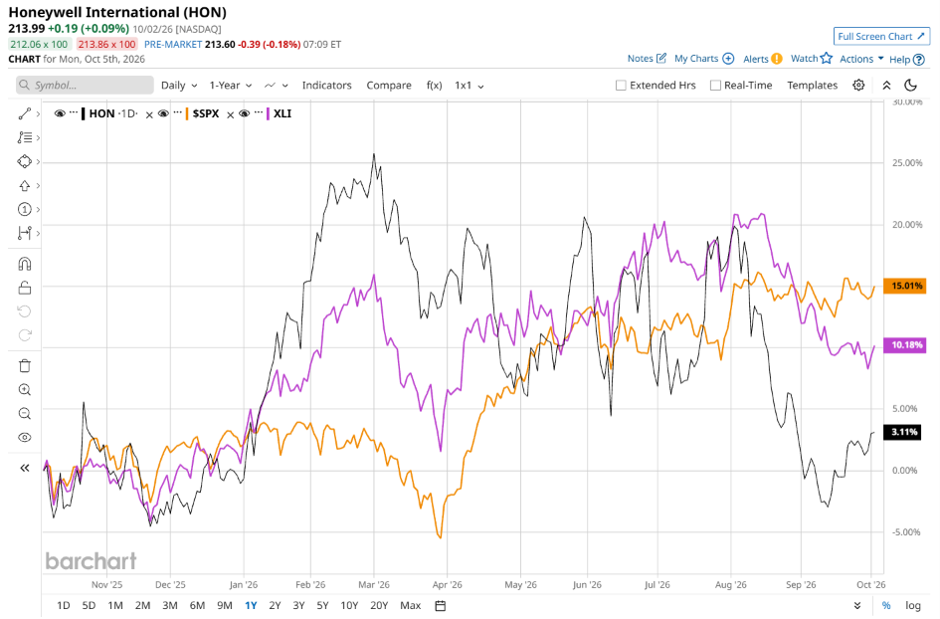
HON’s underperformance stems from broader industrial end-market soft spots, major portfolio restructuring dislocations, and operational execution bottlenecks. While the strategic spin-off of its high-margin Aerospace business Honeywell Aerospace Inc. (HONA) in mid-2026 was intended to unlock pure-play focus, it temporarily removed a primary earnings growth driver from the remaining automation entity. Concurrently, performance was dragged down by persistent weakness in its Process Automation and Technology segment, driven by lower refining catalyst shipments, regional project delays, and geopolitical headwinds in the Middle East, alongside rising operating costs and softer Q2 profitability that triggered downward earnings estimate revisions.
Analysts’ consensus opinion on HON stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 24 analysts covering the stock, 15 advise a “Strong Buy” rating, one suggests a “Moderate Buy,” and eight give a “Hold.” HON’s average analyst price target is $261.78, indicating a potential upside of 22.3% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.