
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Eurozone Utility Stocks With Dividends as Falling Yields Revive Income Appeal
Rate expectations are shifting again, with softer US jobs data, falling Treasury yields and fresh Middle East risks pulling extra attention to Eurozone utilities and infrastructure groups that pay dividends. Income investors do not just want yield; they want resilience when policy headlines move markets overnight. This article walks through three Eurozone dividend payers exposed to these news catalysts and explains where the current backdrop may support or challenge each stock.
The stocks discussed below are just a starter set, and the full screen surfaced 16 more Eurozone utilities and infrastructure dividend payers with equally compelling income and risk narratives that are not covered here.
If you want to identify your own highest conviction picks and pressure test them against rate moves and payout strength, head straight into the Eurozone Dividend-Paying Utility and Infrastructure Stocks screener.
Terna (BIT:TRN)
Overview: Terna runs Italy’s high voltage electricity transmission grid, earning regulated fees for moving power reliably across long distances.
Operations: Terna generates most of its income from about €3.3b of regulated activities, with roughly €0.9b coming from non regulated services.
Market Cap: €18.4b
For income investors who want Eurozone infrastructure exposure that behaves more like a regulated bond proxy, Terna is a textbook example, especially now that rate expectations and energy security are back in the spotlight.
"Ongoing and accelerating investments in grid modernization, digitalization, and resilience, including AI adoption and smart technologies, support higher efficiency in operations.
What really matters from here is how one quiet regulatory decision reshapes the balance between that growing asset base and future returns.
That regulatory call is the real hinge for Terna, so read the full narrative for Terna to see how those rulings could accelerate or cap the next chapter.

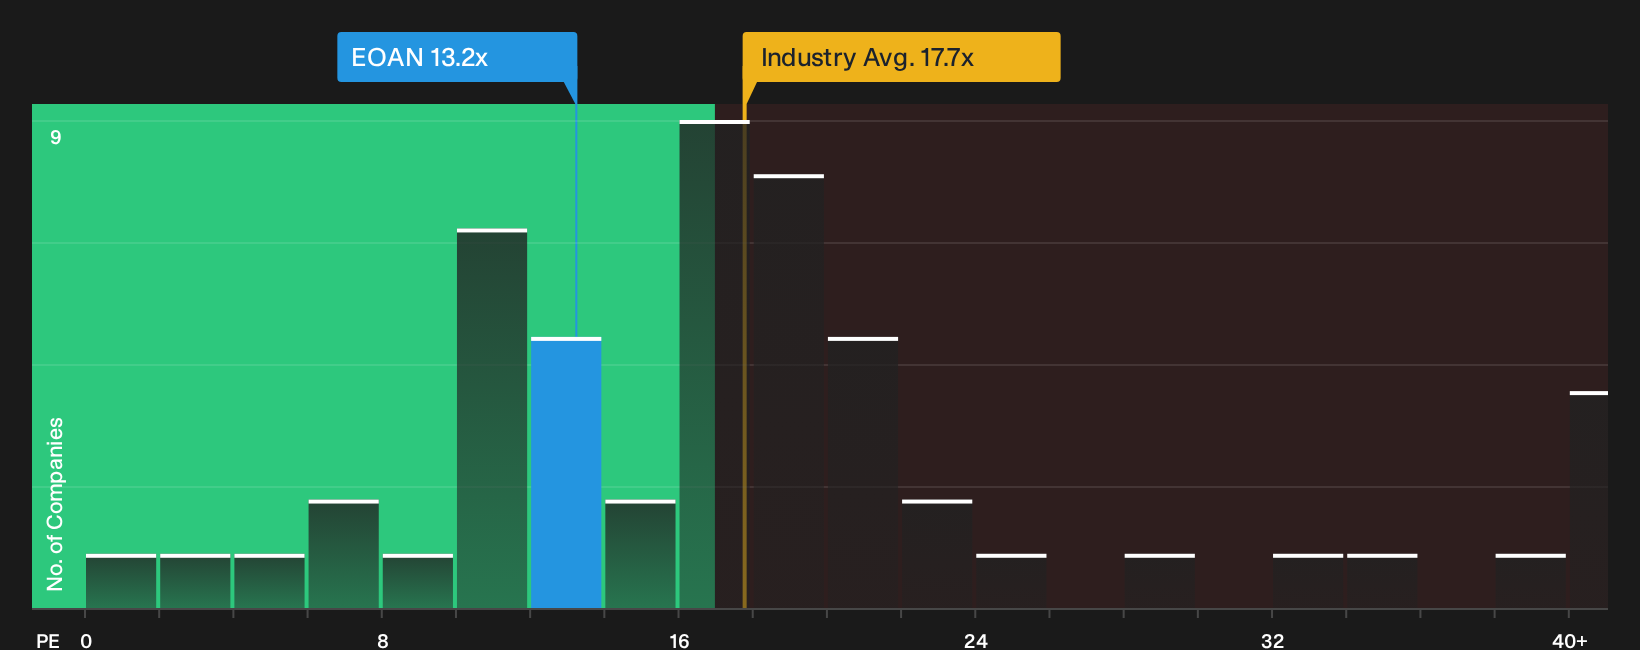
E.ON (XTRA:EOAN)
Overview: E.ON is a Eurozone utility group focused on regulated electricity and gas networks and customer energy solutions across Europe.
Operations: E.ON’s revenue base leans heavily on Energy Networks and Energy Retail, with €22.9b from German networks and €20.6b from German retail leading the mix.
Market Cap: €44.5b
For an income screen built around regulated infrastructure and dividend support, E.ON brings size, Eurozone grid exposure and rate sensitivity that link directly to the theme.
"Multiple forward-looking regulatory uncertainties, particularly in Germany regarding ROE, cost of debt, and changes to benchmarking, introduce real risk to E.ON's projected returns; current overvaluation may imply the market expects optimal regulatory outcomes, while actual rulings could cap returns and compress margins, especially from 2029 onwards."
What happens if a single core assumption behind those long dated grid returns shifts could matter far more than today’s headline yield.
That pivot point is exactly where your thesis gets tested, so read the full narrative for E.ON to see how E.ON’s risk profile and upside case could be decoupling.
Enagás (BME:ENG)
Overview: Enagás runs Spain’s regulated gas transmission, storage and regasification network, supporting income-focused investors seeking Eurozone infrastructure tied to tariff-based returns.
Operations: Enagás generates most of its revenue from about €963 million of regulated gas activities, with much smaller contributions from new businesses and other areas.
Market Cap: €4.3b
Enagás matters for this Eurozone dividend utility screen because CNMC-regulated, rate-linked returns tie its cash flows directly to the interest rate backdrop that is currently moving in investors’ favor.
"Massive, persistent growth in European gas demand for security and system backup (as seen during Spain's April 2025 electricity outage) is underappreciated, positioning Enagás for above-consensus throughput volumes and higher regulated returns on core natural gas infrastructure, which directly benefits overall EBITDA and recurring earnings."
What ultimately happens to Enagás’s payout appeal could hinge on how one still unresolved regulator-and-funding pressure point reshapes future margin headroom.
That pressure point is exactly where the story could turn, so read the full narrative for Enagás to see whether Enagás’s income profile is quietly accelerating or stalling.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first, not loudest. Breakout trends get caught early, then momentum players pile in while latecomers chase. Check under the radar for now and act promptly.
- Spot income workhorses before yields get compressed by late buyers by scanning a curated set of high payout opportunities with the 163 dividend fortresses.
- Target resilient operators while volatility is still dropping and risk scores remain tight by zeroing in on a hand picked universe through the 226 resilient stocks with low risk scores.
- Ride infrastructure momentum tied to rising AI demand before the grid upgrade story is fully priced by focusing on selected enablers inside the 40 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com