
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Hub Group (HUBG) Board Overhaul
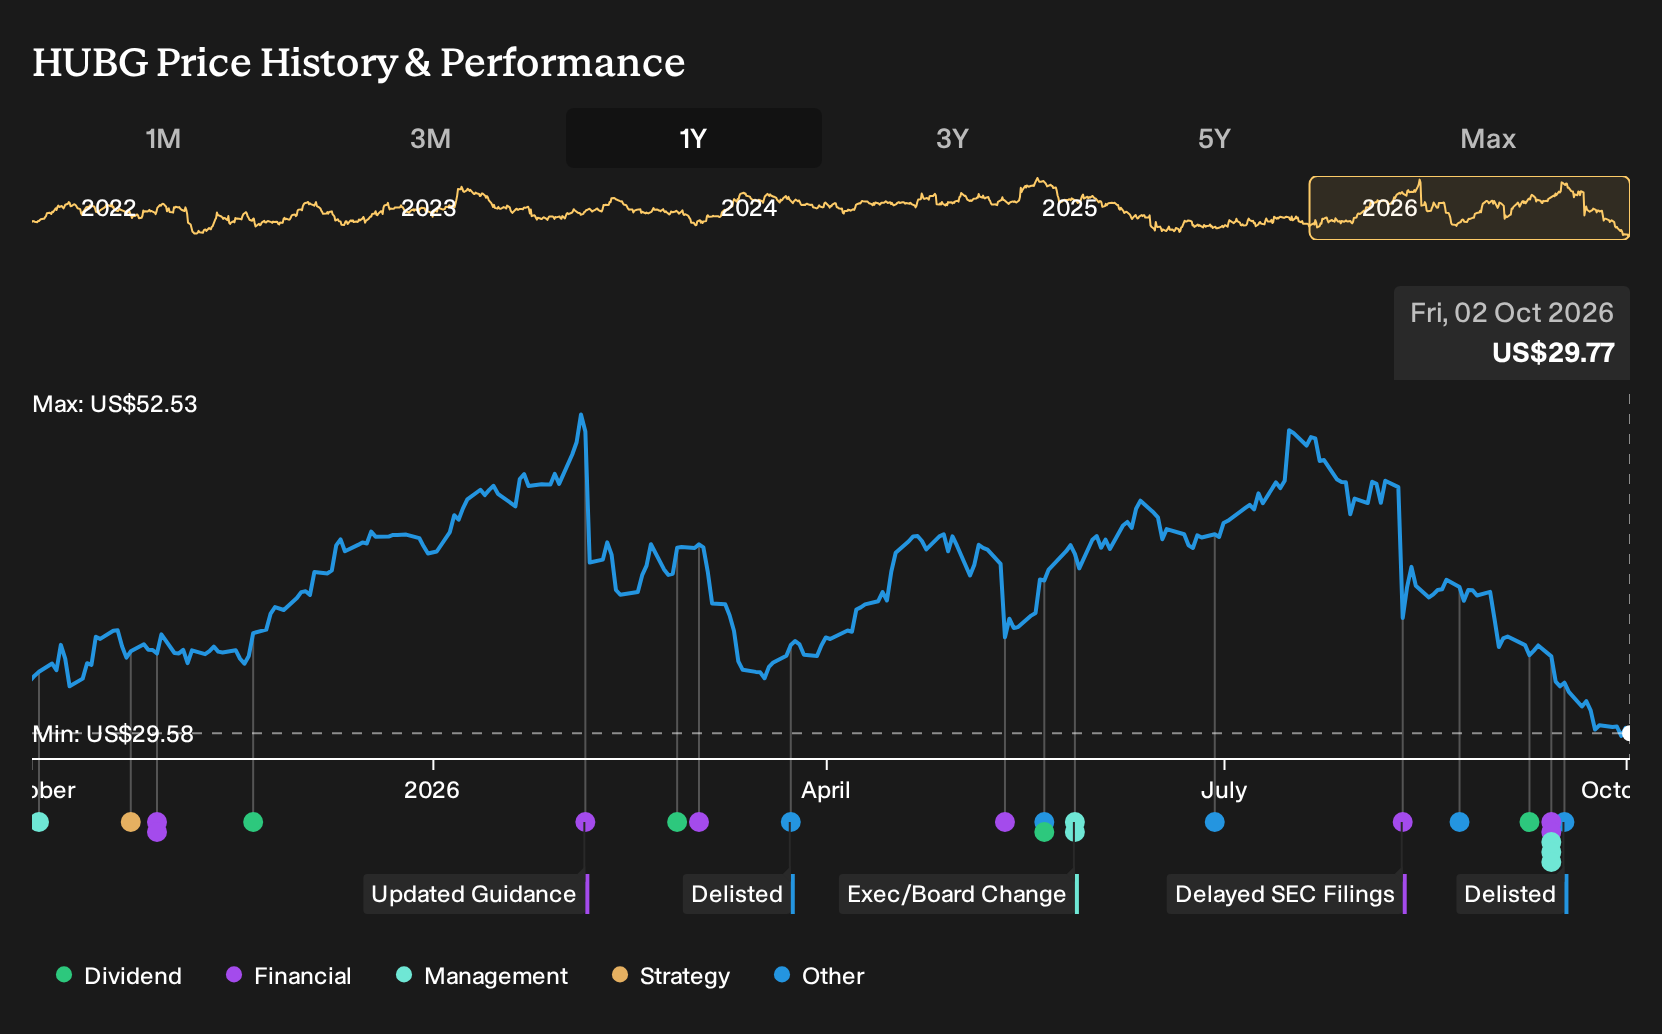
- Hub Group overhauled its board in early October 2026, removing three directors, appointing four new ones, and adopting second amended and restated bylaws.
- The refreshed board brings experience in logistics, corporate governance, law, and capital allocation. These areas of expertise may influence how Hub Group manages costs, growth investments, and risk.
- We will now look at how Hub Group's refreshed board and new bylaws might reshape the company’s longer term investment narrative.
Scan how Hub Group's boardroom shake-up compares with other logistics and industrial players repositioning their governance by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) aligned with disciplined oversight and capital discipline.
Hub Group Investment Narrative Recap
For Hub Group, the core belief is that demand for integrated, tech enabled freight and logistics solutions supports a steady pipeline of intermodal and contract logistics work. You also need to be comfortable with a muted freight backdrop, where the near term swing factor is how quickly new Final Mile and long term logistics contracts ramp against recent revenue pressure.
The latest board overhaul and new bylaws look more governance focused than operational, so the immediate freight and pricing outlook is largely unchanged. The bigger near term risk stays the same: prolonged softness in intermodal and brokerage or delayed customer wins could keep revenue and earnings volatility elevated.
The most relevant update is the appointment of four new directors, including former Hub Group CFO Thomas White and experienced corporate advisors Gregory Bunch and Thaddeus Malik. Their backgrounds in capital allocation, M&A and governance give the board deeper tools to oversee technology spend, fleet decisions and any future acquisition pipeline.
For you, the key question is execution. Can this refreshed board support management in balancing higher capital needs for digital platforms, equipment and sustainability against pressure on free cash flow and margins? If oversight tightens around returns on new projects and contract risk, it could directly influence how Hub Group handles its cost base and long term logistics wins.
Hub Group Earnings And Valuation Anchors
Hub Group's narrative projects US$4.2b revenue and US$141.3 million earnings by 2029. This aligns with analysts assuming 4.4% yearly revenue growth and implies an earnings increase of about US$36.3 million from current earnings of US$105.0 million.
Uncover how Hub Group's fair value indicates a 30% potential upside to its current price that could narrow quickly if sentiment toward Hub Group improves.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Hub Group’s cost and productivity gains as the real swing factor. Before this board shake up, the bullish camp was already modeling about 6.2% yearly revenue growth and US$171.3 million in earnings by 2029. You can now ask whether this governance reset shifts those expectations further, in either direction.
Explore 2 other Hub Group fair value estimates, including one that suggests as much as 306384% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hub Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Hub Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hub Group's overall financial health at a glance.
Looking For More Ideas Beyond Hub Group?
If the Hub Group story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you quickly narrow the field to businesses that better fit your risk, income, or value preferences.
- For investors hunting for potentially mispriced opportunities with resilient financial foundations, scan the 31 high quality undervalued stocks that currently line up well against quality and balance sheet strength.
- If capital preservation and steadier profiles matter most to you, focus on companies in the 31 resilient stocks with low risk scores that score well on financial health and risk metrics.
- When you want to broaden beyond Hub Group into other fundamentally sound operators, start with the 19 high quality undiscovered gems that combine solid numbers with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com