
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Duke Energy (DUK) Could Be 17% Undervalued Following Its Dividend Declaration
Dividend declarations put Duke Energy in focus
Duke Energy (DUK) has affirmed a quarterly cash dividend of $1.085 per common share, along with a scheduled payment on its Series A preferred stock. This provides income focused investors with updated information to consider.
The dividend decision comes as Duke Energy trades at US$114.13, with the share price slipping 5.1% over the past month and 11.0% over ninety days. At the same time, the 3 year total shareholder return of 44.8% and 5 year total shareholder return of 38.8% point to a stronger longer term record despite the recent loss of momentum, set against modest revenue and net income growth and a fresh board appointment that brings additional technology and audit experience into the boardroom.
Compare Duke Energy's income profile and recent share pullback with a hand picked set of resilient utilities in the 31 resilient stocks with low risk scores that prioritise stability and balance sheet strength.
Duke Energy offers a long income record and steady business mix, yet the share price has slipped in recent months. Is this still a strong utility simply marked down, or already fairly valued on today’s numbers?
Most Popular Narrative: 16.7% Undervalued
Duke Energy’s widely followed narrative pegs fair value at about $136.94, above the recent $114.13 close, which frames the current dividend yield and pullback in a different light.
Major economic development wins in Duke Energy territories, including large data center projects, are now supported by about 7.6 to 7.8 GW of executed electric service agreements and a 15.4 GW late stage pipeline that is expected to be fully contracted by the first half of 2027, which could translate into multi year load growth and higher regulated revenue as this contracted demand is served.
See why 86 investors see Duke Energy as 17% undervalued.
Result: Fair Value of $136.94 (UNDERVALUED)
Still, the Duke Energy story depends on smooth execution of a very large capital plan, as well as on regulators continuing to allow timely, constructive cost recovery.
Find out about the key risks to this Duke Energy narrative.
Another View: Duke Energy Through A Cash Flow Lens
While the prevailing Duke Energy narrative leans on a fair value of $136.94 and an undervalued label, the Simply Wall St DCF model lands in a very different place. On future cash flows, the estimate is $100.98, which implies the current $114.13 price sits above that mark. Which yardstick do you trust more for a regulated utility with heavy capital needs?
For a closer look at how the cash flow assumptions stack up against the earnings based story, Look into how the SWS DCF model arrives at its fair value.
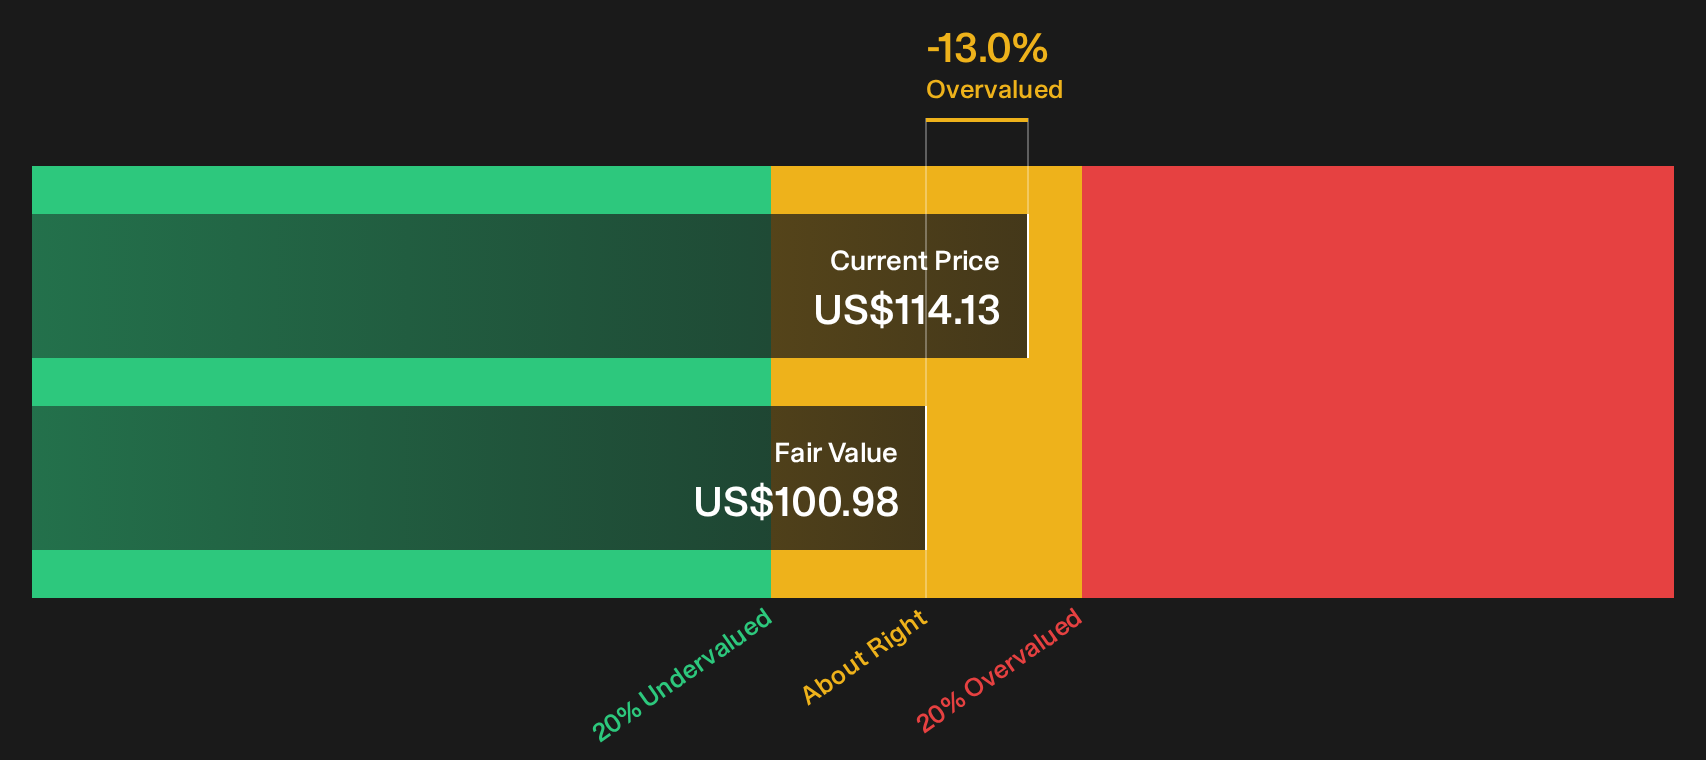
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duke Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Duke Energy can make the story feel unclear, so move fast and pressure test the thesis yourself by weighing both upside and downside using 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Duke Energy?
If Duke Energy is on your radar, do not stop there. Broaden your opportunity set with focused screeners that surface different styles of listed businesses.
- Target stronger value potential by reviewing companies filtered for quality and price using the 31 high quality undervalued stocks.
- Aim for reliable income streams by scanning for payouts with the 7 dividend fortresses.
- Zero in on financial resilience by checking companies in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com