
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Quest Diagnostics’ Quarterly Earnings Preview: What You Need to Know
Comcast Corporation (CMCSA), headquartered in Philadelphia, Pennsylvania, is a global media and technology company providing broadband, wireless, television, streaming and entertainment services. The company operates through two main segments, Connectivity & Platforms and Content & Experiences. With a market capitalization of approximately $79.5 billion, Comcast also produces entertainment, sports and news content and operates theme parks worldwide.
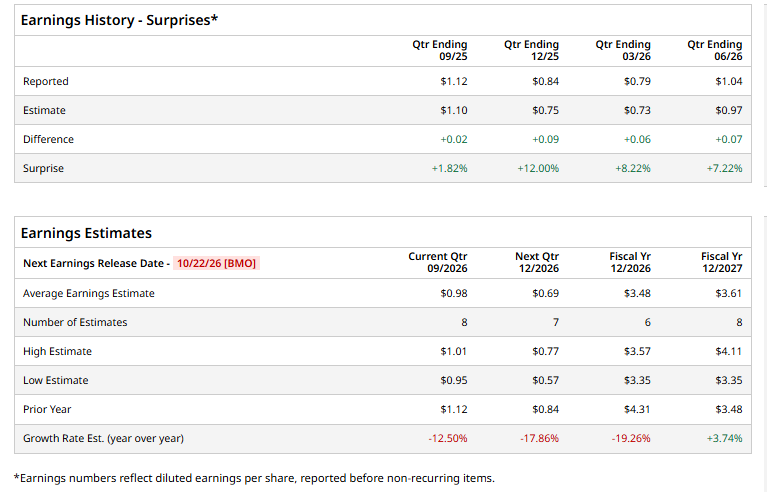
CMCSA is set to report its Q3 earnings on Thursday, October 22, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of 98 cents, down 12.5% from $1.12 in the year-ago quarter. That said, CMCSA has exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
For fiscal 2026, analysts expect the company to report EPS of $3.48, down 19.3% from $4.31 in fiscal 2025. However, EPS is projected to increase 3.7% year over year to $3.61 in fiscal 2027.
CMCSA stock has plunged 29.1% over the past 52 weeks, substantially underperforming both the S&P 500 Index ($SPX), which advanced 15%, and the State Street Communication Services Select Sector SPDR ETF (XLC), which declined 5.3% over the same period.
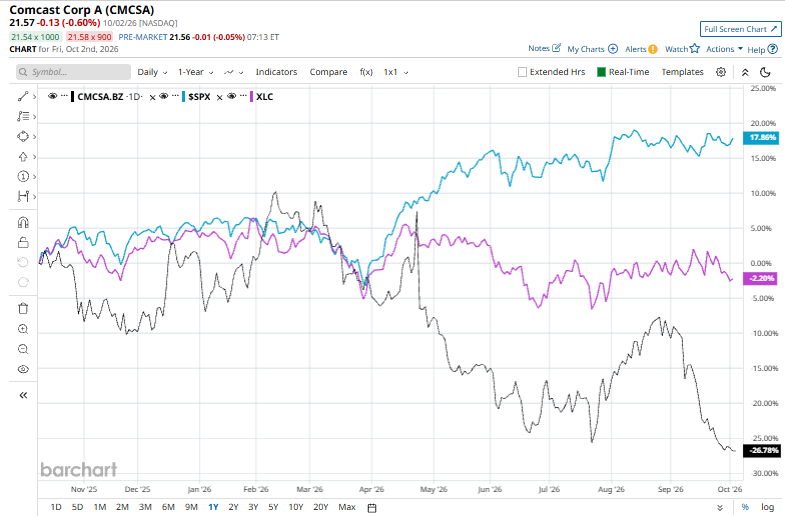
Comcast’s underperformance over the past year has been driven by weak broadband customer growth, rising capital intensity and declining returns on capital. Domestic broadband demand has remained underwhelming, while the company’s free cash flow margin is expected to decline by 4.4 percentage points over the next year, pointing to higher capital requirements and reduced financial flexibility. Meanwhile, weakening returns on capital have raised concerns about the effectiveness of its investment decisions and weighed on investor sentiment.
Analysts remain neutral on CMCSA, with the stock carrying a consensus “Hold” rating. Among the 31 analysts covering the stock, 10 recommend a “Strong Buy,” 17 rate it a “Hold,” and four suggest a “Strong Sell.” Meanwhile, the average price target of $29.14 implies potential upside of 35.1% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.