
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Dividend Increase At Bank OZK (OZK) Has Changed Its Investment Story
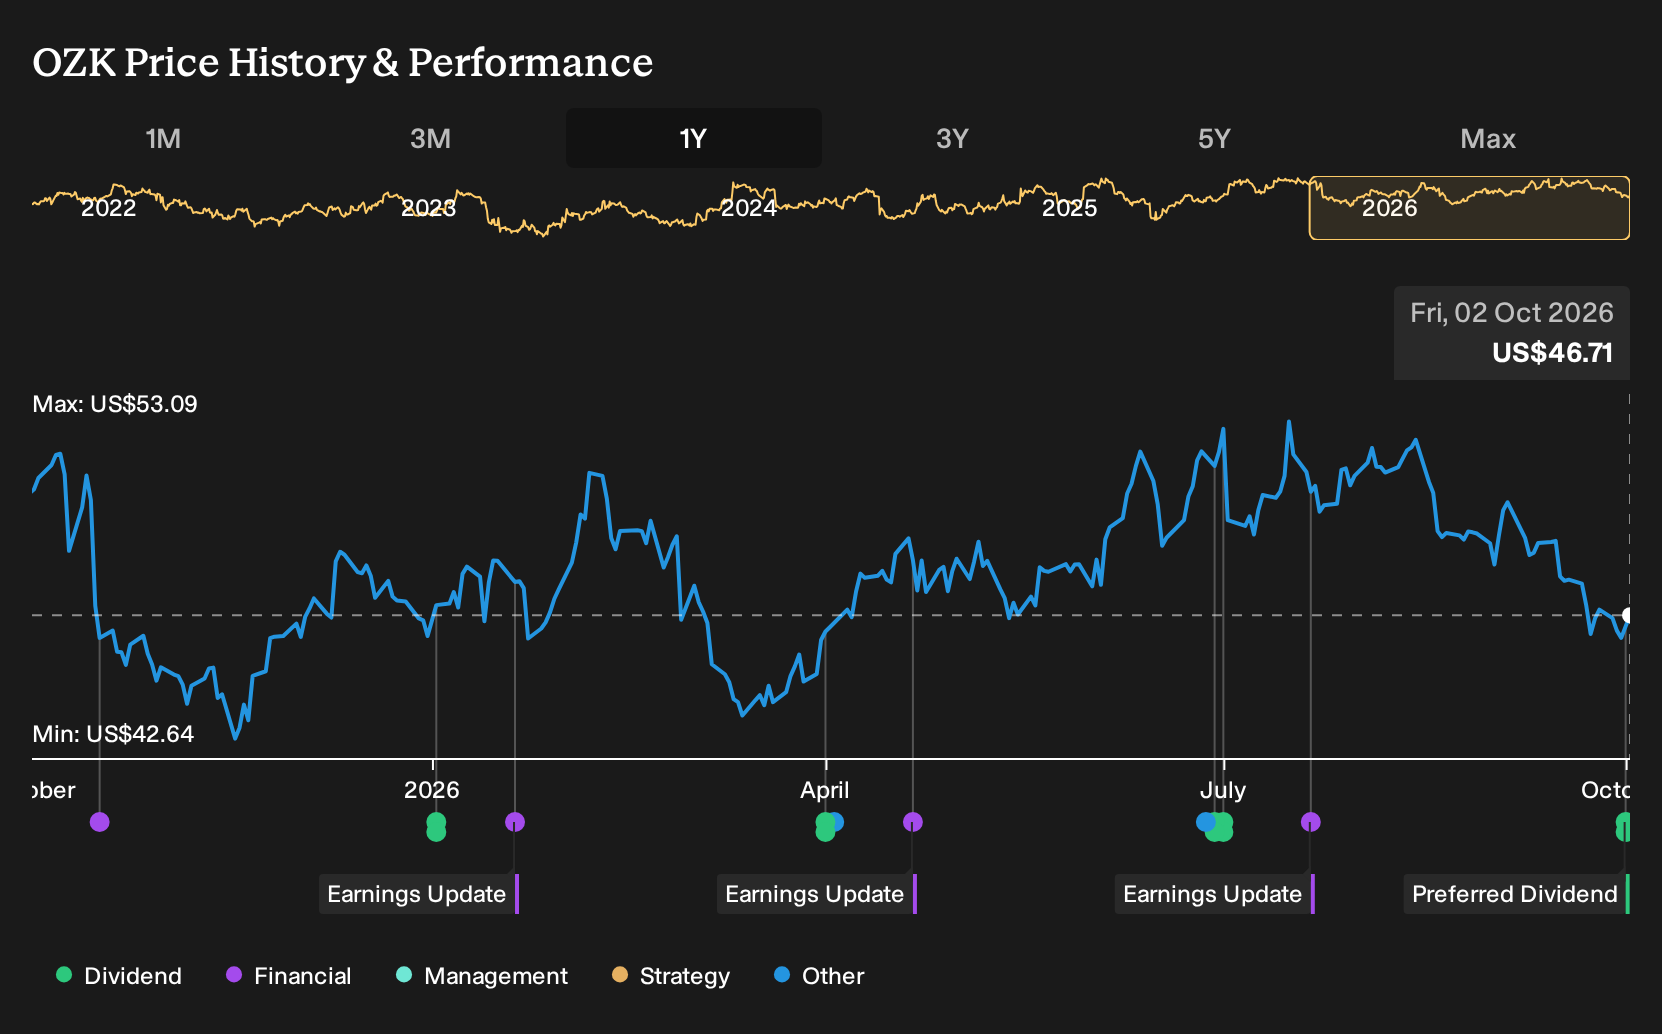
- Bank OZK’s board recently declared a quarterly dividend of $0.49 per common share and $0.28906 per Series A preferred share, with both payments scheduled for October and November 2026 to holders of record on the stated dates.
- The 2.08% increase in the common dividend, marking a 65th straight quarterly rise, highlights management’s focus on regular cash returns alongside ongoing lending and technology investment.
- This development prompts a closer look at how Bank OZK’s pattern of common dividend increases may influence the existing investment narrative around growth and risk.
Scan how Bank OZK’s latest dividend move compares to other income plays by reviewing our hand picked 7 dividend fortresses.
Bank OZK Investment Narrative Recap
To own Bank OZK, an investor needs to be comfortable with a loan book that leans heavily on commercial real estate while management pushes growth in Sun Belt markets and the Corporate & Institutional Banking segment. The key near term swing factor is how credit quality and repayments in its real estate specialties group affect earnings and capital flexibility.
The regular uptick in the common dividend, alongside the scheduled preferred payout, does not materially change that near term setup. It mainly signals that management currently sees its capital position as sufficient to keep funding branch expansion, technology spending, and loan growth while still returning cash to shareholders.
The latest 2.08% increase in Bank OZK’s common dividend and the declared Series A preferred dividend both point to a consistent income framework that some shareholders focus on. For investors tracking catalysts, the habit of small, repeated common dividend bumps can be a useful real time read on how the board views earnings resilience.
That rhythm of quarterly raises can matter if commercial real estate risk or elevated loan repayments start to pressure results. A stable or rising cash return can reinforce the idea that credit costs, Sun Belt expansion spending, and early stage CIB buildout are being managed within the existing earnings and capital envelope.
Bank OZK's current analyst story points to revenue of US$2.1b and earnings of US$658.3 million by 2029, built on an assumed 9.8% yearly revenue growth rate. That forecast implies earnings today of US$675.1 million would decline by about US$16.8 million by the 2029 estimate year.
Uncover why Bank OZK's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Lowest ranked analysts focus on credit risk. They see Bank OZK’s commercial real estate exposure and high RESG repayments as the real swing factor, even with this fresh dividend news. Before it, they were pencilling in about US$2.0b of 2029 revenue and US$682.6 million of earnings, a meaningfully more cautious story than consensus.
Explore 3 other Bank OZK fair value estimates, including one that suggests as much as 14% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank OZK research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Bank OZK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank OZK's overall financial health at a glance.
Looking For More Bank OZK Investment Ideas?
If Bank OZK has you thinking more broadly about income, quality and risk, it can help to compare it with a wider field of opportunities using the Simply Wall St screener.
- For income that aims to combine yield with resilience, review a curated 7 dividend fortresses that may complement or contrast with Bank OZK’s profile.
- If valuation discipline is your priority, scan a focused 31 high quality undervalued stocks built around stronger balance sheets and cash generation.
- For those looking beyond the usual tickers, cast a wider net across 19 high quality undiscovered gems that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com