
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Defensive Stocks With P E Under 31
Canadian investors are watching interest rate expectations cool in the US, as traders sharply cut the odds of an October Federal Reserve hike. Global bond markets have been volatile, and safer balance sheets suddenly feel more valuable. That is where strong, low risk Canadian stocks come in. This article walks through three of the most resilient picks from our quality focused screener and explains why they may deserve a place in your portfolio.
The three stocks covered below are just a starting sample from this low risk leaders idea, and the full screen surfaced 5 more companies with equally compelling narratives that are not covered in this article.
If you want to identify the most resilient balance sheets and analyze potential high conviction anchors for your portfolio, head straight into the Low Risk Leaders screener.
Aritzia (TSX:ATZ)
Overview: Aritzia is a Vancouver based fashion retailer that designs and sells its own womenswear brands through boutiques and online, supporting the stable cash flows that anchor its low risk balance sheet.
Operations: Aritzia generates about CA$4.0b from apparel, with roughly CA$1.5b from Canada and CA$2.5b from the United States.
Market Cap: CA$14.1b
Aritzia fits the Low Risk Leaders idea because its owned brands, boutique network, and online channel together create recurring, relatively predictable cash flows that support the strong balance sheet this screener looks for. At the same time, the company gives investors exposure to a growing North American fashion business.
"Aritzia's geographic expansion strategy, particularly in the United States, has shown strong performance and presents significant growth potential through ongoing boutique openings."
What ultimately matters for investors is how one quiet pressure on future profitability shapes the balance between dependable growth and valuation risk.
That pressure is already shaping expectations, so read the full narrative for Aritzia to see how Aritzia’s balance sheet and valuation story could be decoupling from headline sentiment.

China Gold International Resources (TSX:CGG)
Overview: China Gold International Resources runs large scale gold and copper mining operations in China that underpin recurring cash flow and support the Low Risk Leaders theme.
Operations: The business generates about US$399 million from produced gold and US$1.2b from produced copper concentrate, primarily from the CSH and Jiama mines.
Market Cap: CA$15.6b
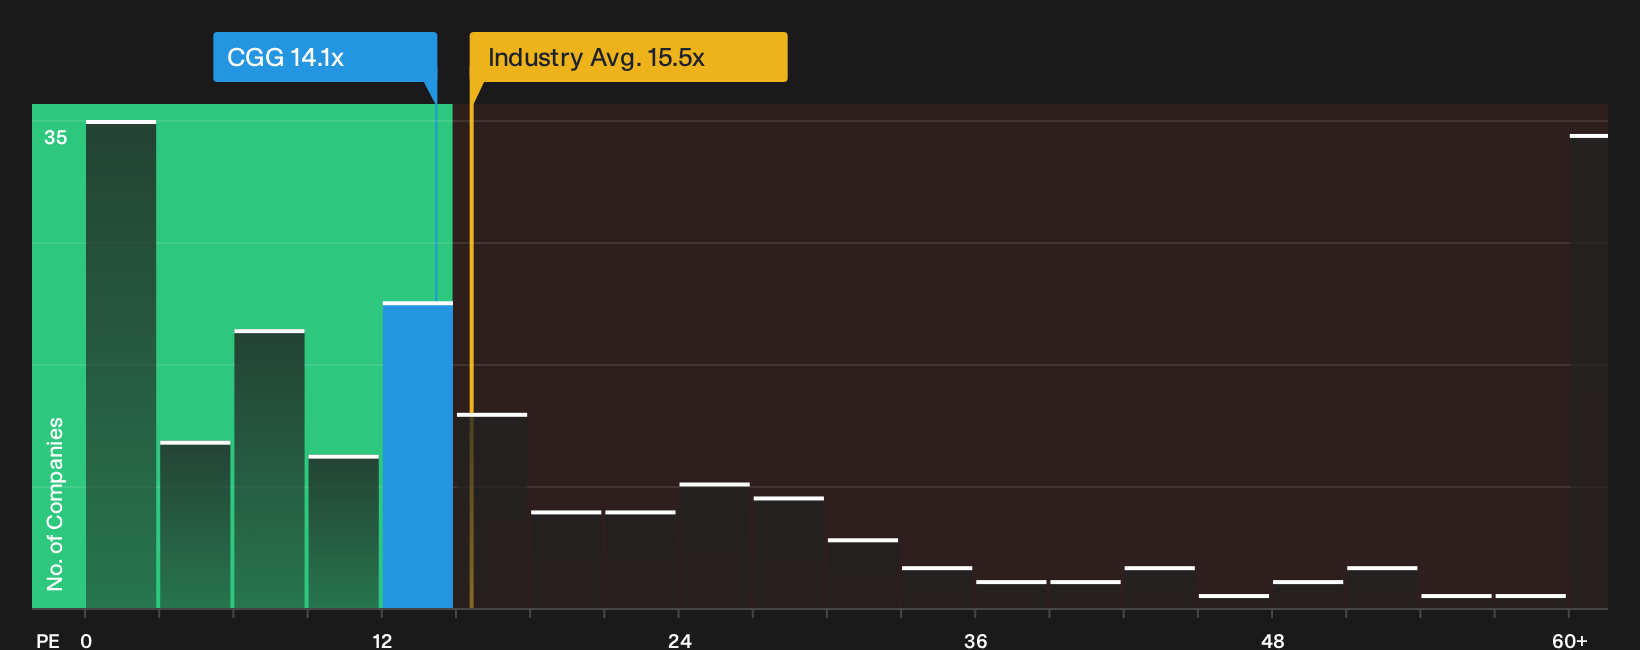
China Gold International Resources offers investors exposure to producing gold and copper assets that support balance sheet strength, with a P/E of 14.1x below industry and peers and current net profit margins of 47.1%. However, future returns hinge on how one unresolved funding pressure interacts with the earnings power of those two core mines.
That funding question is where China Gold International Resources gets interesting, so tap into the analysis report for China Gold International Resources for more detail on how current margins and valuation could be decoupling.
Torex Gold Resources (TSX:TXG)
Overview: Torex Gold Resources is a Toronto based intermediate miner whose fully owned Morelos Complex in Mexico anchors low risk gold focused cash generation.
Operations: Torex Gold Resources produces about US$1.8b of revenue from the Morelos Complex in Mexico, reflecting a highly concentrated single asset focus.
Market Cap: CA$6.5b
Torex Gold Resources fits the Low Risk Leaders idea because the fully owned, producing Morelos Complex gives you a clear, asset backed foundation for earnings that is being steadily reinforced by ongoing drilling and mine life work.
"Successful completion and ramp-up of the Media Luna project, along with ongoing infrastructure advancements (for example, paste backfill plant and ore passes), are set to materially increase production volumes and extend mine life, supporting long-term revenue growth and cash flow stability."
What ultimately matters now is how one unseen cost and execution pressure shapes the trade off between that foundation and future margins.
Those execution and cost questions sit at the center of the full narrative for Torex Gold Resources, which explains how Torex Gold Resources could turn today’s pressure into accelerating, underappreciated upside.

Seeking Alternatives Before Others Move First
Fresh ideas move first, and the strongest stories often gain momentum while many investors are still focused on old favorites. Review these curated picks early and consider where they might fit into your research process.
- Identify emerging cash generators by running the curated 6 high quality undervalued stocks and see which balance sheet focused businesses still trade as if the market has not noticed.
- Monitor where digital finance momentum is quietly building with the hand picked 17 cryptocurrency and blockchain stocks so you can evaluate these blockchain exposed companies while they are still under the radar.
- Build a watchlist of potential income-oriented holdings using the curated 1 dividend fortresses and assess which higher yielding payers may warrant deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com