
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Monte Rosa Therapeutics (GLUE) Following Phase 1 Data Faces A Big Fair Value Question
Monte Rosa Therapeutics (GLUE) is back on investors’ radar after the company released detailed Phase 1 GFORCE-1 data for MRT-8102, a NEK7-directed degrader studied in obese subjects with elevated cardiovascular risk.
Despite the Phase 1 GFORCE-1 update putting Monte Rosa Therapeutics back in focus, the recent trading pattern has been weak, with the share price down 24.13% over the past month and 56.97% over 90 days. However, the 1-year total shareholder return of 37.08% and 3-year total shareholder return of 127.77% show a much stronger longer-term picture, suggesting short-term momentum has faded even as longer-horizon investors who captured earlier moves have seen sizeable gains.
Capitalize on Monte Rosa Therapeutics putting molecular glue degraders in the spotlight by scanning a curated 19 high quality undiscovered gems that targets similar early-stage science with potential to reshape future treatment options.Monte Rosa Therapeutics now has eye-catching science and a share price that has pulled back sharply in a short span. Is the current quote rewarding the platform or the recent drawdown?
Most Popular Narrative: 62% Undervalued
Monte Rosa Therapeutics closed at $10.50 while the most followed narrative anchors fair value at $28, putting a big gap between recent price weakness and that long run view.
Expansion of MRT-8102 into three Phase 2 programs in coronary artery disease, recurrent gout flares and hidradenitis suppurativa, with defined start windows and endpoints, gives Monte Rosa Therapeutics several upcoming data and partnering opportunities that could influence future revenue and earnings trajectories. Use of biomarker, genetics and coronary imaging based patient enrichment in the planned GFORCE-2 CAD study aims to refine a future MACE outcomes trial, which could support clearer clinical positioning and pricing power for MRT-8102 and in turn affect longer term revenue potential.
See why 1 investors see Monte Rosa Therapeutics as 62% undervalued.
Result: Fair Value of $28 (UNDERVALUED)
Still, the Monte Rosa Therapeutics story can shift quickly if MRT-8102 timelines slip or if collaboration revenue keeps trailing expectations and forcing heavier reliance on the cash pile.
Find out about the key risks to this Monte Rosa Therapeutics narrative.
Another View on Monte Rosa Therapeutics Valuation
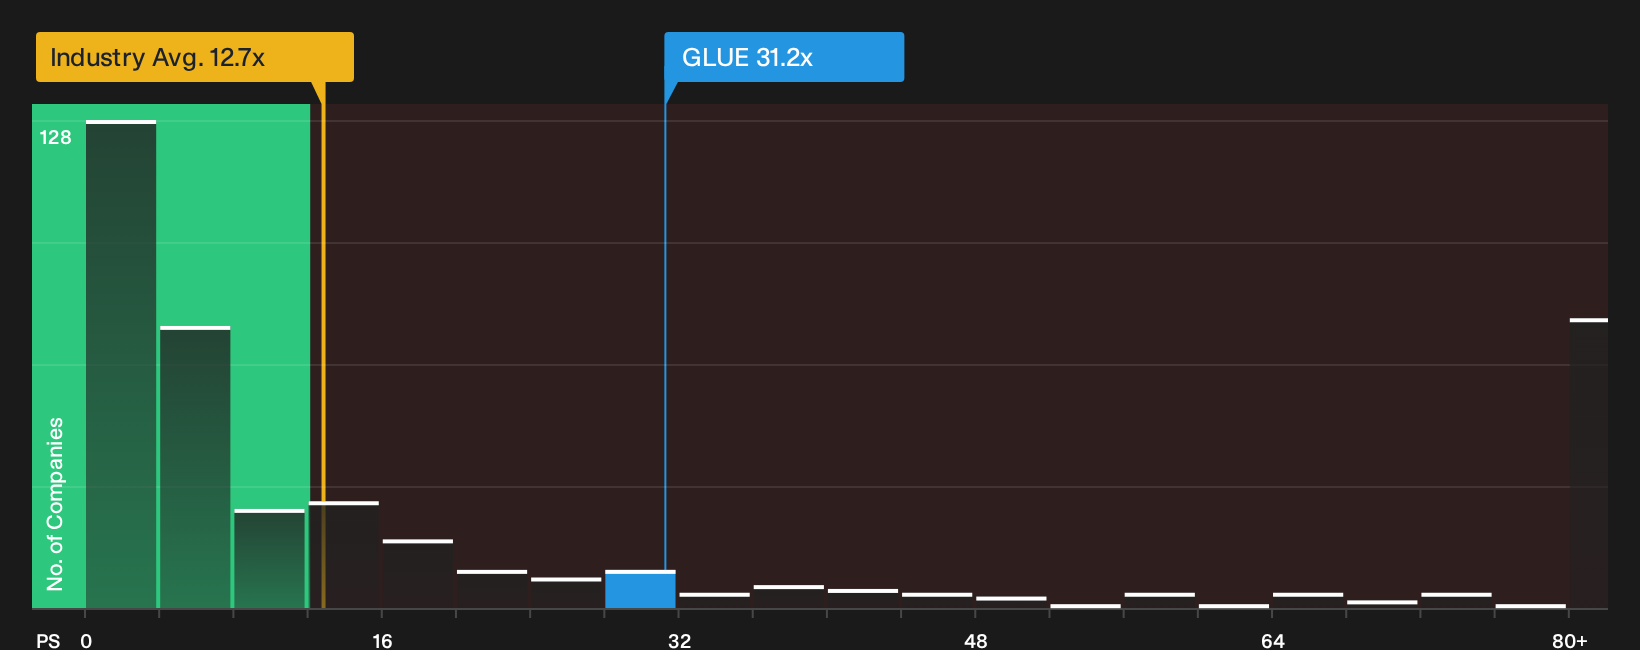
That $28 fair value anchor leans on long term earnings forecasts and high future P/E assumptions. A simpler yardstick, the current P/S ratio of 31.2x, paints Monte Rosa Therapeutics as expensive versus the US Biotechs industry at 12.7x and an estimated fair ratio of 0x. How comfortable are you paying a rich multiple for a business that is still loss making?
To see what the numbers say about this price, investors can review a detailed breakdown that compares current P/S to peers and the fair ratio in more depth See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Monte Rosa Therapeutics valuation and risk profile make this a judgment call. Move quickly on your research and weigh both sides using 2 key rewards and 5 important warning signs
Looking for more Monte Rosa Therapeutics style investment ideas?
If Monte Rosa Therapeutics has sharpened your focus on where risk and reward might meet next, use the Simply Wall Street Screener to uncover focused opportunities before they slip away.
- Target potential mispricings by scanning a curated set of companies that combine quality metrics with attractive valuations through the 31 high quality undervalued stocks.
- Prioritise resilience by zeroing in on businesses with stronger finances and sturdier funding profiles using the list of solid balance sheet and fundamentals (25 results).
- Hunt for smaller opportunities that still pass tough financial filters by working through a refined 7 elite penny stocks with strong financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com