
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Almonty Industries (ALM), Why Is It Back In The Spotlight?
Almonty Industries (NasdaqCM:ALM) has had an active few days, with Zeifmans resigning as auditor, PwC stepping in as the new auditor, and a legal settlement correcting earlier public claims about the company’s leadership history.
Against that backdrop, Almonty Industries has been volatile in the short term, with the share price down about 24% over the past month and roughly 12% over the past quarter, even as the year-to-date share price return of 52% and a very large 3-year total shareholder return suggest earlier momentum has already been strong and may now be cooling as investors reassess growth prospects and risk after the auditor switch and the legal clarification around past leadership claims.
Compare how the recent auditor shake-up at Almonty Industries stacks up against peers by scanning hand-picked list of solid balance sheet and fundamentals (25 results) that have not faced similar oversight changes.
After a sharp year-to-date gain and a recent pullback tied to the auditor change and leadership clarification, Almonty Industries now sits at an awkward crossroads. Is it worth stepping in after this reset, or does patience make more sense as valuation comes into focus next?
Preferred P/E of 51.3x: Is it justified for Almonty Industries?
Almonty Industries closed at $13.40, trading on a P/E of 51.3x that sits well above both its estimated fair P/E of 47.9x and broader Metals and Mining peers, which points to investors paying a premium for each dollar of current earnings.
The P/E ratio captures how much the market is willing to pay today for the miner’s recent profit stream. For a business that has only just become profitable, a high P/E can indicate that investors are heavily focused on expected future earnings rather than the current income line.
Analysts expect Almonty Industries' earnings to grow 56.97% per year and revenue to rise 43.5% per year, with forecasts that both earnings and revenue will expand faster than the wider US market. A P/E of 51.3x, compared with an estimated fair P/E of 47.9x and a US Metals and Mining industry average of 19.9x, signals that the share price embeds much richer expectations than the sector and may have less room for error if those projections shift.
Explore the SWS fair ratio for Almonty Industries.
Result: Price-to-Earnings of 51.3x (OVERVALUED)
Still, Almonty Industries faces clear pressure points if earnings forecasts are revised lower, or if the recent auditor change undermines confidence in reported figures.
Find out about the key risks to this Almonty Industries narrative.
Another view on Almonty Industries: DCF vs market pricing
The high P/E paints Almonty Industries as expensive, yet our DCF model points in the opposite direction. At $13.40, the stock trades about 68.3% below an estimated future cash flow value of $42.26, which frames the current quote as discounted rather than stretched.
This clash between earnings multiple and cash flow value leaves a practical question: Is the market overpaying for near term earnings, or underappreciating longer term cash generation?
Look into how the SWS DCF model arrives at its fair value.
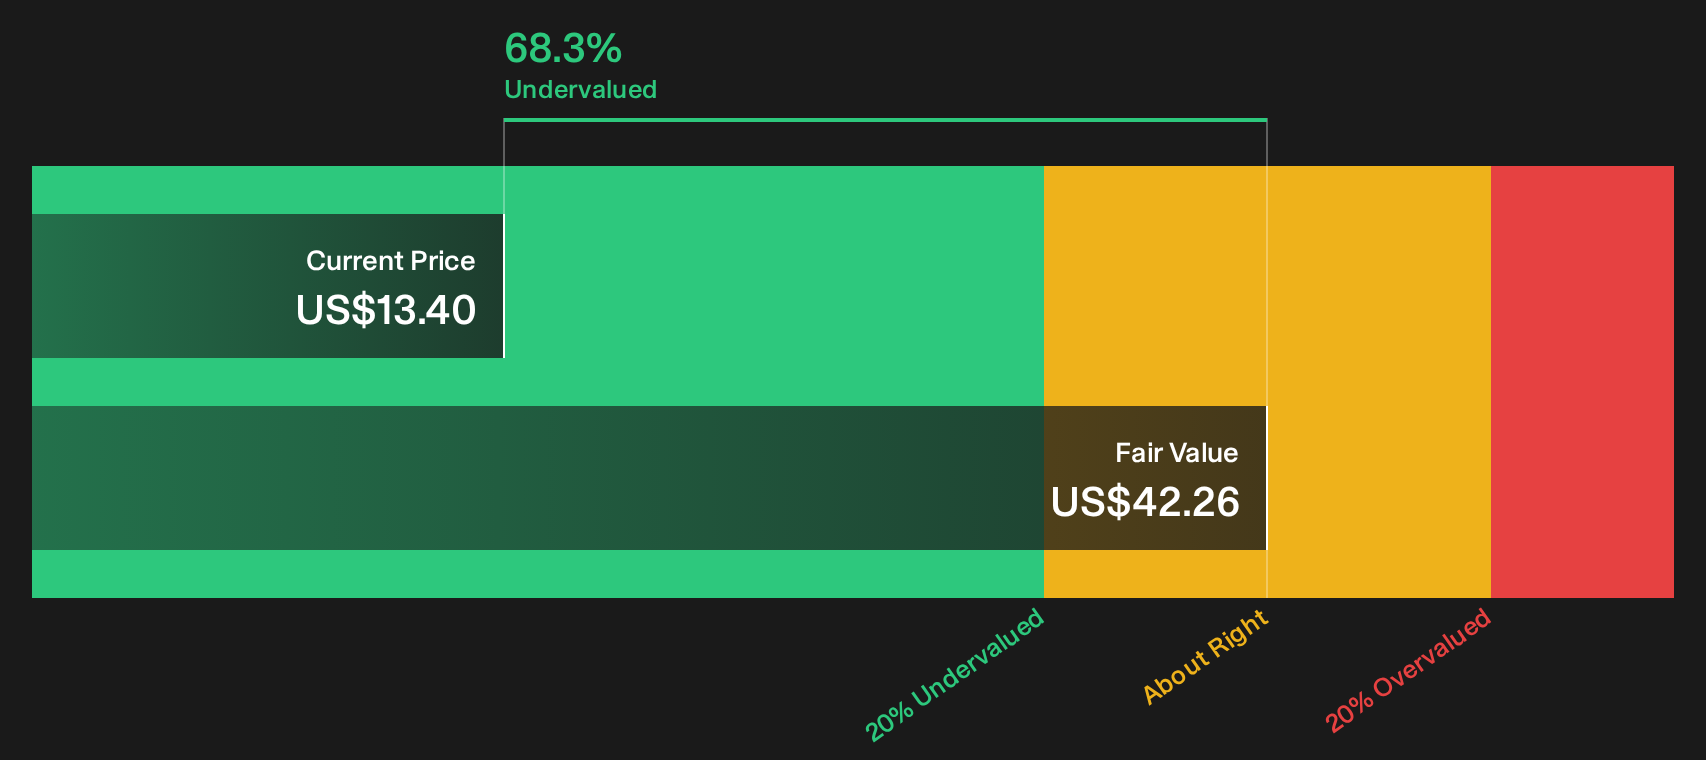
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Almonty Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Almonty Industries do not have to leave you stuck on the sidelines. The fastest way to cut through the noise is to check the underlying data and weigh the 3 key rewards and 4 important warning signs yourself with 3 key rewards and 4 important warning signs
Looking for more investment ideas beyond Almonty Industries?
If Almonty Industries has your attention, use that momentum. Line up a few fresh watchlist candidates now so you are not reacting late to the next move.
- Target resilience first and scan a 31 resilient stocks with low risk scores that filters for businesses with more measured risk profiles.
- Hunt for mispriced quality and review a 19 high quality undiscovered gems that highlights lesser known companies with strong fundamentals.
- Build staying power into your income plan and assess a 7 dividend fortresses focused on higher yielding dividend payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com