
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Global Stocks Estimated To Be Up To 38.1% Below Intrinsic Value
In recent weeks, global markets have experienced mixed performance, with U.S. job growth slowing and inflation remaining persistent, while European equities faced volatility due to elevated oil prices and rising bond yields. Amidst this uncertainty, investors are increasingly focusing on identifying undervalued stocks that may offer potential for growth as they navigate the complexities of today's economic landscape. A good stock in such conditions is one that appears to be trading below its intrinsic value, presenting an opportunity for long-term appreciation when market conditions stabilize or improve.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shanghai Flyco Electrical Appliance (SHSE:603868) | CN¥31.09 | CN¥61.62 | 49.5% |
| Nissui (TSE:1332) | ¥1107.00 | ¥2180.59 | 49.2% |
| Kingnet Network (SZSE:002517) | CN¥16.01 | CN¥31.56 | 49.3% |
| Innodisk (TPEX:5289) | NT$1295.00 | NT$2530.08 | 48.8% |
| Ichikoh Industries (TSE:7244) | ¥545.00 | ¥1066.53 | 48.9% |
| Hainan Jinpan Smart Technology (SHSE:688676) | CN¥61.53 | CN¥121.78 | 49.5% |
| Grupa Pracuj (WSE:GPP) | PLN56.00 | PLN110.50 | 49.3% |
| ENN Energy Holdings (SEHK:2688) | HK$48.62 | HK$96.82 | 49.8% |
| Double Medical Technology (SZSE:002901) | CN¥40.86 | CN¥79.59 | 48.7% |
| China Coal Energy (SEHK:1898) | HK$10.17 | HK$20.10 | 49.4% |
Let's explore several standout options from the results in the screener.
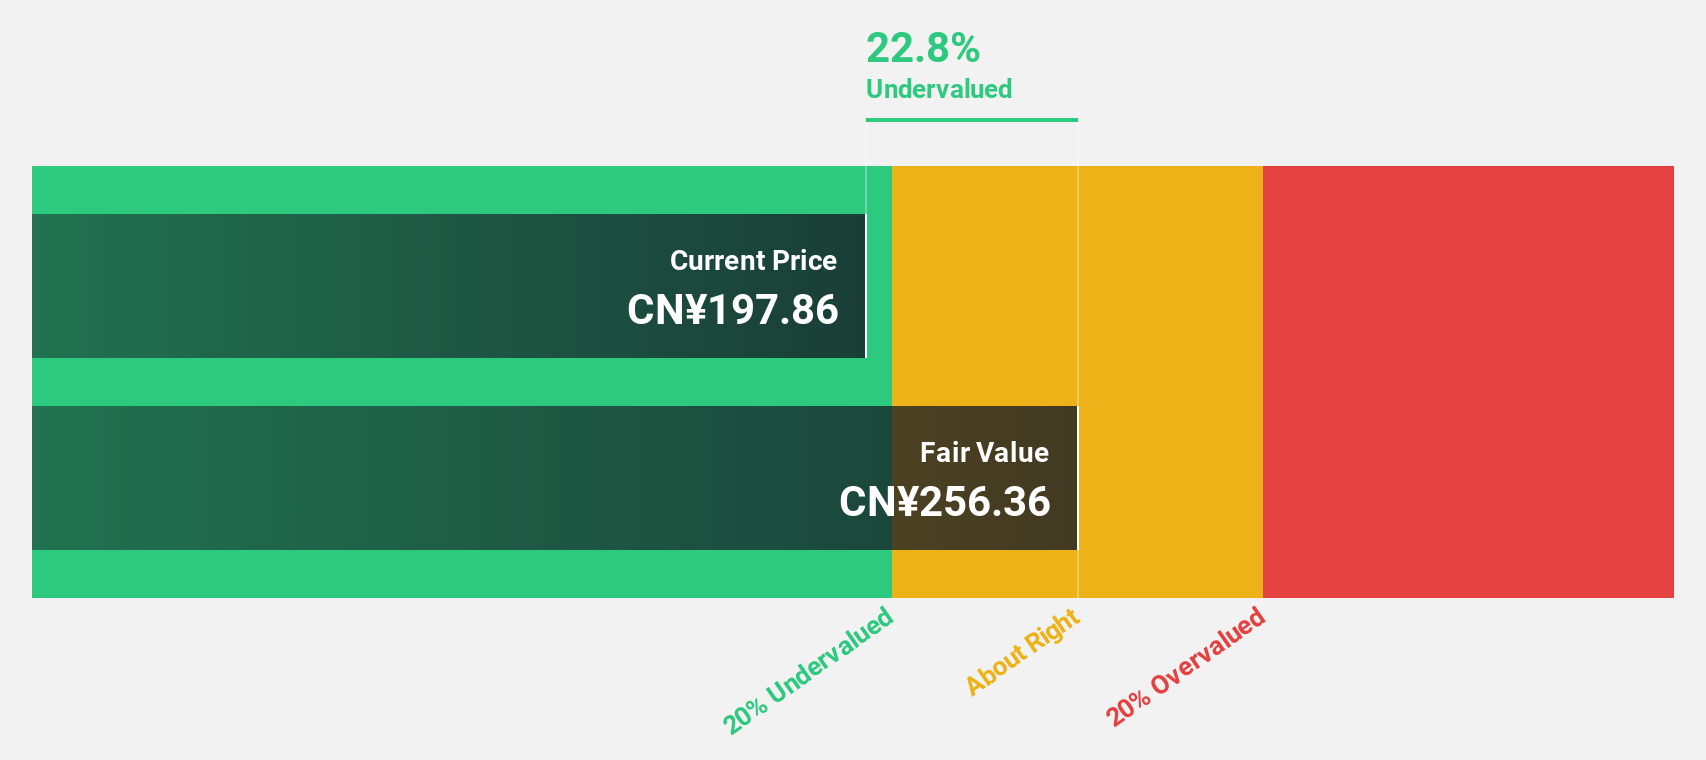
Shennan Circuits (SZSE:002916)
Overview: Shennan Circuits Co., Ltd. designs, manufactures, and sells printed circuit boards, packaging substrates, and electronic assemblies both in China and internationally, with a market cap of CN¥254.08 billion.
Operations: The company's revenue is primarily derived from printed circuit boards (CN¥16.64 billion), packaging substrates (CN¥6.07 billion), and electronic assemblies (CN¥3.57 billion).
Estimated Discount To Fair Value: 22.5%
Shennan Circuits is trading at CN¥373.01, below its estimated future cash flow value of CN¥481.31, indicating undervaluation based on discounted cash flow analysis. Earnings are expected to grow significantly at 28.3% annually, outpacing the market's growth rate. Despite a volatile share price and a dividend not well covered by free cash flows, recent earnings showed substantial improvement with net income rising to CN¥2.25 billion from CN¥1.36 billion year-over-year.
- Upon reviewing our latest growth report, Shennan Circuits' projected financial performance appears quite optimistic.
- Take a closer look at Shennan Circuits' balance sheet health here in our report.
Toyo Suisan Kaisha (TSE:2875)
Overview: Toyo Suisan Kaisha, Ltd., along with its subsidiaries, is involved in the production and sale of food products both in Japan and internationally, with a market capitalization of ¥918.91 billion.
Operations: The company's revenue segments include Domestic Instant Noodles at ¥106.05 billion, Overseas Instant Noodles at ¥256.83 billion, Low Temperature Food at ¥61.32 billion, Seafood at ¥33.76 million, Refrigeration at ¥27.70 million, and Processed Foods at ¥23.26 million.
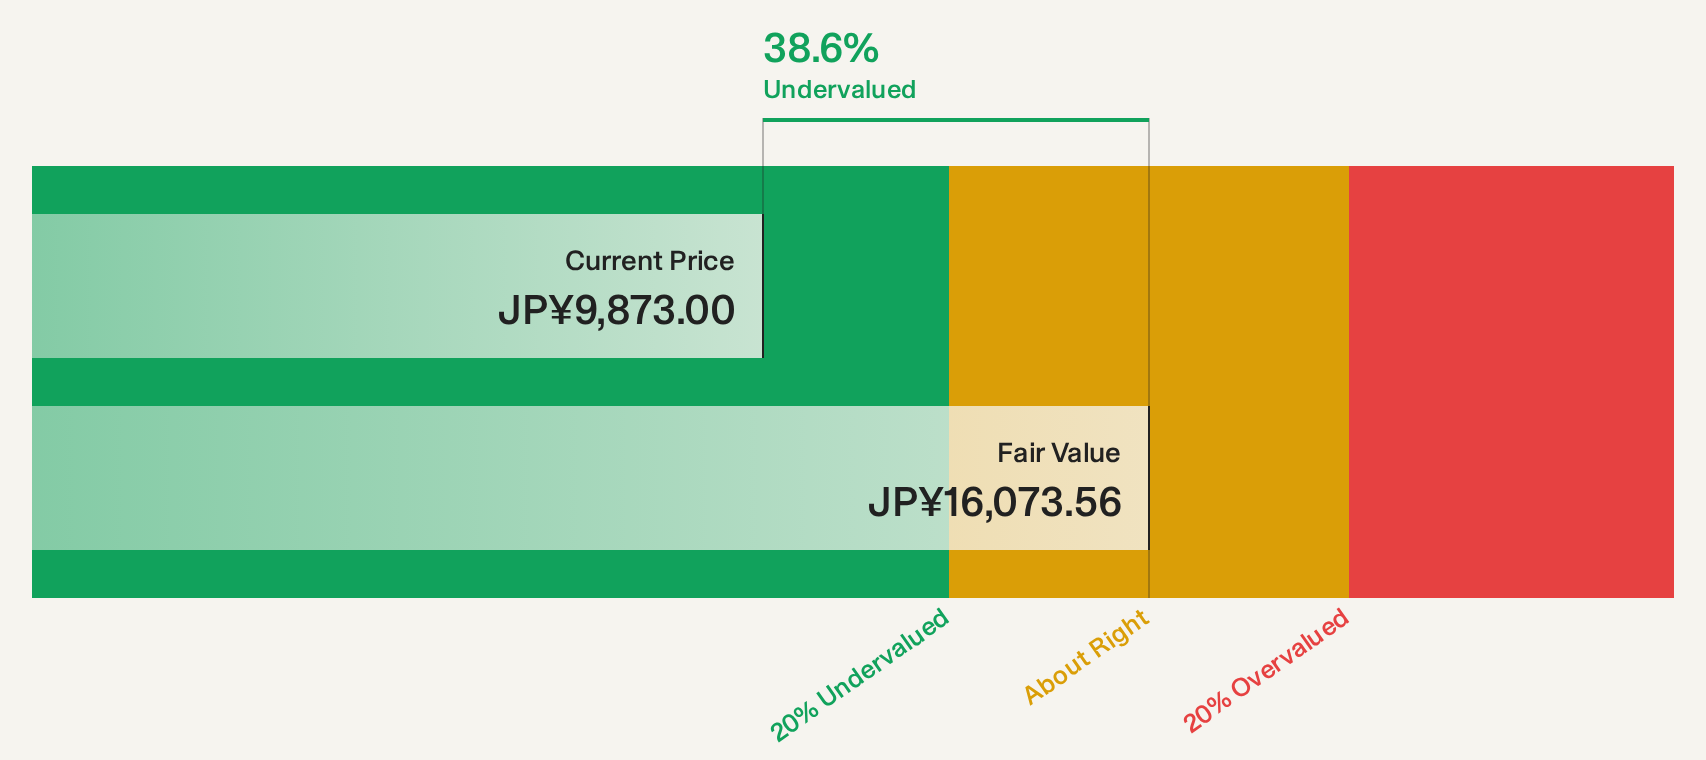
Estimated Discount To Fair Value: 38.1%
Toyo Suisan Kaisha is trading at ¥9,957, significantly below its estimated future cash flow value of ¥16,073.56, highlighting its undervaluation. The company recently completed a share buyback worth ¥27.50 billion and forecasts net sales of ¥560 billion for fiscal 2027. However, earnings growth is expected to be modest at 1.7% annually compared to the market's 9.5%. Despite this, it offers a reliable dividend yield of 2.21%.
- The growth report we've compiled suggests that Toyo Suisan Kaisha's future prospects could be on the up.
- Click to explore a detailed breakdown of our findings in Toyo Suisan Kaisha's balance sheet health report.
Mitsui Chemicals (TSE:4183)
Overview: Mitsui Chemicals, Inc. operates globally in the sectors of life & healthcare solutions, mobility solutions, ICT solutions, and basic & green materials with a market cap of ¥759.50 billion.
Operations: The company's revenue is primarily derived from its basic & green materials segment at ¥695.51 billion, followed by mobility solutions at ¥530.80 billion, ICT solutions at ¥295.70 billion, and life & healthcare solutions at ¥270.18 billion.
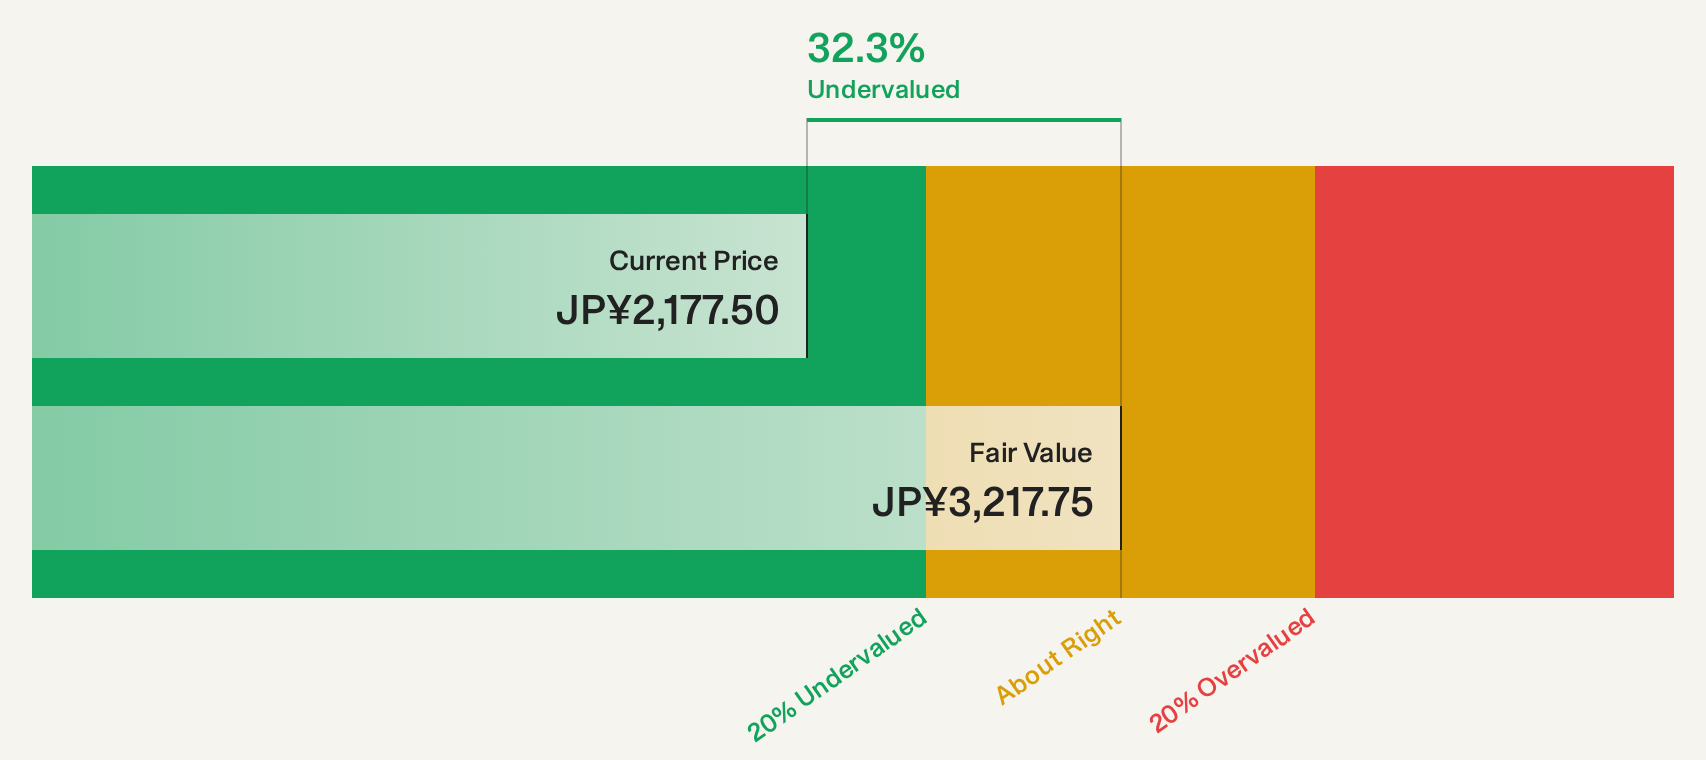
Estimated Discount To Fair Value: 31.9%
Mitsui Chemicals is trading at ¥2,164.5, significantly below its estimated future cash flow value of ¥3,177.88, indicating undervaluation. Despite high debt levels and a forecasted low return on equity (8.9%), earnings are expected to grow 11.63% annually, outpacing the Japanese market's 9.5%. Recent guidance anticipates ¥957 billion in sales revenue for the first half of fiscal 2027, with reliable dividends maintained at ¥37.50 per share annually.
- Insights from our recent growth report point to a promising forecast for Mitsui Chemicals' business outlook.
- Navigate through the intricacies of Mitsui Chemicals with our comprehensive financial health report here.
Summing It All Up
- Access the full spectrum of 234 Undervalued Global Stocks Based On Cash Flows by clicking on this link.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com