
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Modine Manufacturing (MOD) Shares Dropped And What Investors Are Weighing
Modine Manufacturing (MOD) has been in the news after President of Performance Technologies Jeremy M. Patten left the company following the completion of certain transactions and his transition to Gentherm.
Recent trading has turned against the short-term trend for Modine Manufacturing, with the share price down 5.82% in the last session and 24.23% over 90 days, even though the year-to-date share price return is 26.55% and the 3-year total shareholder return is very large at more than 3x.
Scan beyond Modine Manufacturing and see how other data center and infrastructure plays are setting up right now with our curated list of 90 AI infrastructure stocks.
So is Modine Manufacturing’s pullback a verdict on the data center cooling business, or just a reset in sentiment after a huge multi year run that leaves the current valuation doing most of the talking next?
Most Popular Narrative: 41% Undervalued
On the most followed view of Modine Manufacturing, the gap between the $178.20 share price and a fair value of about $302 suggests the market is assigning a steep discount even after a sharp multi year run. That framework leans heavily on data center cooling demand and climate solutions to justify both the cash flow outlook and the 8.59% discount rate used.
The accelerating build-out of data centers and the need for next-generation cooling solutions is driving extraordinary demand for Modine's products, with management forecasting the potential to double data center revenues from approximately $1 billion in fiscal '26 to $2 billion by fiscal '28. This structural demand from digital infrastructure is set to materially boost revenue growth and deliver significant operating leverage over time.
See why 54 investors see Modine Manufacturing as 41% undervalued.
Result: Fair Value of $302.43 (UNDERVALUED)
Still, the bullish Modine Manufacturing story can crack if data center orders slow relative to its expanded capacity, or if acquisition integration keeps margins under pressure longer than expected.
Find out about the key risks to this Modine Manufacturing narrative.
Another View: Modine Manufacturing Looks Expensive On Earnings
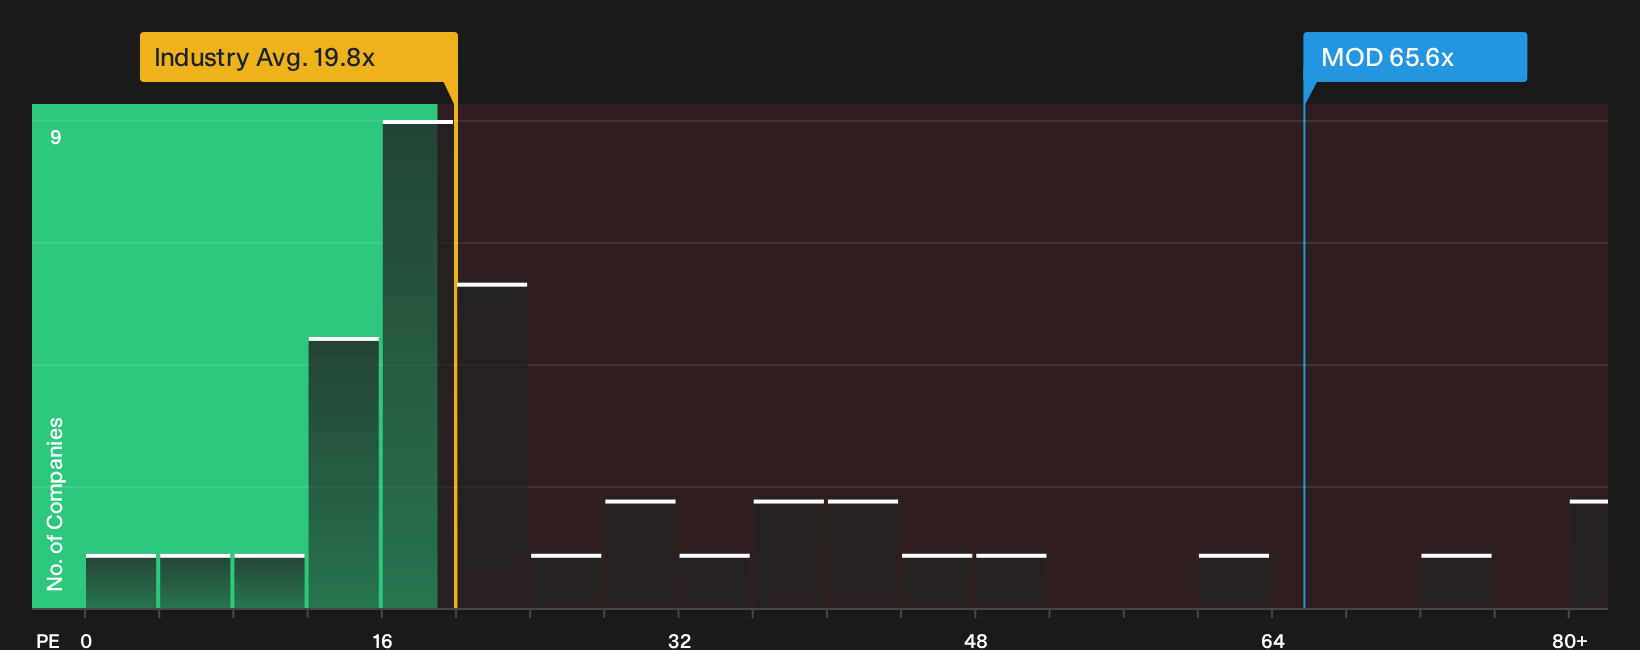
There is a different message if you ignore cash flows and look at Modine Manufacturing through its P/E ratio. The shares trade on about 65.6x earnings, compared with roughly 19.8x for the wider US Building group and a fair ratio of 72.2x. That keeps the story open. Is this a growth rerating that holds, or a rich multiple that eventually cools?
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling torn between Modine Manufacturing looking undervalued on cash flows yet expensive on earnings multiples is reasonable. This is why it pays to review the data yourself and weigh both the downside debate and upside potential before moving. To help frame that view, investors can benchmark the trade off with 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Modine Manufacturing?
If Modine Manufacturing has your attention, do not stop here. Broaden your watchlist with fresh ideas that match how you like to build a portfolio.
Spot potential bargains early by reviewing our 19 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Target resilience first and focus on capital preservation with a curated set of 31 resilient stocks with low risk scores that score well on business and balance sheet stability.
Strengthen your core holdings by filtering for companies on the list of solid balance sheet and fundamentals (25 results) that keep debt in check and financial flexibility front and center.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com