
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 UK Stocks Including Autotrader Group That May Be Priced Below Intrinsic Estimates
Amidst the recent downturn in the FTSE 100, driven by weak trade data from China and its ripple effects on global markets, UK investors are keenly observing opportunities that may arise in undervalued stocks. In such uncertain times, identifying stocks priced below their intrinsic value can offer a strategic advantage, as these investments have the potential for growth when market conditions stabilize.
Top 10 Undervalued Stocks Based On Cash Flows In The United Kingdom
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Stelrad Group (LSE:SRAD) | £1.47 | £2.48 | 40.7% |
| Smiths News (LSE:SNWS) | £0.786 | £1.46 | 46.2% |
| Smith & Nephew (LSE:SN.) | £9.89 | £17.42 | 43.2% |
| Property Franchise Group (AIM:TPFG) | £4.15 | £7.49 | 44.6% |
| Premier Foods (LSE:PFD) | £1.875 | £3.13 | 40% |
| Polar Capital Holdings (AIM:POLR) | £8.46 | £14.59 | 42% |
| PayPoint (LSE:PAY) | £6.35 | £10.72 | 40.7% |
| LSL Property Services (LSE:LSL) | £2.48 | £4.64 | 46.5% |
| Gamma Communications (LSE:GAMA) | £10.95 | £20.15 | 45.6% |
| Distribution Finance Capital Holdings (AIM:DFCH) | £0.744 | £1.37 | 45.8% |
Underneath we present a selection of stocks filtered out by our screen.
Autotrader Group (LSE:AUTO)
Overview: Autotrader Group plc operates an automotive platform in the United Kingdom with a market cap of £3.61 billion.
Operations: The company generates revenue through its Autorama segment, contributing £39 million, and its Auto Trader segment, which brings in £585.30 million.
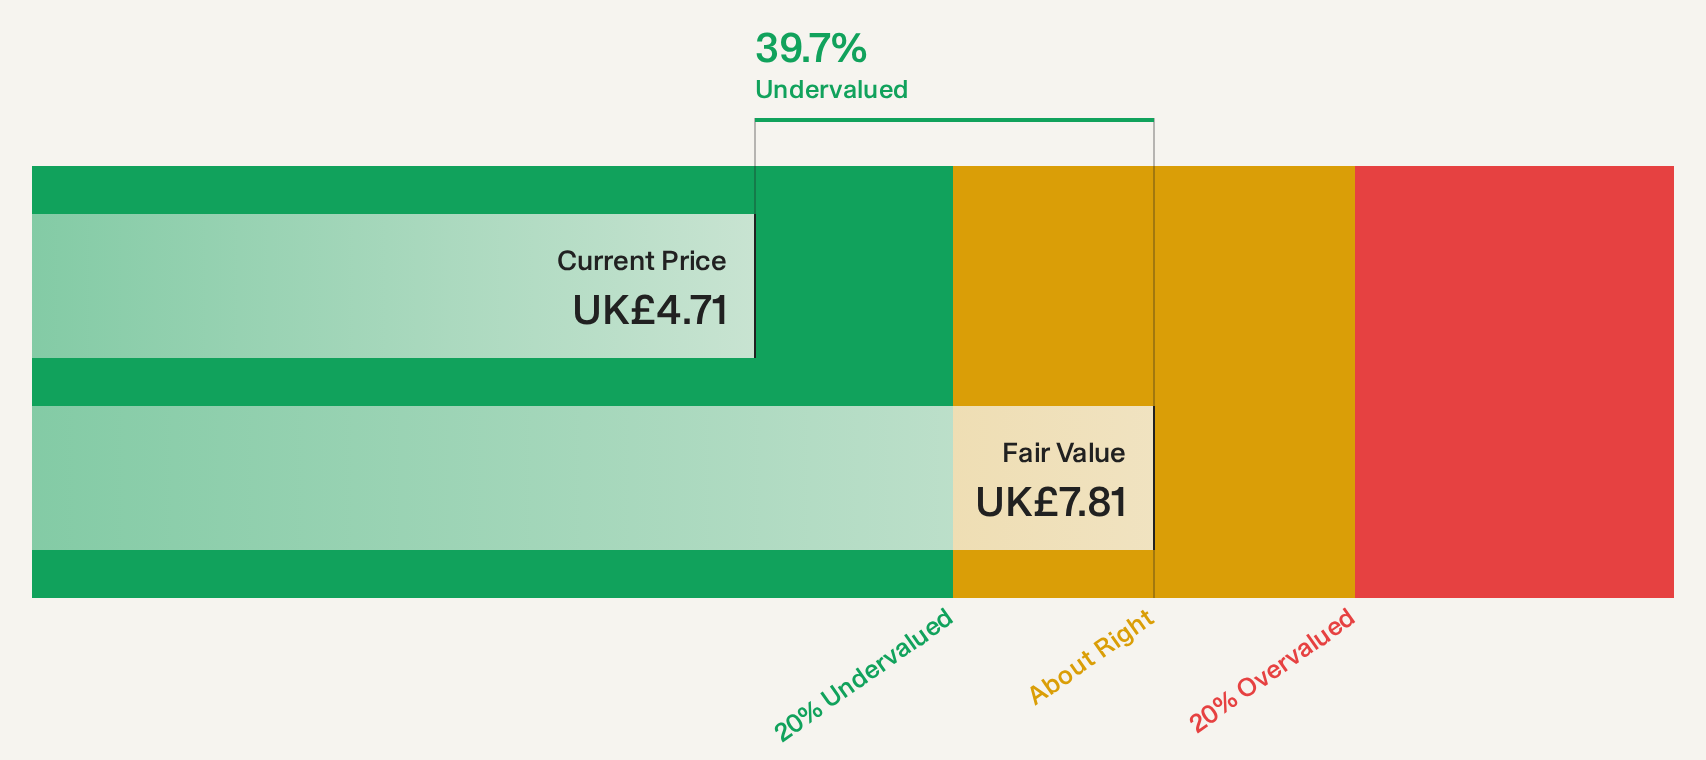
Estimated Discount To Fair Value: 40%
Autotrader Group is trading at £4.62, significantly below its estimated future cash flow value of £7.69, indicating it may be undervalued based on cash flows. Revenue growth is expected to outpace the UK market at 4.6% annually, though earnings growth lags behind at 3.5%. Despite an unstable dividend track record, a high return on equity forecast and good relative value compared to peers highlight its potential for investors focused on cash flow valuation.
- According our earnings growth report, there's an indication that Autotrader Group might be ready to expand.
- Click here to discover the nuances of Autotrader Group with our detailed financial health report.
Smiths News (LSE:SNWS)
Overview: Smiths News plc, with a market cap of £190.24 million, operates in the distribution of newspapers and magazines both in the United Kingdom and internationally.
Operations: The company generates revenue of £1.04 billion from distributing newspapers and magazines in the UK and internationally.
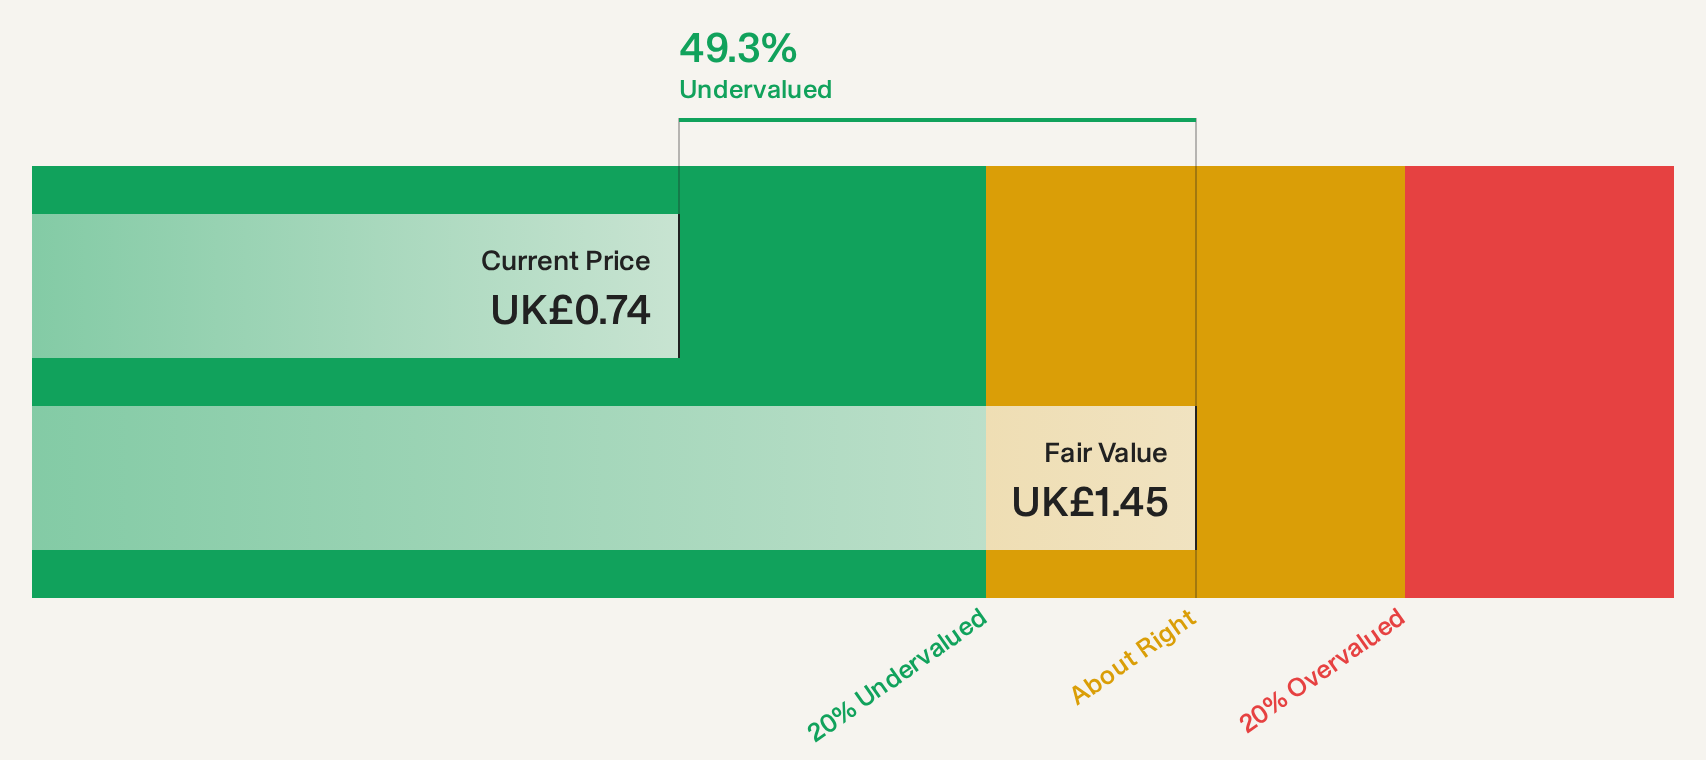
Estimated Discount To Fair Value: 46.2%
Smiths News trades at £0.79, below its estimated future cash flow value of £1.46, highlighting potential undervaluation based on cash flows despite expected revenue and earnings declines over the next three years. Recent long-term contracts with Frontline Limited and Seymour Distribution Limited provide enhanced revenue visibility and commercial certainty, representing an annual uplift of approximately £105 million from 2030. However, its dividend track record remains unstable amidst high return on equity forecasts in the coming years.
- Our expertly prepared growth report on Smiths News implies its future financial outlook may be stronger than recent results.
- Delve into the full analysis health report here for a deeper understanding of Smiths News.
Telecom Plus (LSE:TEP)
Overview: Telecom Plus Plc provides utility services in the United Kingdom and has a market cap of £632.69 million.
Operations: The company generates revenue from its non-regulated utility segment, amounting to £1.94 billion.
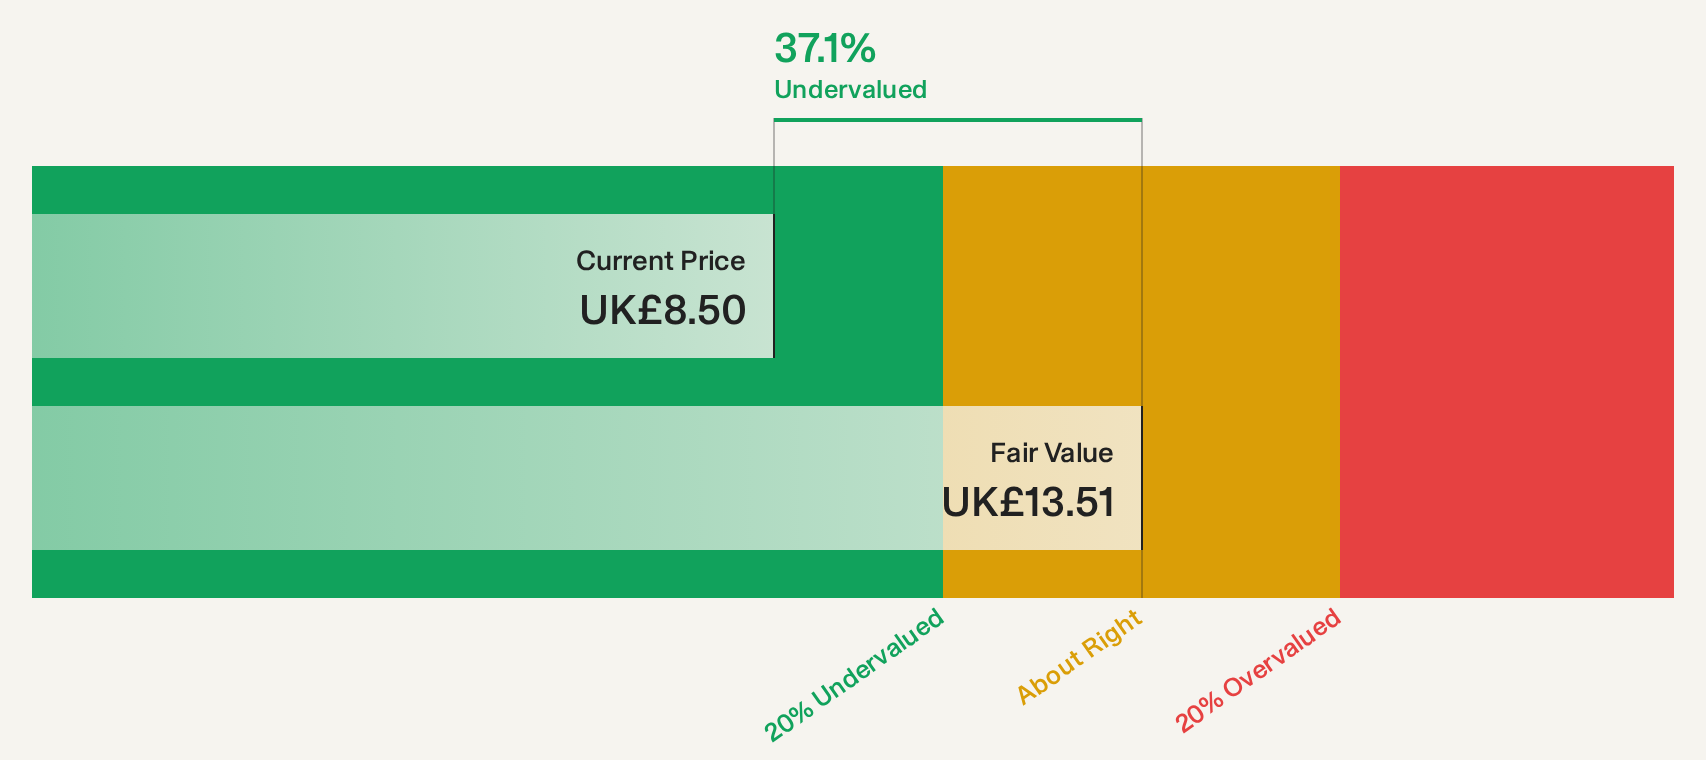
Estimated Discount To Fair Value: 39.9%
Telecom Plus trades at £8.12, significantly below its estimated future cash flow value of £13.51, suggesting potential undervaluation despite an unstable dividend track record and high debt levels. While earnings are projected to decline by 3.3% annually over the next three years, revenue is expected to grow at 5.4% per year, outpacing the UK market average of 3.8%. The stock offers good relative value compared to peers and industry standards.
- Our comprehensive growth report raises the possibility that Telecom Plus is poised for substantial financial growth.
- Click here and access our complete balance sheet health report to understand the dynamics of Telecom Plus.
Summing It All Up
- Access the full spectrum of 29 Undervalued UK Stocks Based On Cash Flows by clicking on this link.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com