
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Rubicon Research And 2 Indian Growth Stocks To Watch
Rising United States Treasury yields are pulling global money toward safer, higher income bonds, which makes it tougher for Indian companies to rely on cheap capital. That squeeze creates a spotlight on homegrown businesses that can fund expansion internally and are run by leaders with real skin in the game. This article explores three Indian stocks with high insider stakes that fit that profile.
The companies in this piece are just a small sample of the fast growing, high insider ownership stocks that fit this theme. The full screen surfaced 105 more businesses with equally compelling stories that are not covered here. If you want to move quickly from ideas to a focused watchlist, head straight into the Fast Growing Stocks With High Insider Ownership screener to identify, filter, and analyze the highest conviction opportunities that match your criteria.
Rubicon Research (NSEI:RUBICON)
Overview: Rubicon Research develops and manufactures specialty pharmaceutical products using its RubiReten and RubiSRL drug delivery platforms across multiple therapeutic areas.
Operations: Rubicon Research generates ₹19,358 million in revenue from pharmaceutical products, including generics, specialty formulations, APIs, and related services.
Market Cap: ₹270.0 billion
For investors focused on fast growing businesses where insiders are closely aligned with long term expansion plans, Rubicon Research illustrates how a focused drug delivery platform can support that type of growth narrative.
"Consistent R&D investment at roughly 10% to 11% of revenue, together with a record of commercialising 88% of approved products, points to a deeper product basket that can support future revenue and earnings visibility."
The key question for Rubicon Research is how margins and returns might change if a single key assumption around its product mix shifts.
If that mix shift is what you care about, read the full narrative for Rubicon Research to see where insiders, capital intensity, and product concentration could be decoupling.

Astra Microwave Products (BSE:532493)
Overview: Astra Microwave Products designs and manufactures radar and radio frequency subsystems for defense, aerospace, space, meteorology, and communication programs in India.
Operations: Astra Microwave Products generates about ₹11,397 million in revenue from radio frequency and microwave products serving multiple end markets.
Market Cap: ₹154.2 billion
Astra Microwave Products fits the fast growing, high insider ownership theme through its radar and RF work for defense and space. However, the real story hinges on how resilient that specialist position is as technology and competition shift around it.
"The rapid pace of technological change in communications and defense (including AI, photonics, and quantum-related systems) could lead to Astra's substantial R&D investments becoming obsolete or insufficient, resulting in loss of market share, compressing net margins, and stalling earnings growth if more agile global competitors outpace them."
The pressure point to watch is whether one subtle change in buyer preferences eventually resets the pricing power behind Astra Microwave Products.
That pricing reset risk is exactly why reading the full narrative for Astra Microwave Products can help you see whether Astra Microwave Products is quietly building a stronger competitive position.

Bajel Projects (NSEI:BAJEL)
Overview: Bajel Projects runs EPC contracts for high voltage power transmission and distribution, along with in-house manufacturing of poles and substation structures that support rapid grid build out.
Operations: Bajel Projects generates about ₹27,508 million in revenue from power transmission and power distribution focused EPC activities.
Market Cap: ₹18.9 billion
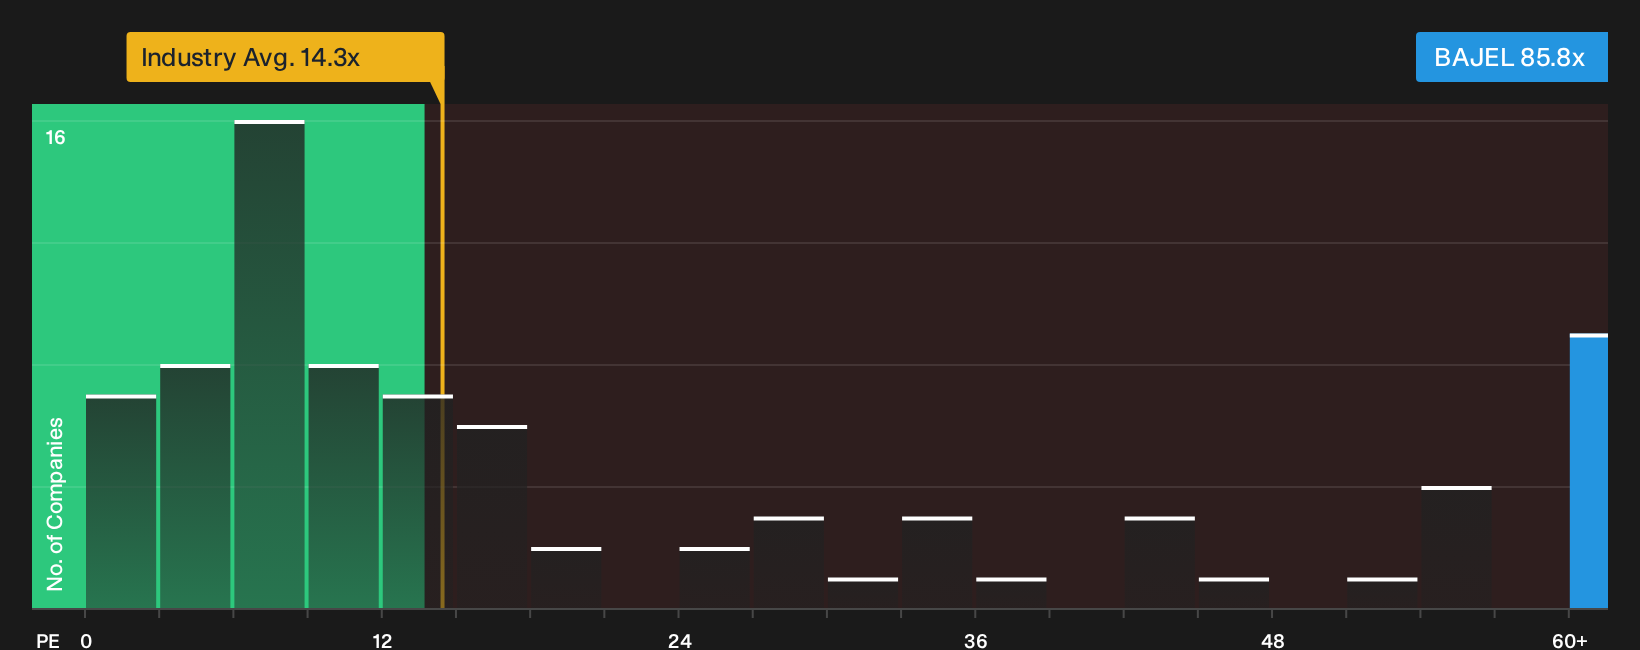
Bajel Projects combines forecast earnings growth of 57.7% a year with large EPC wins in India and Egypt that fit within the fast grid expansion theme. However, thin 0.8% profit margins and a high 85.8x P/E indicate that future returns depend significantly on how pricing power and profitability evolve as the current order book converts to cash.
That profit squeeze makes it worth scanning the 2 key rewards and 1 important warning sign before earnings momentum and contract wins start telling a different story.
Curious About Alternative Stock Paths
Fresh opportunities can move from quiet to flying under the radar for only so long. Scan these ideas before the crowd catches on and the best entry points drop, act now.
- Spot cash rich compounders early by comparing balance sheet strength across a curated list of solid balance sheet and fundamentals (206 results) before that quality gets fully priced in.
- Track where automation momentum is building and sift through a focused set of 89 robotics and automation stocks while valuations still reflect under the radar potential.
- Consider the AI infrastructure build out and review a hand picked basket of 90 AI infrastructure stocks before capital flows reset expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com