
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Asian Stocks Estimated To Be Up To 49.5% Below Intrinsic Value
In recent months, Asian markets have experienced mixed performance amid global economic uncertainties and fluctuating investor sentiment. Despite these challenges, opportunities may exist for investors seeking undervalued stocks that are estimated to be trading significantly below their intrinsic value. Identifying such stocks requires a comprehensive analysis of market conditions and company fundamentals to uncover potential investment opportunities in the region.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Shanghai Flyco Electrical Appliance (SHSE:603868) | CN¥31.09 | CN¥61.62 | 49.5% |
| Nissui (TSE:1332) | ¥1098.00 | ¥2180.59 | 49.6% |
| Kingnet Network (SZSE:002517) | CN¥16.01 | CN¥31.56 | 49.3% |
| Innodisk (TPEX:5289) | NT$1295.00 | NT$2530.08 | 48.8% |
| Ichikoh Industries (TSE:7244) | ¥540.00 | ¥1066.37 | 49.4% |
| Hainan Jinpan Smart Technology (SHSE:688676) | CN¥61.53 | CN¥121.78 | 49.5% |
| Foxconn Industrial Internet (SHSE:601138) | CN¥58.20 | CN¥113.22 | 48.6% |
| ENN Energy Holdings (SEHK:2688) | HK$48.62 | HK$96.82 | 49.8% |
| Double Medical Technology (SZSE:002901) | CN¥40.86 | CN¥79.59 | 48.7% |
| China Coal Energy (SEHK:1898) | HK$10.17 | HK$20.10 | 49.4% |
Here we highlight a subset of our preferred stocks from the screener.
HAESUNG DS (KOSE:A195870)
Overview: HAESUNG DS Co., Ltd. manufactures and sells semiconductor components both in South Korea and internationally, with a market cap of ₩1.11 trillion.
Operations: The company generates revenue of ₩758.27 billion from its semiconductor segment.
Estimated Discount To Fair Value: 42.1%
HAESUNG DS is trading at ₩65,300, significantly below its estimated future cash flow value of ₩112,771.27. Analysts agree the stock price could rise by 29%, with earnings projected to grow 35.43% annually—outpacing the Korean market's 28.4%. Despite high volatility and a dividend yield not well covered by free cash flows, HAESUNG DS presents an undervalued opportunity based on discounted cash flow analysis.
- Our expertly prepared growth report on HAESUNG DS implies its future financial outlook may be stronger than recent results.
- Unlock comprehensive insights into our analysis of HAESUNG DS stock in this financial health report.
Netmarble (KOSE:A251270)
Overview: Netmarble Corporation develops and publishes PC, mobile, and console games in South Korea and internationally, with a market cap of ₩2.83 trillion.
Operations: The company's revenue primarily comes from the development and publishing of game software, totaling ₩2.89 trillion.
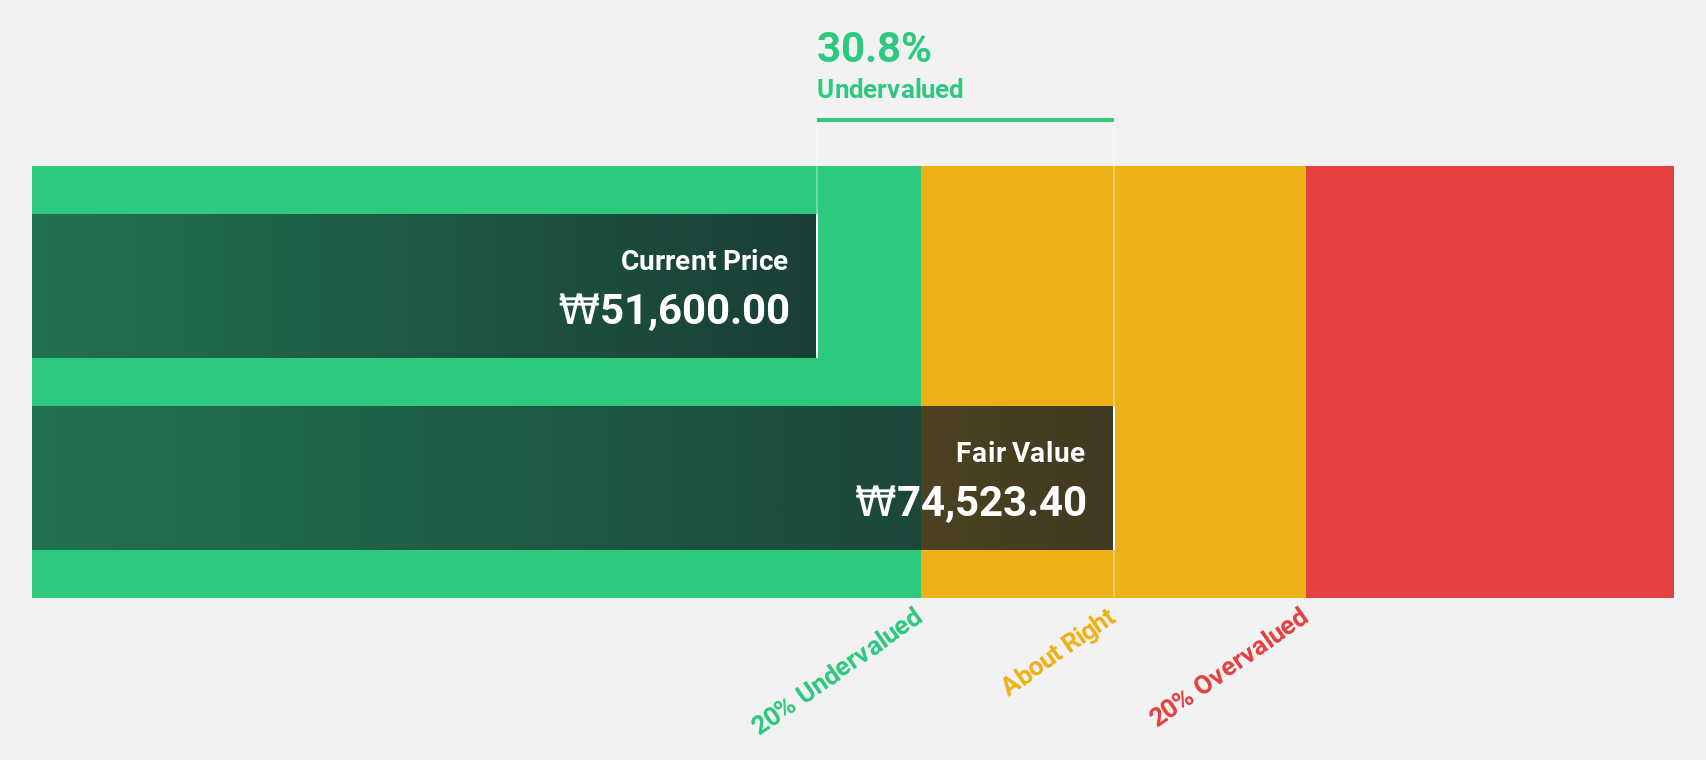
Estimated Discount To Fair Value: 34.4%
Netmarble is trading at ₩35,350, well below its estimated future cash flow value of ₩53,894.60, suggesting it is undervalued based on discounted cash flow analysis. Despite a 328.5% earnings growth last year, forecasts indicate a 13% annual decline in earnings over the next three years. Recent product launches like RAVEN2's ZERO server and Ni no Kuni: Cross Worlds' global service may impact revenue positively but can't offset the predicted earnings decline entirely.
- Insights from our recent growth report point to a promising forecast for Netmarble's business outlook.
- Click here and access our complete balance sheet health report to understand the dynamics of Netmarble.
Hainan Jinpan Smart Technology (SHSE:688676)
Overview: Hainan Jinpan Smart Technology Co., Ltd. focuses on the research, development, production, sale, and servicing of power transmission and distribution as well as control equipment products in China, with a market cap of CN¥28.25 billion.
Operations: Hainan Jinpan Smart Technology Co., Ltd. generates revenue through its involvement in the research, development, production, sale, and servicing of power transmission and distribution along with control equipment products within China.
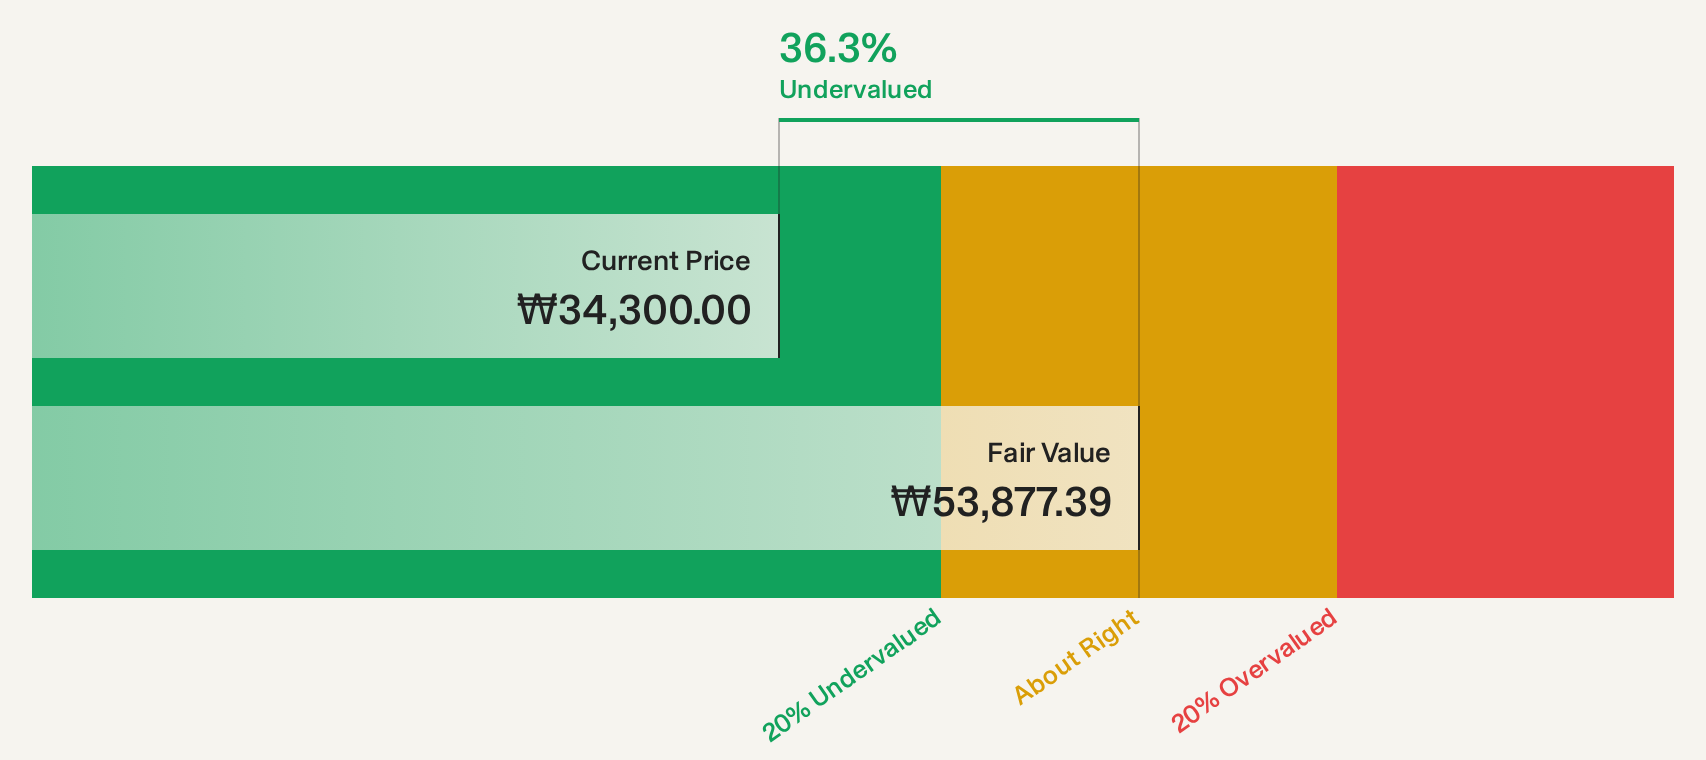
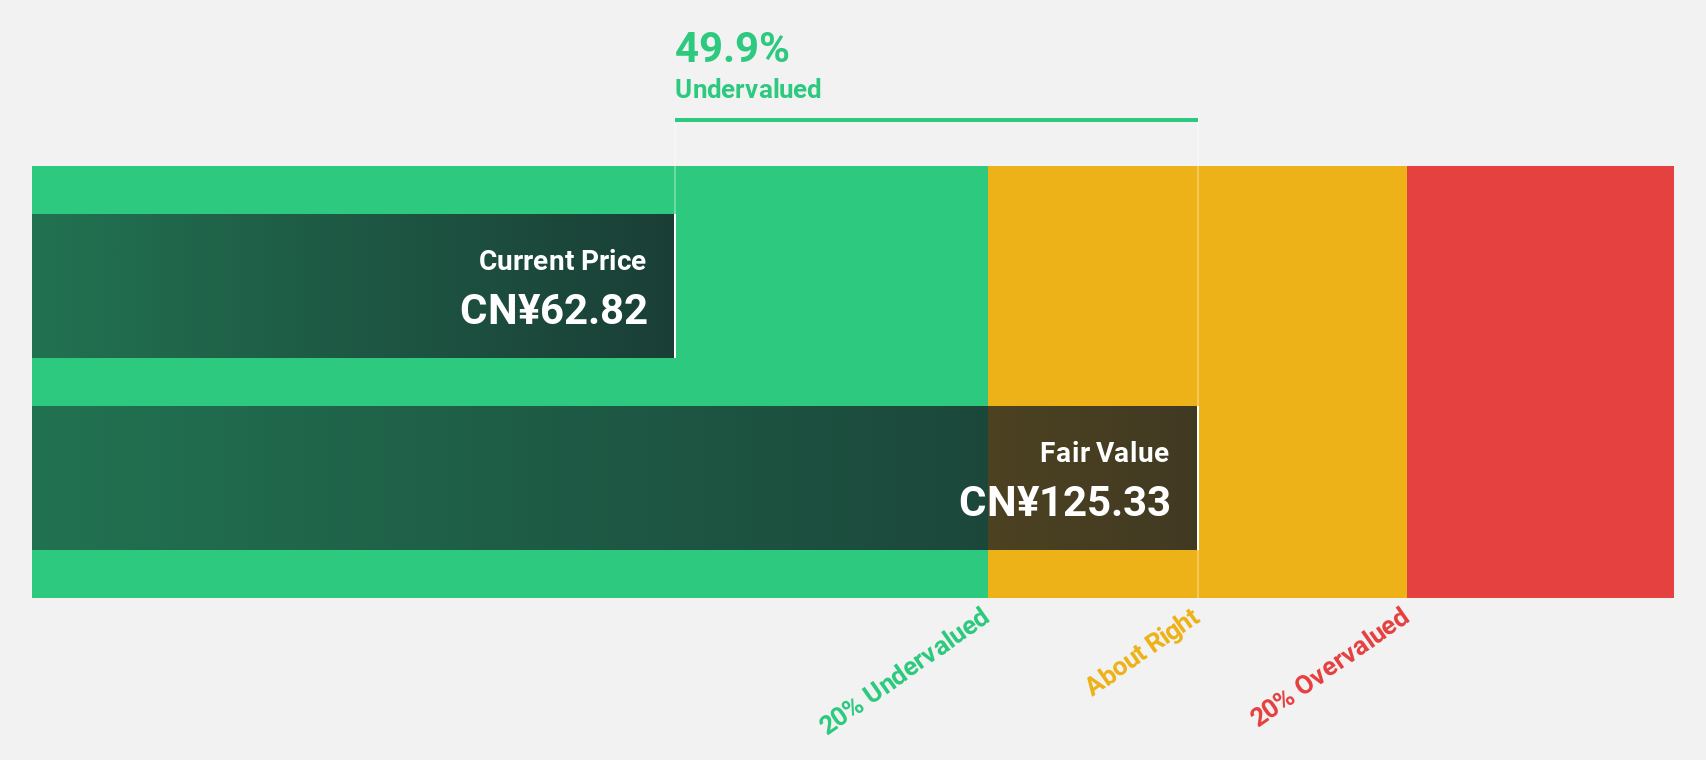
Estimated Discount To Fair Value: 49.5%
Hainan Jinpan Smart Technology is trading at CN¥61.53, significantly below its estimated future cash flow value of CN¥121.78, indicating undervaluation. The company's earnings are forecast to grow substantially at 34.56% annually over the next three years, outpacing the Chinese market's growth rate of 27.3%. Despite a volatile share price and a dividend yield not fully covered by free cash flows, recent revenue and earnings reports show strong year-on-year growth.
- According our earnings growth report, there's an indication that Hainan Jinpan Smart Technology might be ready to expand.
- Navigate through the intricacies of Hainan Jinpan Smart Technology with our comprehensive financial health report here.
Seize The Opportunity
- Navigate through the entire inventory of 166 Undervalued Asian Stocks Based On Cash Flows here.
- Already own these companies? Link your portfolio to Simply Wall St and get alerts on any new warning signs to your stocks.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com