
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
October 2026's Top Asian Growth Companies With Strong Insider Ownership
As of October 2026, Asian markets have been navigating a landscape marked by fluctuating global economic indicators and regional policy shifts, with investors closely monitoring interest rate trends and inflationary pressures. In such an environment, growth companies with strong insider ownership can be particularly appealing as they may indicate confidence in the company's future prospects and align management's interests with those of shareholders.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Skychem Technology (SHSE:688603) | 31.8% | 67.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34.3% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| HUMAN MADE (TSE:456A) | 29.1% | 29.5% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We'll examine a selection from our screener results.
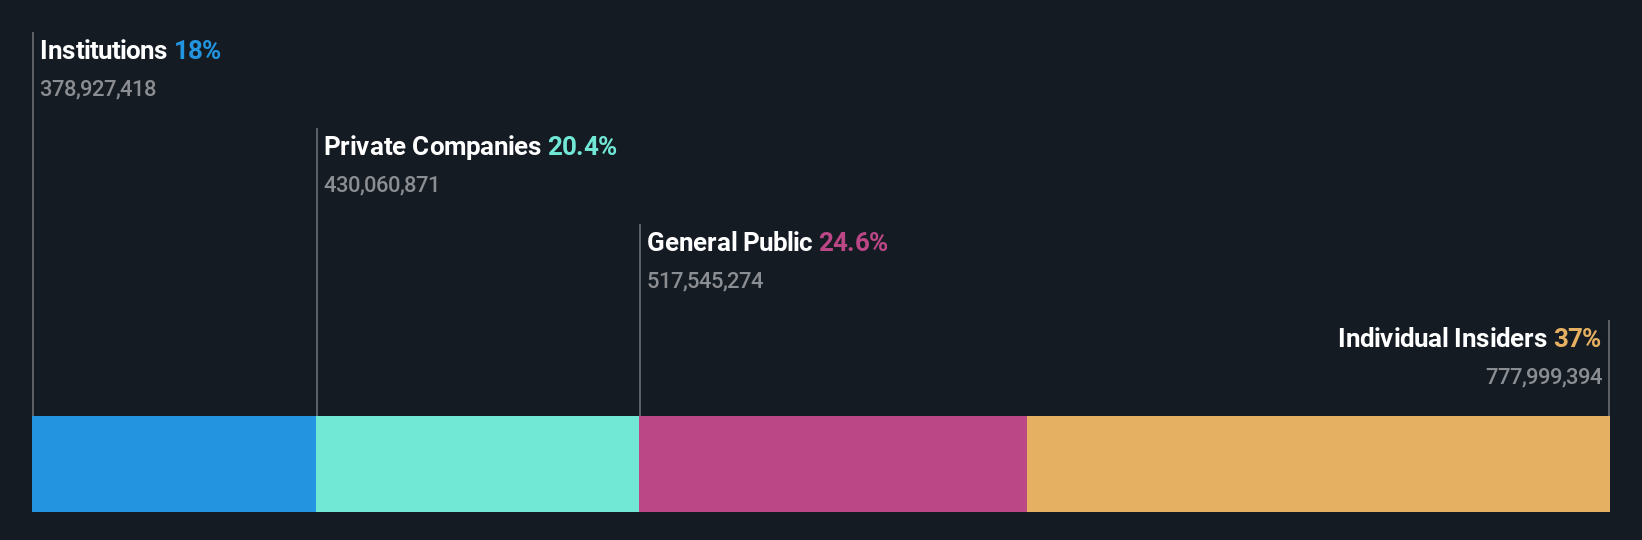
Shanghai Putailai New Energy Technology GroupLtd (SHSE:603659)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Shanghai Putailai New Energy Technology Group Co., Ltd. develops and sells materials for lithium-ion batteries and automation equipment both in China and internationally, with a market cap of CN¥45.29 billion.
Operations: Shanghai Putailai New Energy Technology Group Co., Ltd. generates revenue through the development and sale of materials for lithium-ion batteries as well as automation equipment, serving both domestic and international markets.
Insider Ownership: 36.5%
Earnings Growth Forecast: 27.6% p.a.
Shanghai Putailai New Energy Technology Group Ltd. demonstrates significant growth potential with forecasted annual earnings growth of 27.6%, surpassing the Chinese market average. Despite trading at a substantial discount to its estimated fair value, its Return on Equity is expected to remain modest at 17.8%. Recent earnings reports show robust revenue and net income increases, while a CNY 300 million share buyback program underscores management's confidence in long-term prospects without recent insider trading activity.
- Take a closer look at Shanghai Putailai New Energy Technology GroupLtd's potential here in our earnings growth report.
- The valuation report we've compiled suggests that Shanghai Putailai New Energy Technology GroupLtd's current price could be quite moderate.
Yuanjie Semiconductor Technology (SHSE:688498)
Simply Wall St Growth Rating: ★★★★★★
Overview: Yuanjie Semiconductor Technology Co., Ltd. (ticker: SHSE:688498) operates in the semiconductor industry and has a market cap of approximately CN¥200.38 billion.
Operations: Yuanjie Semiconductor Technology generates revenue from its operations in the semiconductor industry, with a market capitalization of around CN¥200.38 billion.
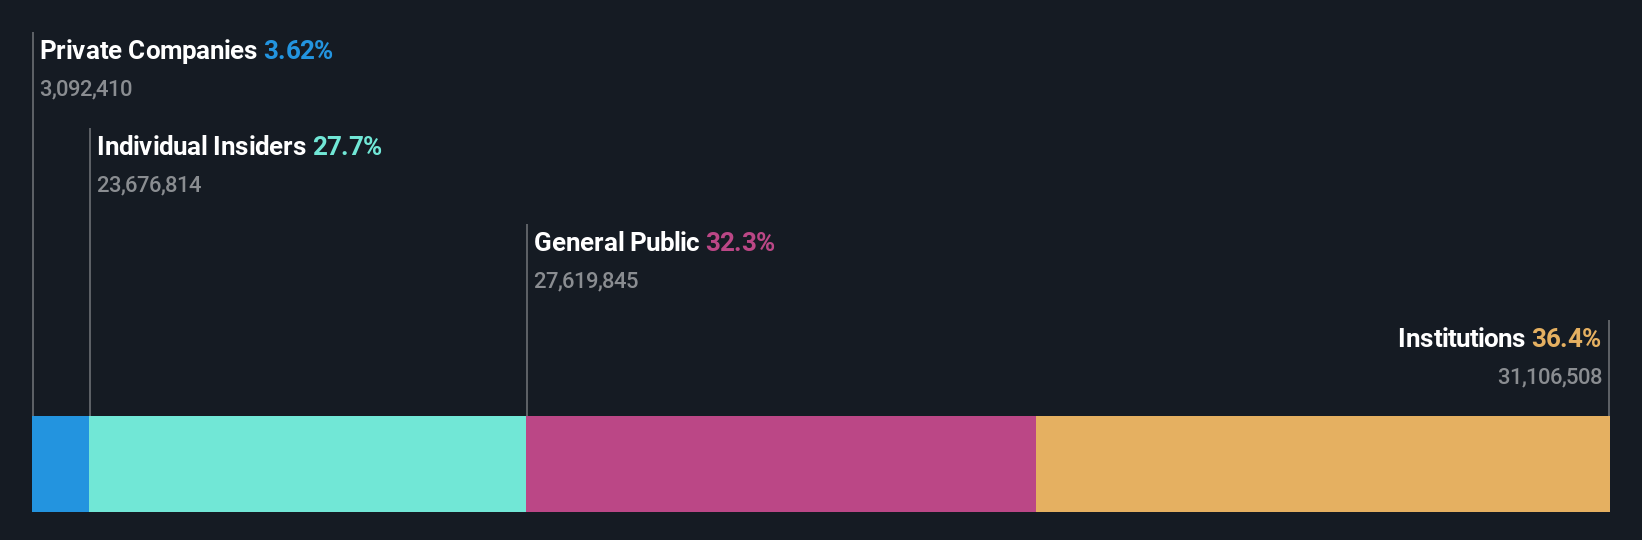
Insider Ownership: 27.7%
Earnings Growth Forecast: 55.2% p.a.
Yuanjie Semiconductor Technology exhibits strong growth potential, with earnings and revenue expected to grow significantly faster than the Chinese market at 55.2% and 39.6% annually, respectively. Recent financial results highlight a substantial increase in net income to CNY 607.07 million from CNY 46.26 million year-on-year, demonstrating robust performance despite share price volatility. The company's high insider ownership aligns management interests with shareholders, supporting its long-term growth trajectory without recent insider trading activity noted.
- Click here and access our complete growth analysis report to understand the dynamics of Yuanjie Semiconductor Technology.
- Our valuation report unveils the possibility Yuanjie Semiconductor Technology's shares may be trading at a premium.
Dazhong Mining (SZSE:001203)
Simply Wall St Growth Rating: ★★★★★★
Overview: Dazhong Mining Co., Ltd. is involved in the mining and beneficiation of iron ore, with a market cap of CN¥33.89 billion.
Operations: The company's revenue is primarily derived from its Mining and Smelting Industry segment, which generated CN¥3.90 billion.
Insider Ownership: 26.7%
Earnings Growth Forecast: 56.3% p.a.
Dazhong Mining demonstrates significant growth potential, with earnings and revenue forecasted to grow at 56.3% and 41.6% annually, outpacing the Chinese market. Despite a recent dip in half-year sales and net income to CNY 1.77 billion and CNY 322.04 million respectively, expectations remain high due to strong projected returns on equity of 22.4%. The absence of recent insider trading activity suggests stable insider confidence amid structural changes approved in July 2026.
- Navigate through the intricacies of Dazhong Mining with our comprehensive analyst estimates report here.
- Our expertly prepared valuation report Dazhong Mining implies its share price may be too high.

Key Takeaways
- Delve into our full catalog of 497 Fast Growing Asian Companies With High Insider Ownership here.
- Searching for a Fresh Perspective? We've found 8 US stocks that are forecast to pay a dividend yeild of over 6% next year. See the full list for free.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com