
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Novozymes (CPSE:NSIS B) Is Back In The Spotlight
Why the West Allis expansion matters for Novozymes investors
Novozymes (CPSE:NSIS B) is back in focus after Novonesis completed a major expansion of its West Allis, Wisconsin facility, significantly increasing North American dairy culture fermentation and packaging capacity.
The site is now positioned among the largest lactobacillus production hubs globally. It features energy efficient equipment, water reuse systems, and waste heat recovery designed to limit environmental impact while serving growing demand for nutritious food products.
For investors watching Novozymes, the West Allis upgrade lands at a time when the DKK416.0 share price has delivered a 4.84% year-to-date share price return. The 1-year total shareholder return of 8.23% and 3-year total shareholder return of 49.87% point to momentum that has built over a longer horizon, even as the past month’s 4.72% share price decline suggests some cooling in the near term.
Scan other enzyme and biosolutions specialists showing similar capacity build outs and pricing power signals using our curated list of 615 high quality undiscovered gems tied to real-world demand for specialty ingredients.
Novozymes now trades at a double discount, about 20% below the average analyst target and roughly 47% under one intrinsic value estimate. Is that genuine mispricing or a fair warning label after the recent pullback?
Most Popular Narrative: 15% Undervalued
On the most widely followed view, Novozymes is worth DKK491.93 per share, which sits above the last close of DKK416 and frames the current discount as a valuation gap that hinges on execution across multiple growth projects.
Structural growth in bioenergy from higher blend mandates, new second generation ethanol and biodiesel capacity in India, Latin America and Europe, and technology driven efficiency gains in existing plants should support high single digit growth in Agriculture, Energy & Tech and underpin cash flow and earnings expansion.
See why 5 investors see Novozymes as 15% undervalued.
The narrative uses a 5.72% discount rate on future cash flows, ties fair value to assumptions for revenue of €5.3b and earnings of €1.0b by 2029, and then checks whether a 36.1x P/E on those projected profits can justify a DKK491.93 outcome against the current DKK416 price.
Result: Fair Value of DKK491.93 (UNDERVALUED)
Still, the Novozymes story can change quickly if currency headwinds bite into euro based earnings or if heavy spending in emerging markets fails to deliver scale.
Find out about the key risks to this Novozymes narrative.
Another View on Novozymes’ valuation
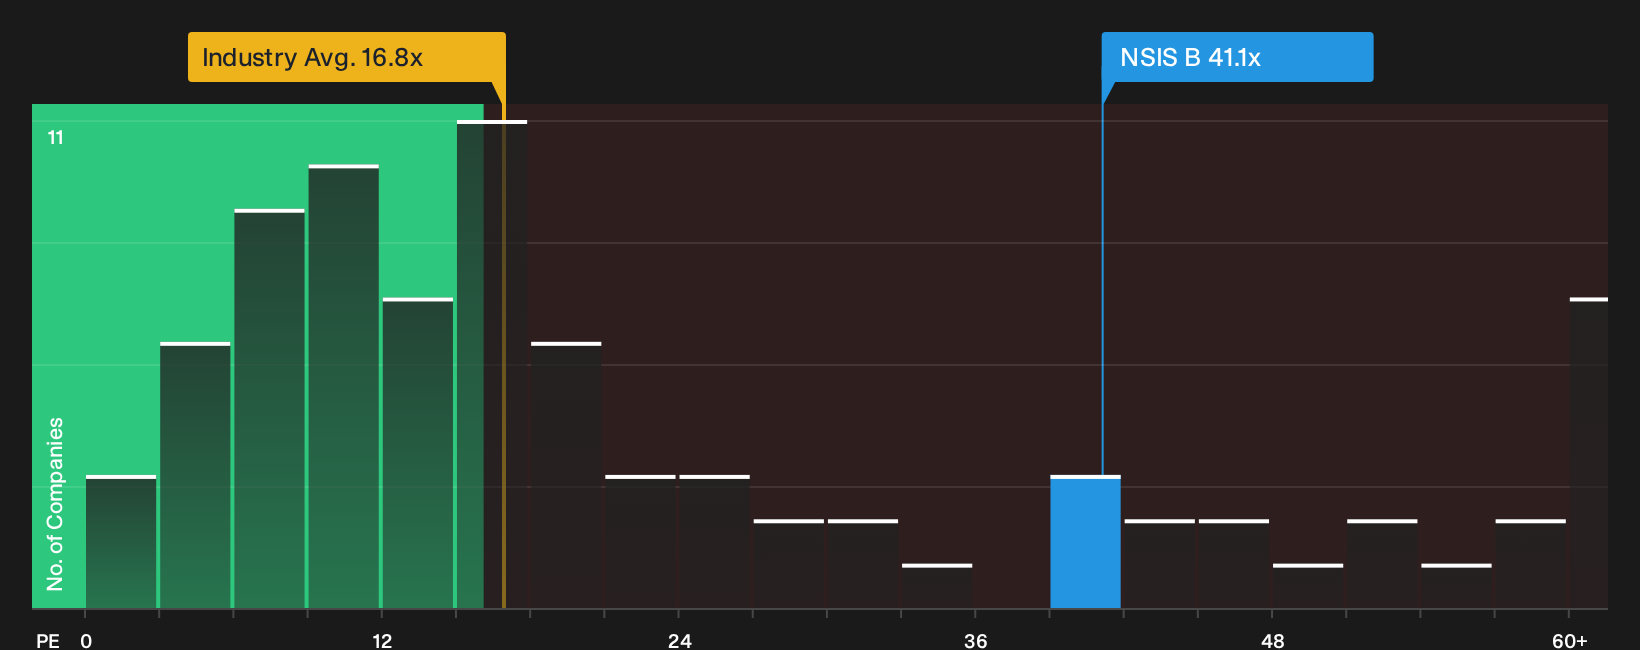
The first story presents Novozymes as undervalued based on future earnings and cash flow. Today, however, the shares trade on a P/E of 41.1x. That compares with 30.6x for peers, 16.8x for the broader European chemicals group, and a fair ratio of 27.7x. Current pricing therefore appears to incorporate a significant degree of optimism. Which lens do you trust more when real money is on the line?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Novozymes can feel messy, so move quickly, review the underlying risks and potential upsides, then weigh the 4 key rewards and 1 important warning sign.
Looking for more Novozymes sized investment ideas?
If Novozymes has your attention, do not stop here. Broaden your watchlist with other focused ideas built from real balance sheet strength, income potential, and value screens.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (206 results) that already filters for financial strength and fundamental quality.
- Hunt for mispriced opportunities using a 192 high quality undervalued stocks that highlights companies combining quality metrics with potentially attractive entry prices.
- Build a steadier income stream by reviewing a 168 dividend fortresses built around higher yielding payouts with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com