
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Primaris Real Estate Investment Trust (TSX:PMZ.UN) Could Be 54% Undervalued After Upper Canada Mall Deal
Primaris Real Estate Investment Trust’s Upper Canada Mall Deal
Primaris Real Estate Investment Trust (TSX:PMZ.UN) has agreed to buy Upper Canada Mall in Newmarket, Ontario for $411 million in cash, a transaction that management expects will influence future net operating income and portfolio scale.
For context, Primaris Real Estate Investment Trust units trade at CA$22.15, with a 30-day share price return of 4.73% and year-to-date share price gain of 42.44%. The 1-year total shareholder return of 50.30% and 3-year total shareholder return of 96.72% suggest momentum has been building as investors digest recent moves such as the September follow-on equity offering and this Upper Canada Mall acquisition.
Compare Primaris Real Estate Investment Trust’s move with other potential real estate and income ideas by scanning our hand picked 1 dividend fortresses.
Bulls see Primaris Real Estate Investment Trust using Upper Canada Mall to scale NOI and reinforce a focused platform. Bears see concentration risk and fresh leverage. Which story do the current numbers lean toward as you weigh valuation next?
Price-to-Earnings of 22.1x for Primaris Real Estate Investment Trust: Is it justified?
Primaris Real Estate Investment Trust changes hands at a P/E of 22.1x, a level that points to a richer valuation than its own fair ratio estimate even though it sits slightly below the wider North American Retail REITs peer group.
The P/E ratio compares the current unit price to earnings per unit and helps you see how much investors are paying for each dollar of profit. For a landlord like Primaris Real Estate Investment Trust, that earnings multiple often reflects expectations around rental income durability, occupancy outcomes, and the reliability of cash distributions.
PMZ.UN is described as expensive versus its estimated fair P/E of 18.4x. This suggests the market is paying a higher multiple than this model implies could be sustainable. That premium, alongside dilution over the past year, indicates investors are currently accepting a fuller price to access the REIT’s recent earnings growth and high quality earnings profile.
Compared with the North American Retail REITs industry average P/E of 23.9x, the units trade on a slightly cheaper multiple, which still remains above the 18.4x fair ratio estimate. That mix signals investors are valuing Primaris broadly in line with the sector while assigning a higher multiple than the level this fair value framework suggests the market could move toward over time.
Explore the SWS fair ratio for Primaris Real Estate Investment Trust.
Result: Price-to-Earnings of 22.1x (OVERVALUED)
Still, Primaris Real Estate Investment Trust faces risk if the Upper Canada Mall purchase increases concentration in a single asset, while fresh equity raises weigh on per unit metrics.
Find out about the key risks to this Primaris Real Estate Investment Trust narrative.
Another View on Primaris Real Estate Investment Trust’s Value
The SWS DCF model paints a very different picture for Primaris Real Estate Investment Trust. At CA$22.15, the units trade at a 53.7% discount to an estimated future cash flow value of CA$47.88. This points to a scenario where cash generation suggests significantly more upside than the P/E ratio implies.
For investors weighing which signal to trust, the question becomes whether earnings multiples or long range cash flow assumptions better capture where Primaris Real Estate Investment Trust really sits today, and which type of risk you are more comfortable taking.
Look into how the SWS DCF model arrives at its fair value.
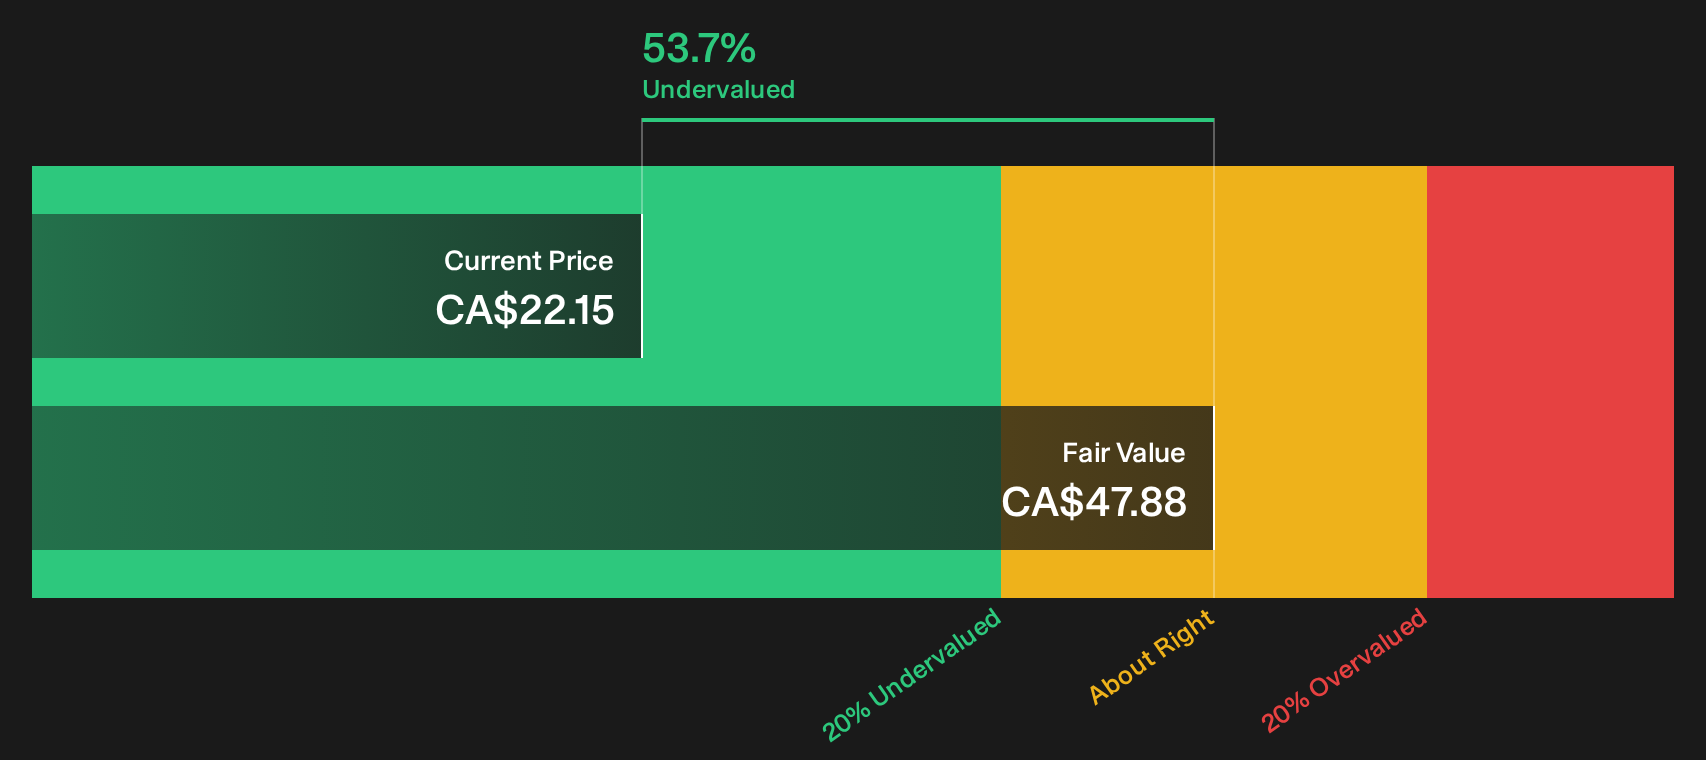
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Primaris Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Primaris Real Estate Investment Trust so far. If you want to move quickly and form your own judgment, start with the 3 key rewards and 2 important warning signs.
Looking for more Primaris Real Estate Investment Trust sized ideas?
You have already put in the work on Primaris Real Estate Investment Trust. Do not stop there when other opportunities might suit your income goals and risk limits even better.
- Target dependable income streams by reviewing our hand picked list of resilient high yield payers through the 1 dividend fortresses.
- Hunt for quality at a discount by scanning the 6 high quality undervalued stocks that blend solid fundamentals with room for potential re rating.
- Protect your downside first by focusing on strength of finances using the list of solid balance sheet and fundamentals (7 results) so you are not late to stronger opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com