
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Missed Weatherford International's 23% Run? What Held Up
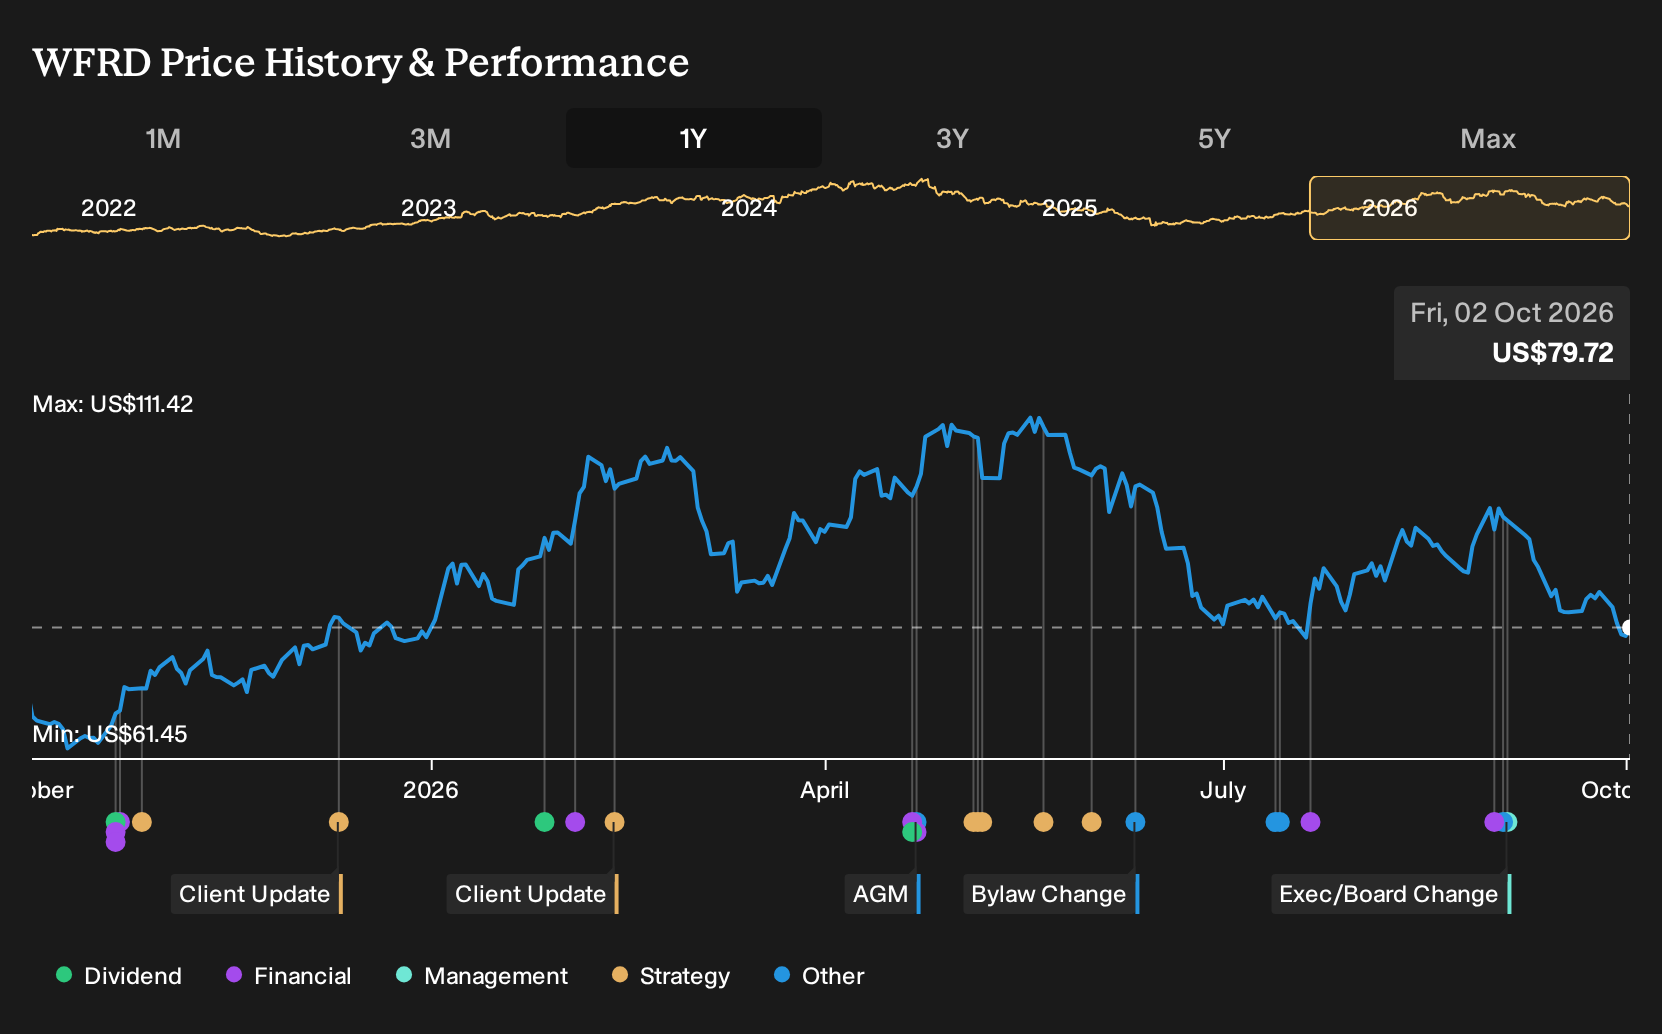
If you only glanced at headlines about falling Weatherford International margins and weaker Q2 2026 profits, you might assume shareholders were punished. Investors who held Weatherford International over the past year are up 22.9%, including dividends. If you had bought on 2 October 2025, you would be looking at that outcome while reading about lower revenue and net income. So what did the record at the start actually signal about this risk and reward mix?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Weatherford International harder to judge, start where the gap is still open and scan 31 high quality undervalued stocks.
The Two Weatherford International Stories Investors Had To Weigh
The shares cost US$66.29 at the start of the period, so anyone looking at Weatherford International then had to decide which future felt more plausible.
The bull narrative pointed to a fair value of US$73, about 10% above the start price. This view was built on expansion in Middle East and Asian oilfield regions and heavier use of digital tools such as ForeSite Power.
The bear narrative suggested a fair value of US$59, about 11% below the start price, and highlighted falling activity in Mexico and softer demand in North America and Europe as core risks.
What The Q2 Numbers And Contracts Said About Weatherford International
Weatherford International secured new offshore work in Brazil and other deepwater contracts, which supported the optimistic story about international and completions strength. The harder hit came from the Q2 2026 report. Revenue slipped from US$1,204 million to US$1,105 million, and net income dropped from US$136 million to US$39 million. Net margin moved from 11.3% to 3.5%. Overall, the evidence cut both ways.
The decision back in October 2025 largely turned on margin resilience. When you test a similar thesis elsewhere, track not just revenue but also the direction of reported net margin relative to what the original bull and bear cases assumed.
What Weatherford International’s Price Now Asks You To Believe
Weatherford International now trades at US$79.72, with this Narrative’s Fair Value placed above that level rather than below it. The argument leans on a heavier mix of higher margin, capital light services and disciplined pruning of lower quality operations.
The Narrative also leans on strong free cash flow conversion and balance sheet flexibility. A buyer today would need to judge whether sustained high free cash flow conversion alongside geopolitical and integration risks can keep holding.
"Weatherford International’s emphasis on free cash flow as a primary performance metric, with recent guidance for mid to high 40% free cash flow conversion and net leverage at 0.34x alongside about US$1.14b of cash and restricted cash, suggests continued room for stronger free cash flow and balance sheet flexibility that can influence equity valuation metrics."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where Weatherford’s Work Leads Next
Weatherford International helps keep hydrocarbons flowing. Your next question is what happens before that gas even reaches key projects.
Moving gas from the well to power plants and liquefaction sites requires intense compression. That physical step is not optional when pressure and flow fall out of balance.
One specialist business focuses almost entirely on owning and running that compression horsepower for customers that need reliable throughput.
Its role is closer to long life infrastructure than short cycle services, with contracts and hardware that can sit on location for years.
If you are curious about what that kind of compressed gas toll road might mean for returns, the detailed case starts in the next section.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 48% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com