
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CVB Financial (CVBF) Could Be 11% Undervalued As Efficiency Supports The Narrative
CVB Financial (CVBF) has been drawing attention after recent trading moves, with the share price closing at US$22.28. Investors are weighing its returns across different periods and the scale of its banking operations.
Recent trading has been choppy for CVB Financial, with the share price up 1.23% on the day but the 30 day share price return down 1.50%. At the same time, a 19.34% year to date share price gain and 22.04% one year total shareholder return point to momentum that has built over a longer stretch rather than in the last few weeks.
Scan how CVB Financial’s recent moves compare with other banks showing similar trading patterns by reviewing the curated 31 resilient stocks with low risk scores in the current market.
For CVB Financial, that mix of short term softness and stronger longer term gains raises a simple tension: Are investors reacting to the bank’s underlying progress, or is this mostly a sentiment swing that the valuation now has to justify?
Most Popular Narrative: 11% Undervalued
At a last close of $22.28, the most followed narrative for CVB Financial points to a fair value estimate of $25.17. This implies the current trading level sits at an 11.5% discount once that view is applied using a 7.11% discount rate.
The company's disciplined expense control and operational efficiency through technology investment, branch optimization, and lease negotiations support industry-leading efficiency ratios and provide positive operating leverage even in periods of slow loan growth, benefiting net margins and long-term profitability.
See why 10 investors see CVB Financial as 11% undervalued.
Result: Fair Value of $25.17 (UNDERVALUED)
Still, CVB Financial’s heavy tilt to California and sizeable commercial real estate exposure could challenge that undervalued narrative if credit quality or loan demand weaken.
Find out about the key risks to this CVB Financial narrative.
Another View On CVB Financial’s Valuation
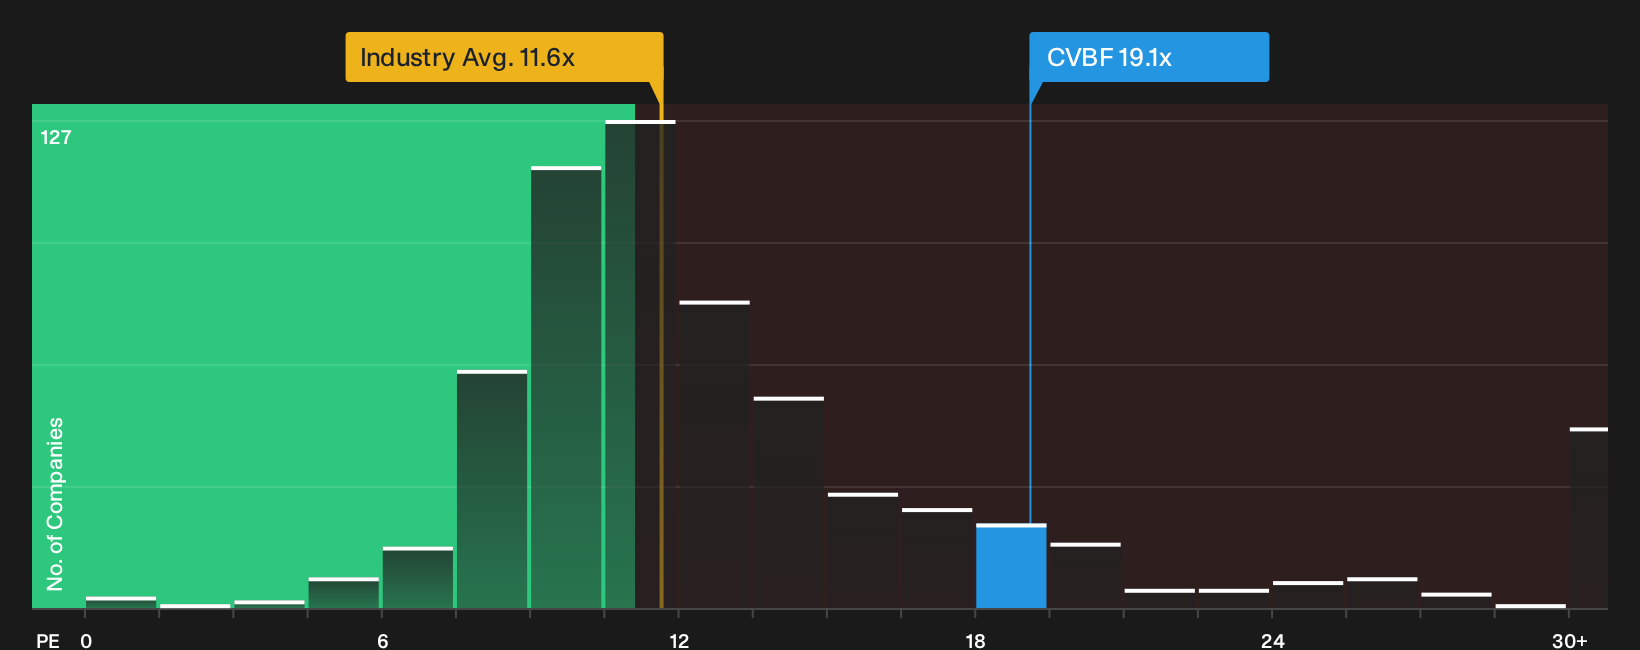
There is a wrinkle to the CVB Financial story. On headline P/E, the stock trades at 19.1x earnings, which is higher than both the US Banks industry on 11.6x and an estimated fair ratio of 16.1x. That gap points to valuation risk even if the DCF case suggests upside.
Investors weighing these mixed signals may want to stress test what would need to go right on earnings growth, margins and credit costs for the current premium P/E to hold, and what happens if the market instead gravitates back toward that lower fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unclear whether CVB Financial’s recent moves leave you confident or cautious. Act while the data is still fresh, and weigh both sides of the story by reviewing 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond CVB Financial?
Do not stop with CVB Financial. Use the Simply Wall Street Screener to quickly spot fresh opportunities that match your risk tolerance and income goals.
- Target potential mispricing and hunt for quality companies trading below estimated value by scanning the 31 high quality undervalued stocks.
- Build a steadier income stream and focus on companies offering stronger yields through the 7 dividend fortresses.
- Prioritize resilience and sleep easier at night by filtering for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com