
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should High Grade Drill Results Require Action From OceanaGold (TSX:OGC) Investors?
- OceanaGold reported new drill results from 16 holes at the Wharekirauponga project in New Zealand, with multiple wide, high-grade gold intercepts in the EG Vein and hanging wall structures that support continuity in the southern high-grade zone.
- The company has expanded to five active rigs and added a new drill site focused on the open southern high-grade area, which could improve confidence in resource conversion and the longer term operating potential of Wharekirauponga.
- We will now assess how OceanaGold's investment narrative could shift as higher grade Wharekirauponga intercepts reshape views on future resource quality.
Compare OceanaGold's Wharekirauponga results with other potential breakouts in the sector by reviewing our curated list of 36 elite gold producer stocks.
OceanaGold Investment Narrative Recap
OceanaGold appeals to investors who want a multi mine producer with meaningful organic growth options rather than a pure steady state producer. That view now leans more heavily on Wharekirauponga, where the new high grade intercepts and extra rigs support the idea that this could meaningfully upgrade resource quality over time. The main near term swing factor remains consistent execution at Haile, Didipio, Macraes and Waihi.
The biggest operational risk is that cost and productivity issues at existing sites offset progress in New Zealand, whether from harder ore, weather, or inflation. The Wharekirauponga update looks positive for future resource conversion but does not remove these execution challenges in the next 12 to 24 months.
The Wharekirauponga drilling update is the announcement that most directly matters for this catalyst discussion. OceanaGold is not just adding ounces on paper. Management is testing whether the southern high grade zone can support a larger, better defined resource that eventually feeds into Mineral Reserves and a future mine plan.
Those intercepts in both the EG Vein and the hanging wall structures, along with five active rigs and the new drill site, increase the operational focus on New Zealand growth. Investors still need to weigh that against the earlier decision to walk away from the Brewer earn in, which keeps capital concentrated on core projects but reduces US exploration optionality.
OceanaGold Assumptions Behind The Wharekirauponga Upside
To understand how Wharekirauponga could reshape OceanaGold over time, it helps to look at what analysts already have baked into their models. The current consensus assumes revenue expands by 12.7% a year for the next three years, with profit margins building from 24.0% today to 34.1% by 2028. That is a meaningful shift in earnings power, even before you layer in any upside from higher grade conversion in New Zealand.
On these projections, analysts expect earnings to reach $764.2 million by 2028, compared with $375.8 million today. That implies just over a doubling of profit, alongside earnings per share of $2.12 if share count trends lower by about 2.08% a year. For readers tracking Wharekirauponga, the key question is whether the emerging high grade southern zone helps make those margin and earnings assumptions feel conservative, aggressive, or broadly in line with what the asset can eventually support.
These assumptions also reset what investors are being asked to accept from the OceanaGold share price today. To hit current price targets, the business would need to trade on a P/E of 6.7x those 2028 earnings, down from 11.6x now and well below the AU Metals and Mining industry at 18.0x. If Wharekirauponga drilling keeps firming up a larger, cohesive high grade resource, some investors may see that future multiple as implying a margin of safety. Others may argue that execution risk at Haile, Didipio, Macraes and Waihi still justifies a discounted earnings multiple even if New Zealand delivers.
Wharekirauponga therefore sits within a wider capital allocation and execution puzzle rather than floating on its own. Extra rigs, denser drilling in the south and a focus on structure are all aimed at turning promising intercepts into something that can back those margin assumptions with hard tonnes. Whether that eventually leads analysts to revisit the discount rate used in their models, or rethink how much value they ascribe to New Zealand compared with the US and Philippines assets, will depend on the quality and consistency of the next waves of drill data.
OceanaGold's narrative projects $2.2b revenue and $764.2 million earnings by 2028. This requires 12.7% yearly revenue growth and an earnings increase of about 2x from $375.8 million today.
Uncover why OceanaGold's fair value indicates a 5% potential upside to its current price before that valuation gap starts to close.
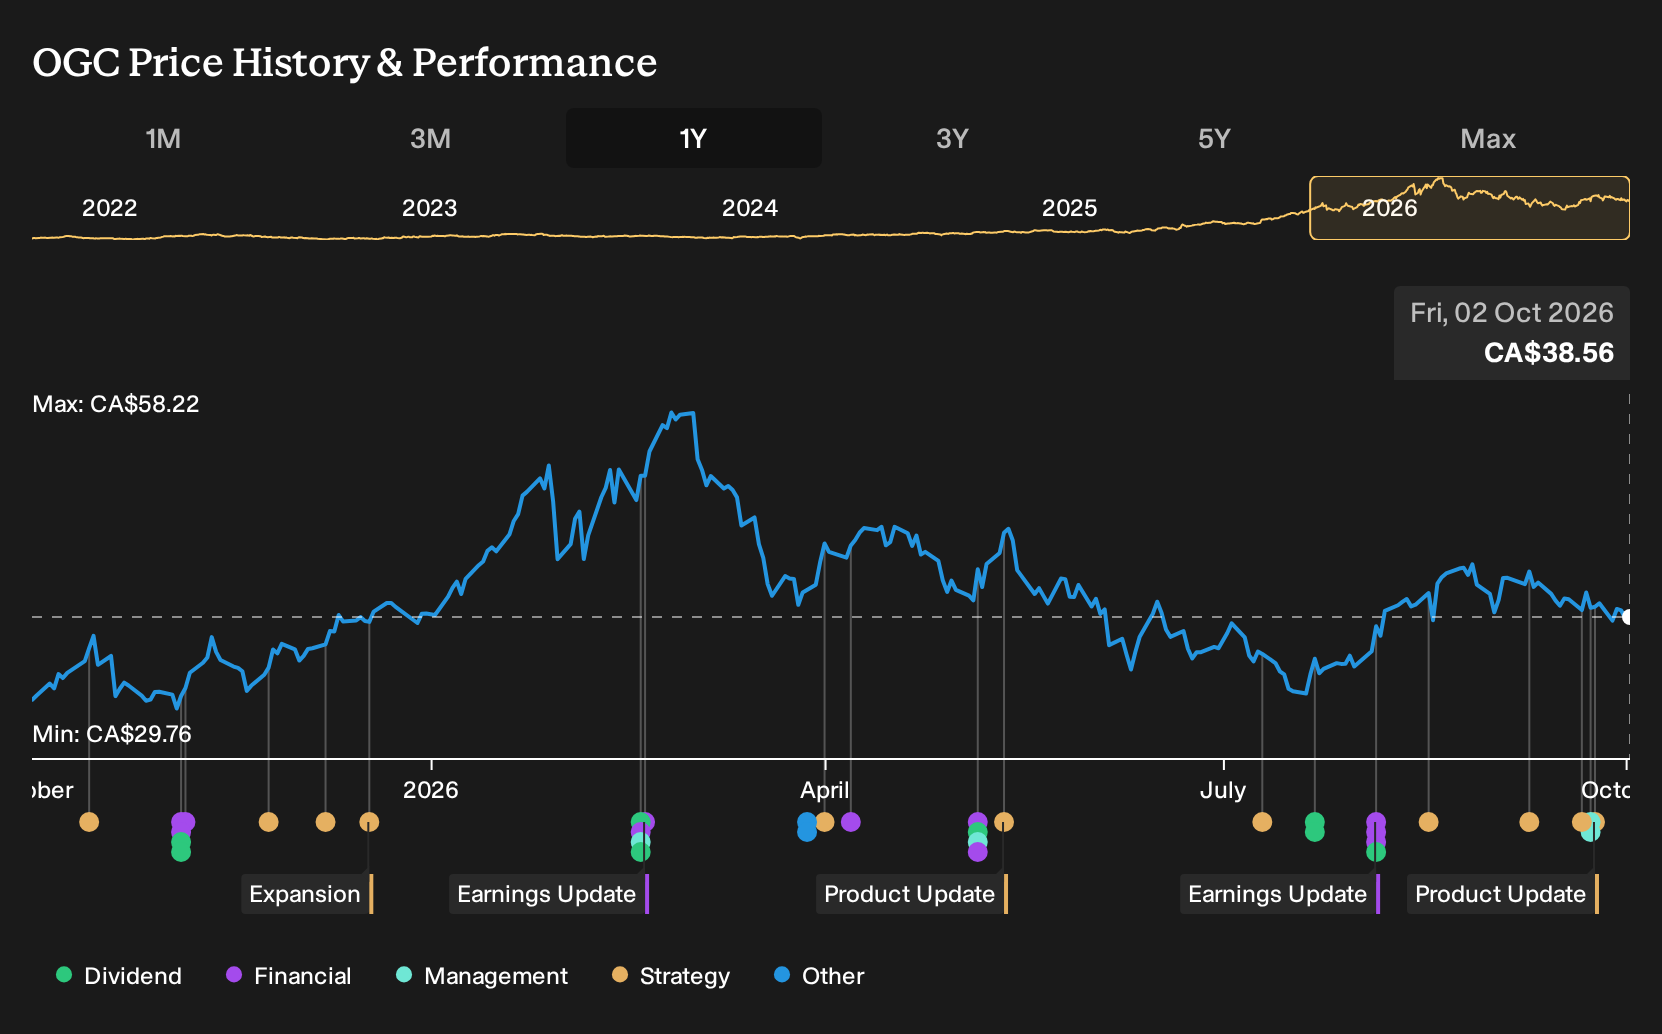
Exploring Other Perspectives
Some of the most optimistic OceanaGold analysts were already banking on fast track permitting at Wharekirauponga, with revenue projections of $2.9b and earnings of $1.3b by 2029 before this drilling update. You can now weigh those upbeat expectations against the new high grade results and decide which narrative feels closer to your own view.
Explore 6 other OceanaGold fair value estimates, including one that suggests there could be as much as 88% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OceanaGold research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for OceanaGold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OceanaGold's overall financial health at a glance.
Looking For More Investment Ideas Beyond OceanaGold?
If the OceanaGold story has sharpened your interest in resource stocks but you want a wider watchlist, the Simply Wall St Screener can help you quickly sort through companies that match very different risk and quality profiles.
- For readers who want small positions in higher risk opportunities, consider scanning a shortlist of 17 elite penny stocks with strong financials that already show stronger balance sheets and fundamentals than the typical microcap.
- If the priority is quality at a reasonable price, filter for businesses trading below intrinsic value by reviewing a focused 6 high quality undervalued stocks that combine solid cash generation with healthier financials.
- For a steadier ride, concentrate on resilience and capital preservation by using the 8 resilient stocks with low risk scores to surface companies with lower risk scores that still stack up on core fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com