
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Are we teetering on the edge of a pattern shift?
Howdy market watchers!
It’s the most fantastic month of the year! Fall and Oktoberfest are all that needs to be said!
Finally, temperatures are beginning to cool with the weather pattern finally shifting to wetter conditions that the Super El Nino forecast has long promised. However, the drought monitor is yet to show much relief after a scorching and incredibly dry August and September takes time to correct.
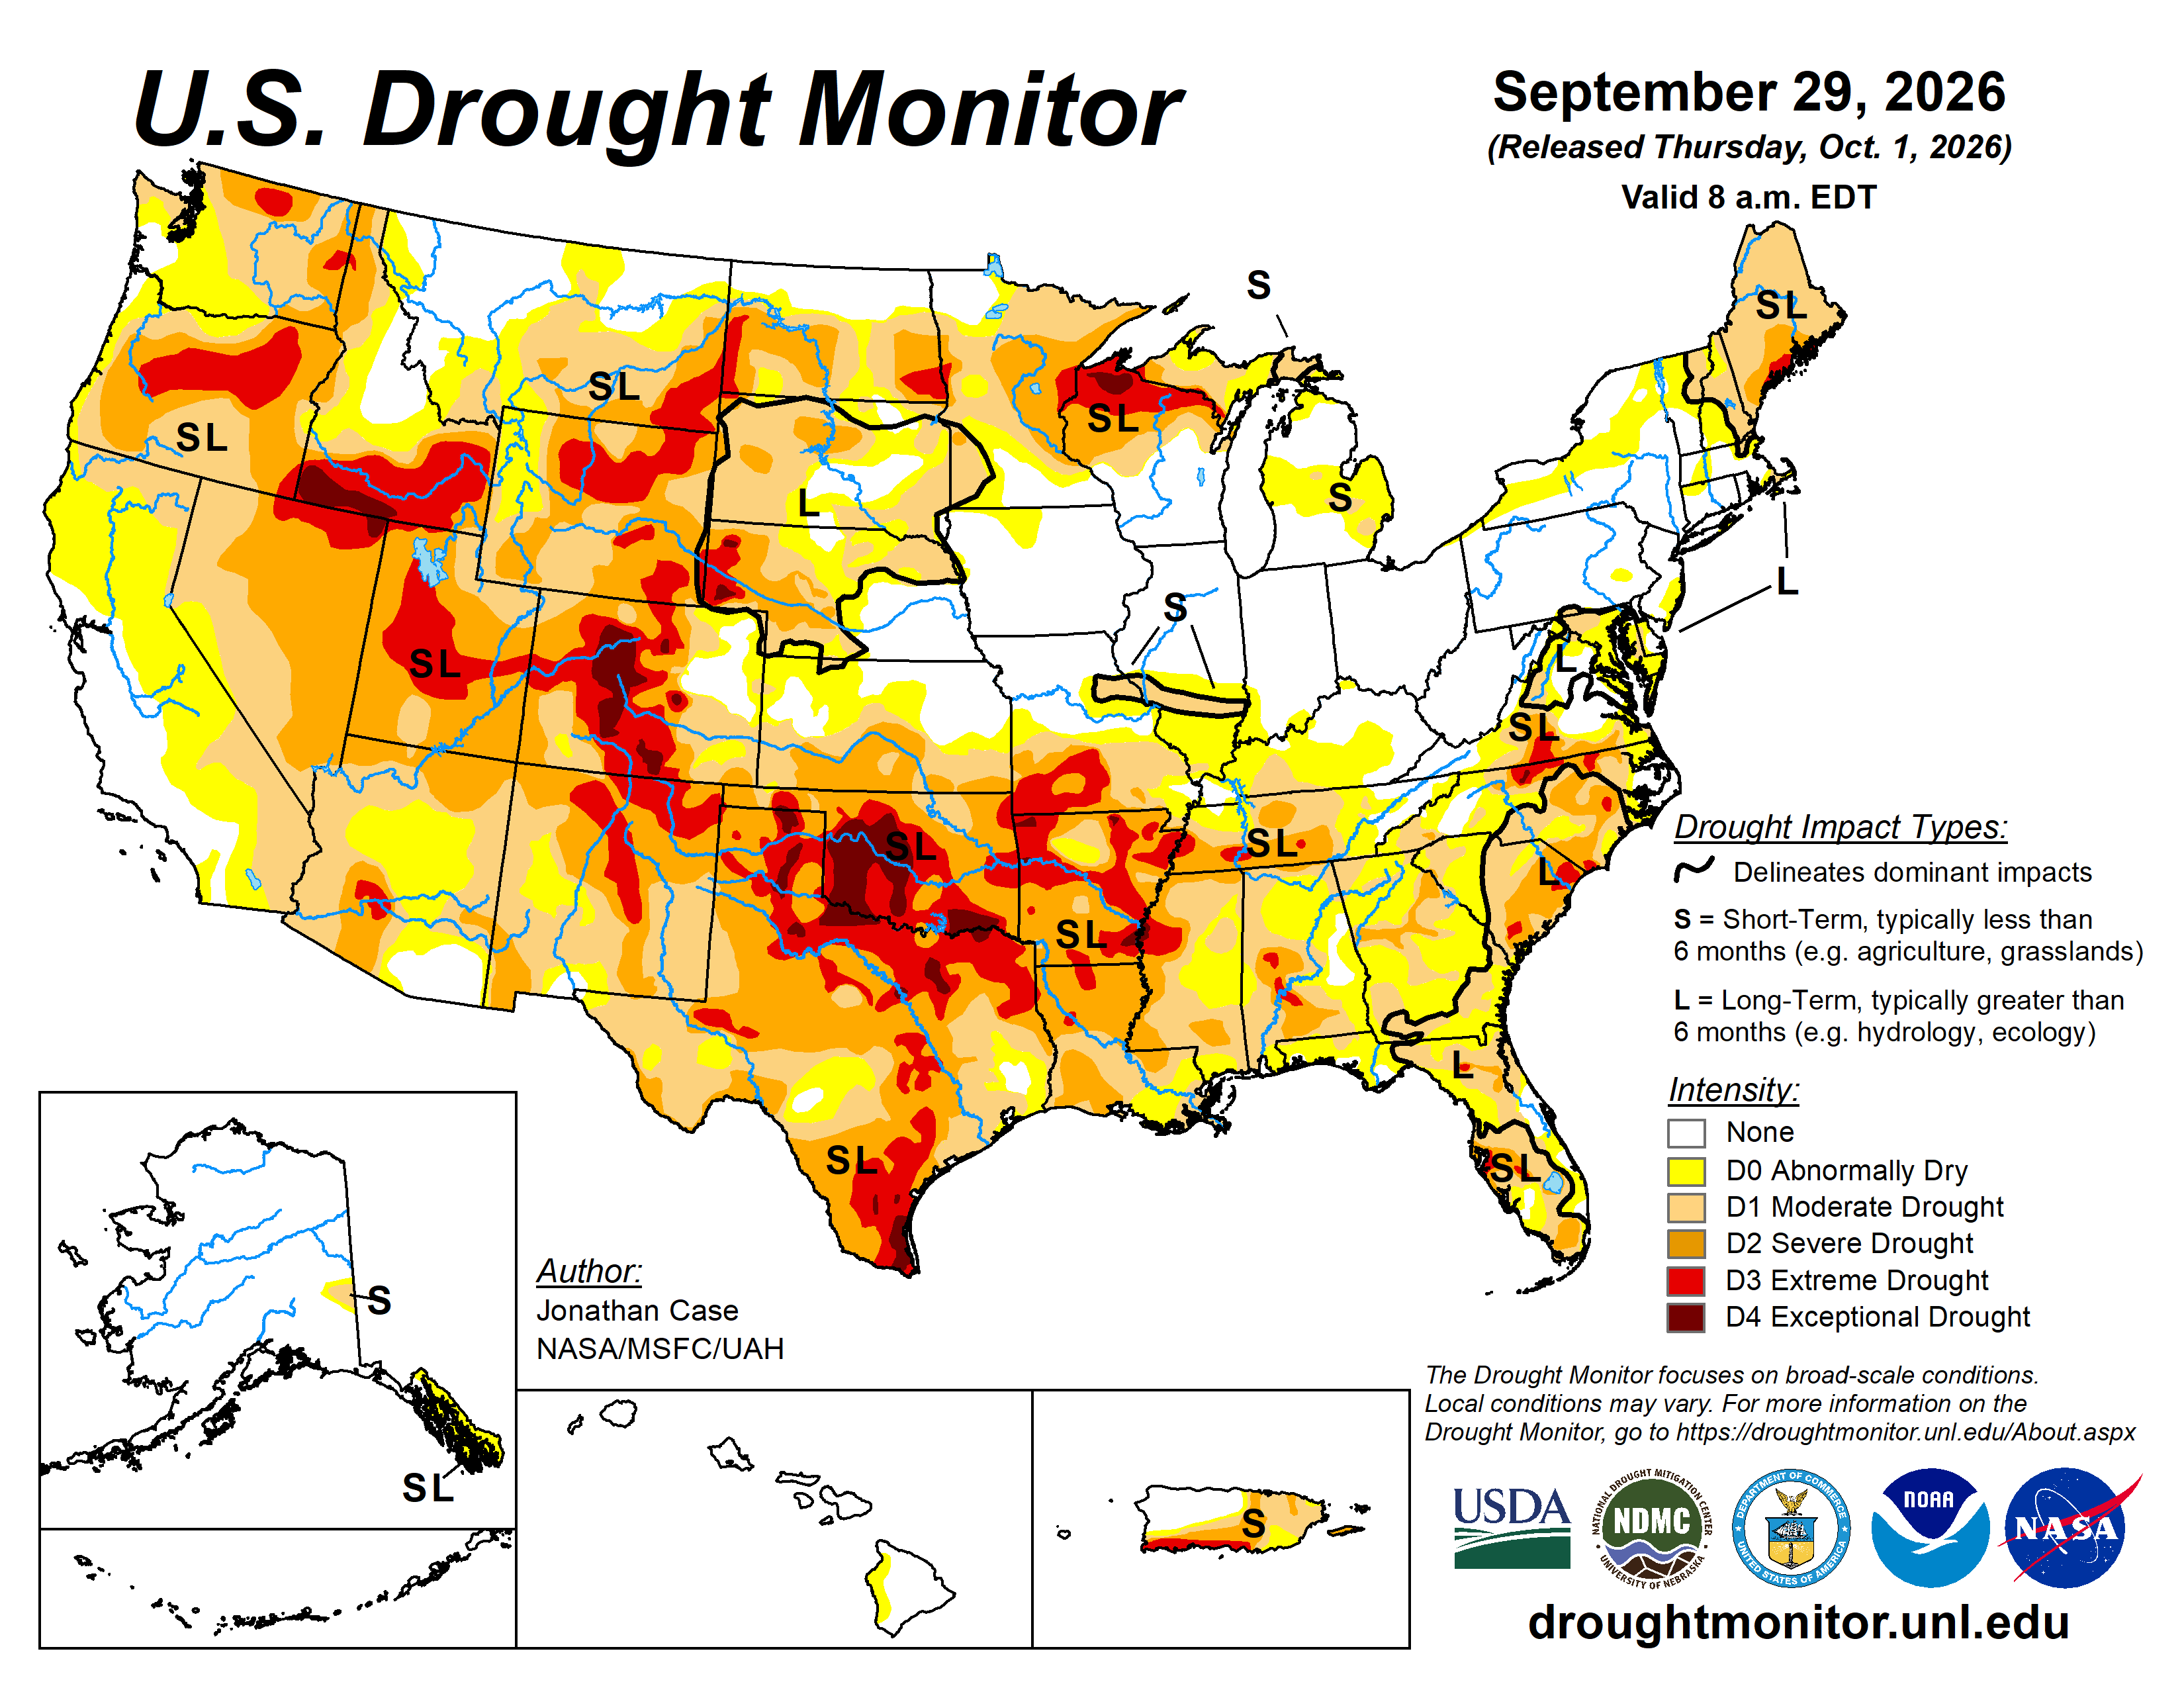
As combines get in the field across the country, we will begin to see just how much damage was done to the crops during that time despite a more favorable finish although now teetering on the edge of excess. When it rains, it pours, they say.
Despite less than favorable harvest conditions, the row crop complex has not yet added premium back in the market after the disappointing follow-up from China’s President Xi to the US in the form of purchases. While tariff concessions set up the terms for further trade and cooperation, we have not yet seen confirmation that activity is picking up.
Wednesday was the end of the month and 3rd quarter, however, and so we could see more news next week as the final quarter of the year has begun and US harvest begins to pick up in earnest, weather permitting.
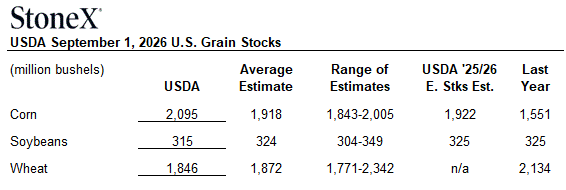
USDA’s September grain stocks reports on Wednesday saw the corn market hit hard, losing over 20 cents on the day, as the agency increased September 1st corn stocks above 2.0 billion bushels while a cut was expected from the prior 1.955 billion bushel estimate. This compares to last year’s 1.551 billion bushels for corn while last year’s production was cut slightly.
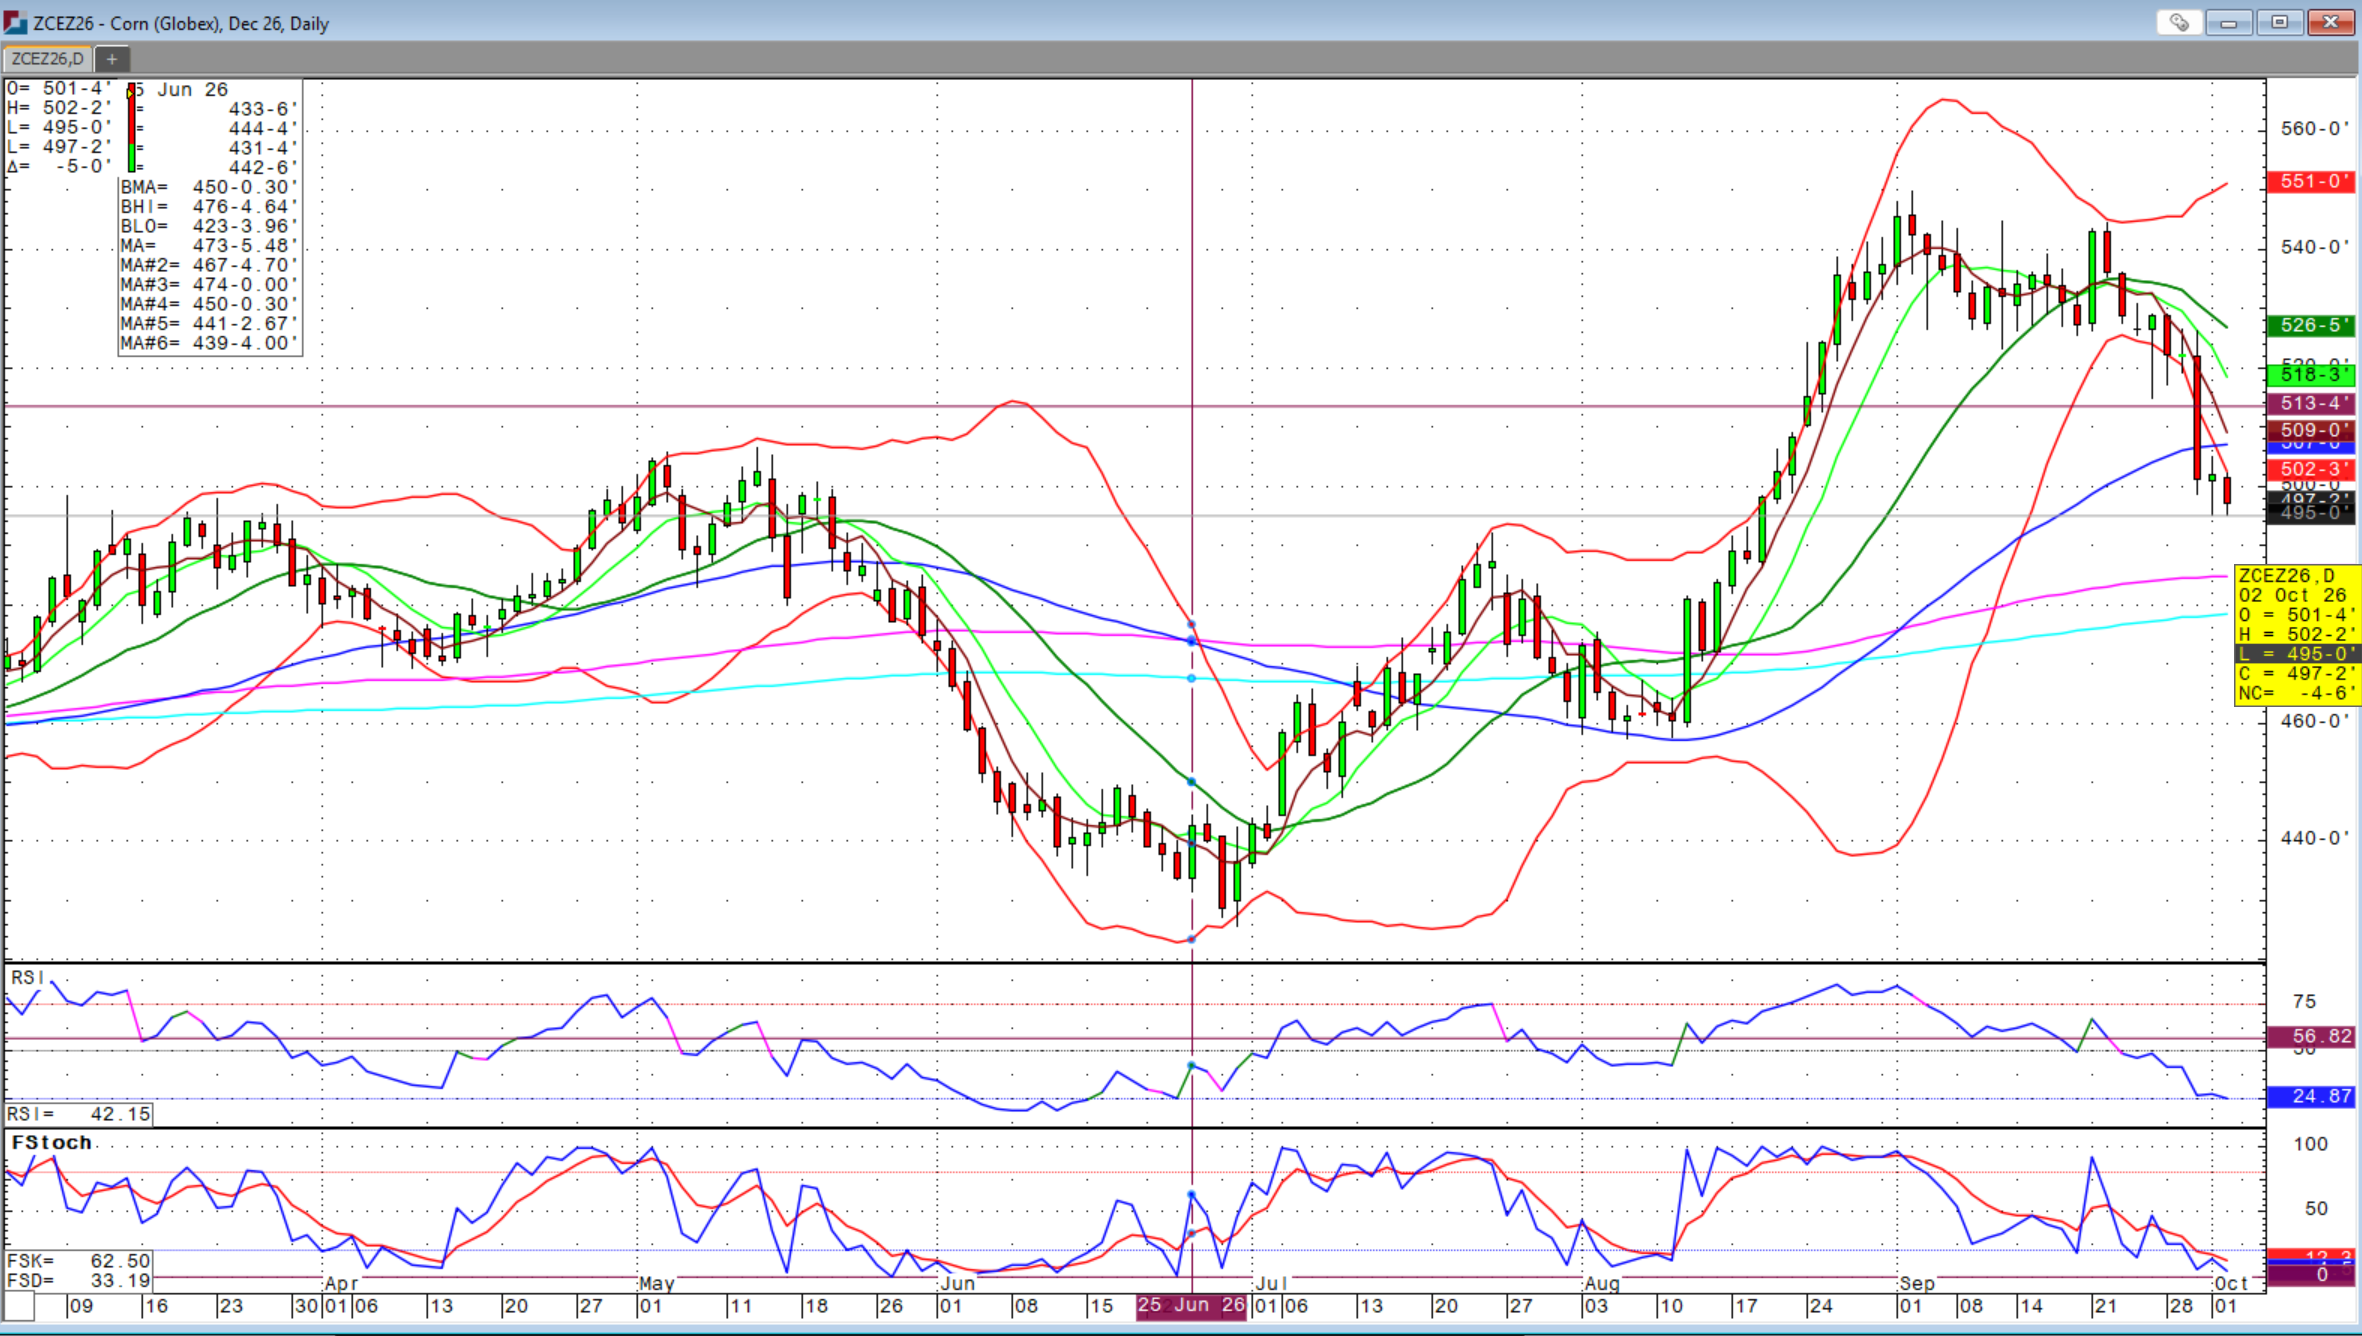
December corn put in an inside day on the chart on Friday, but a lower close under $5.00 for the first time since August 19th.
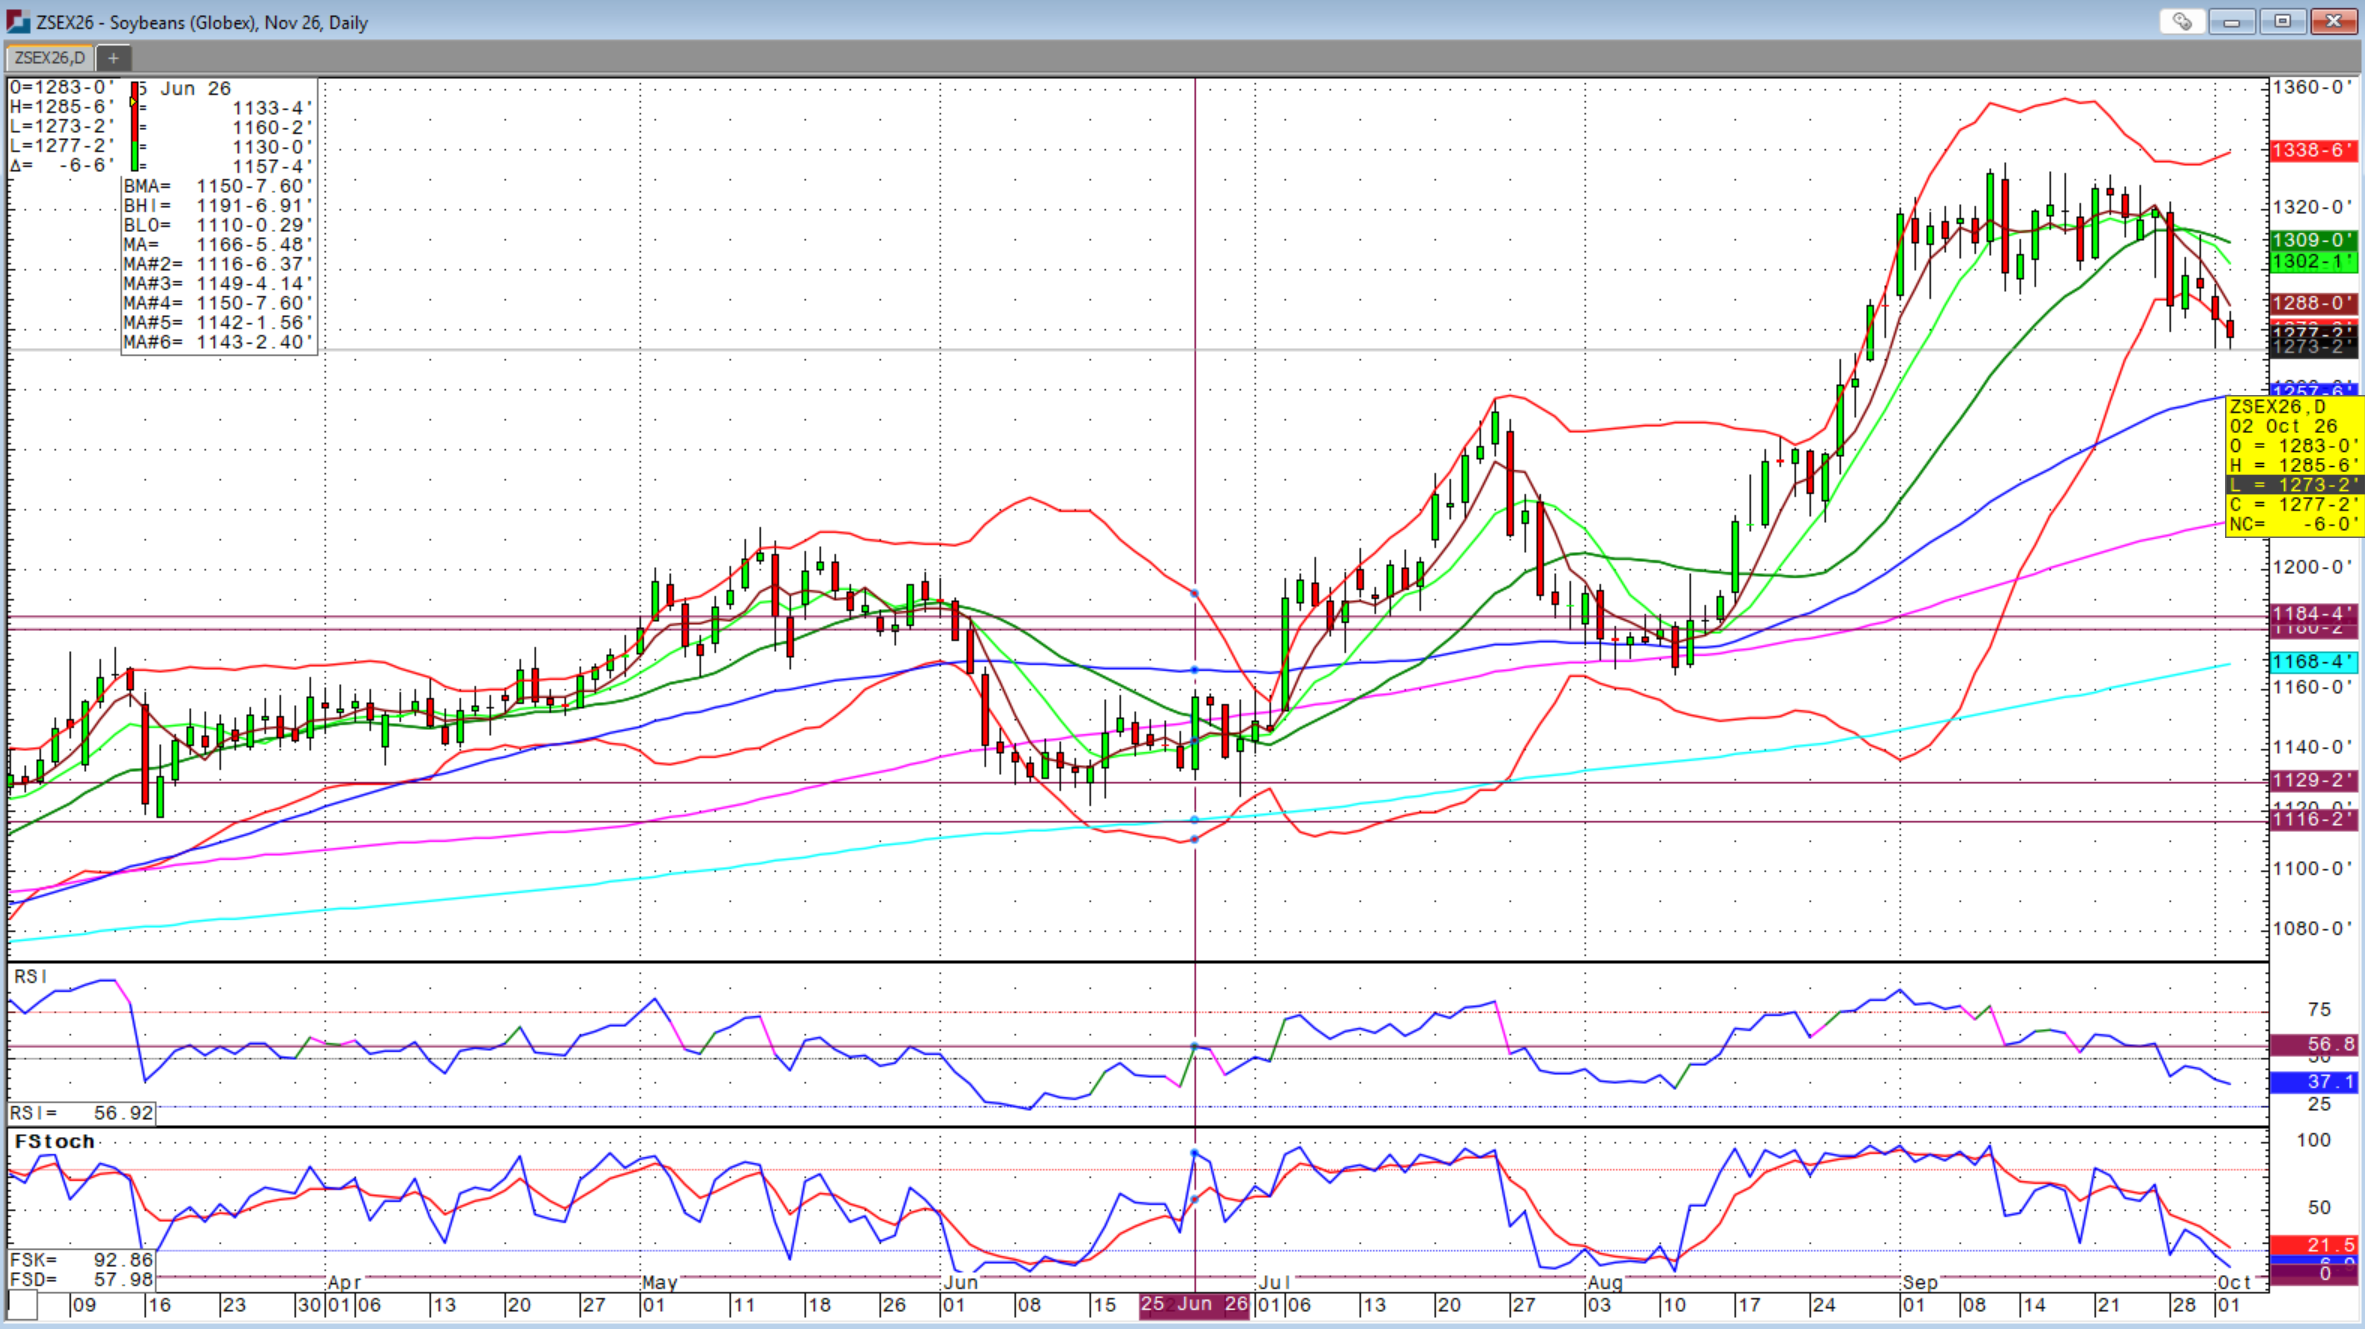
Soybeans have held somewhat better after the initial blow for a lack of new China commitments with the lowest close since August 27th. US soybean stocks were cut by 10.0 million metric tons while a cut of only 1.0 MMT was expected.
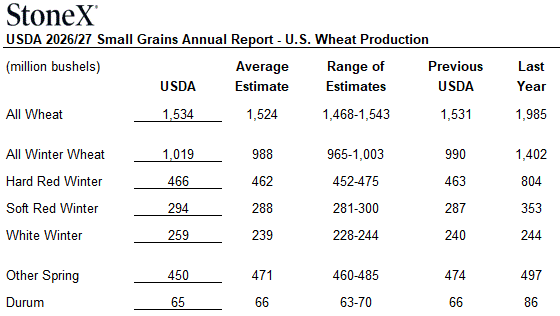
The US wheat stocks number was more bullish than expected with a cut of 26 million bushels more than expected. New crop US wheat production figures were updated with a 10.0-million-bushel increase above expectations, but only 3 million bushels above prior estimates.
For hard red winter wheat traded on the Kansas City wheat futures, there was a 3.0-million-bushel increase above last month although a 1.0-million-bushel decrease was expected. All in all, the stocks number was bullish and supplies are still well below last year due to much lower production this year.
The next trigger could be USDA’s monthly Crop Production and WASDE reports if not geopolitics. The tensions in the Black Sea have somewhat cooled with more ‘dialogue’ among various arbitrators although nothing concrete has surfaced. Russia just bombed the main Kiev bridge again and it seems that we could see a re-escalation soon after the recent United Nations meetings and temporary peace wares off.
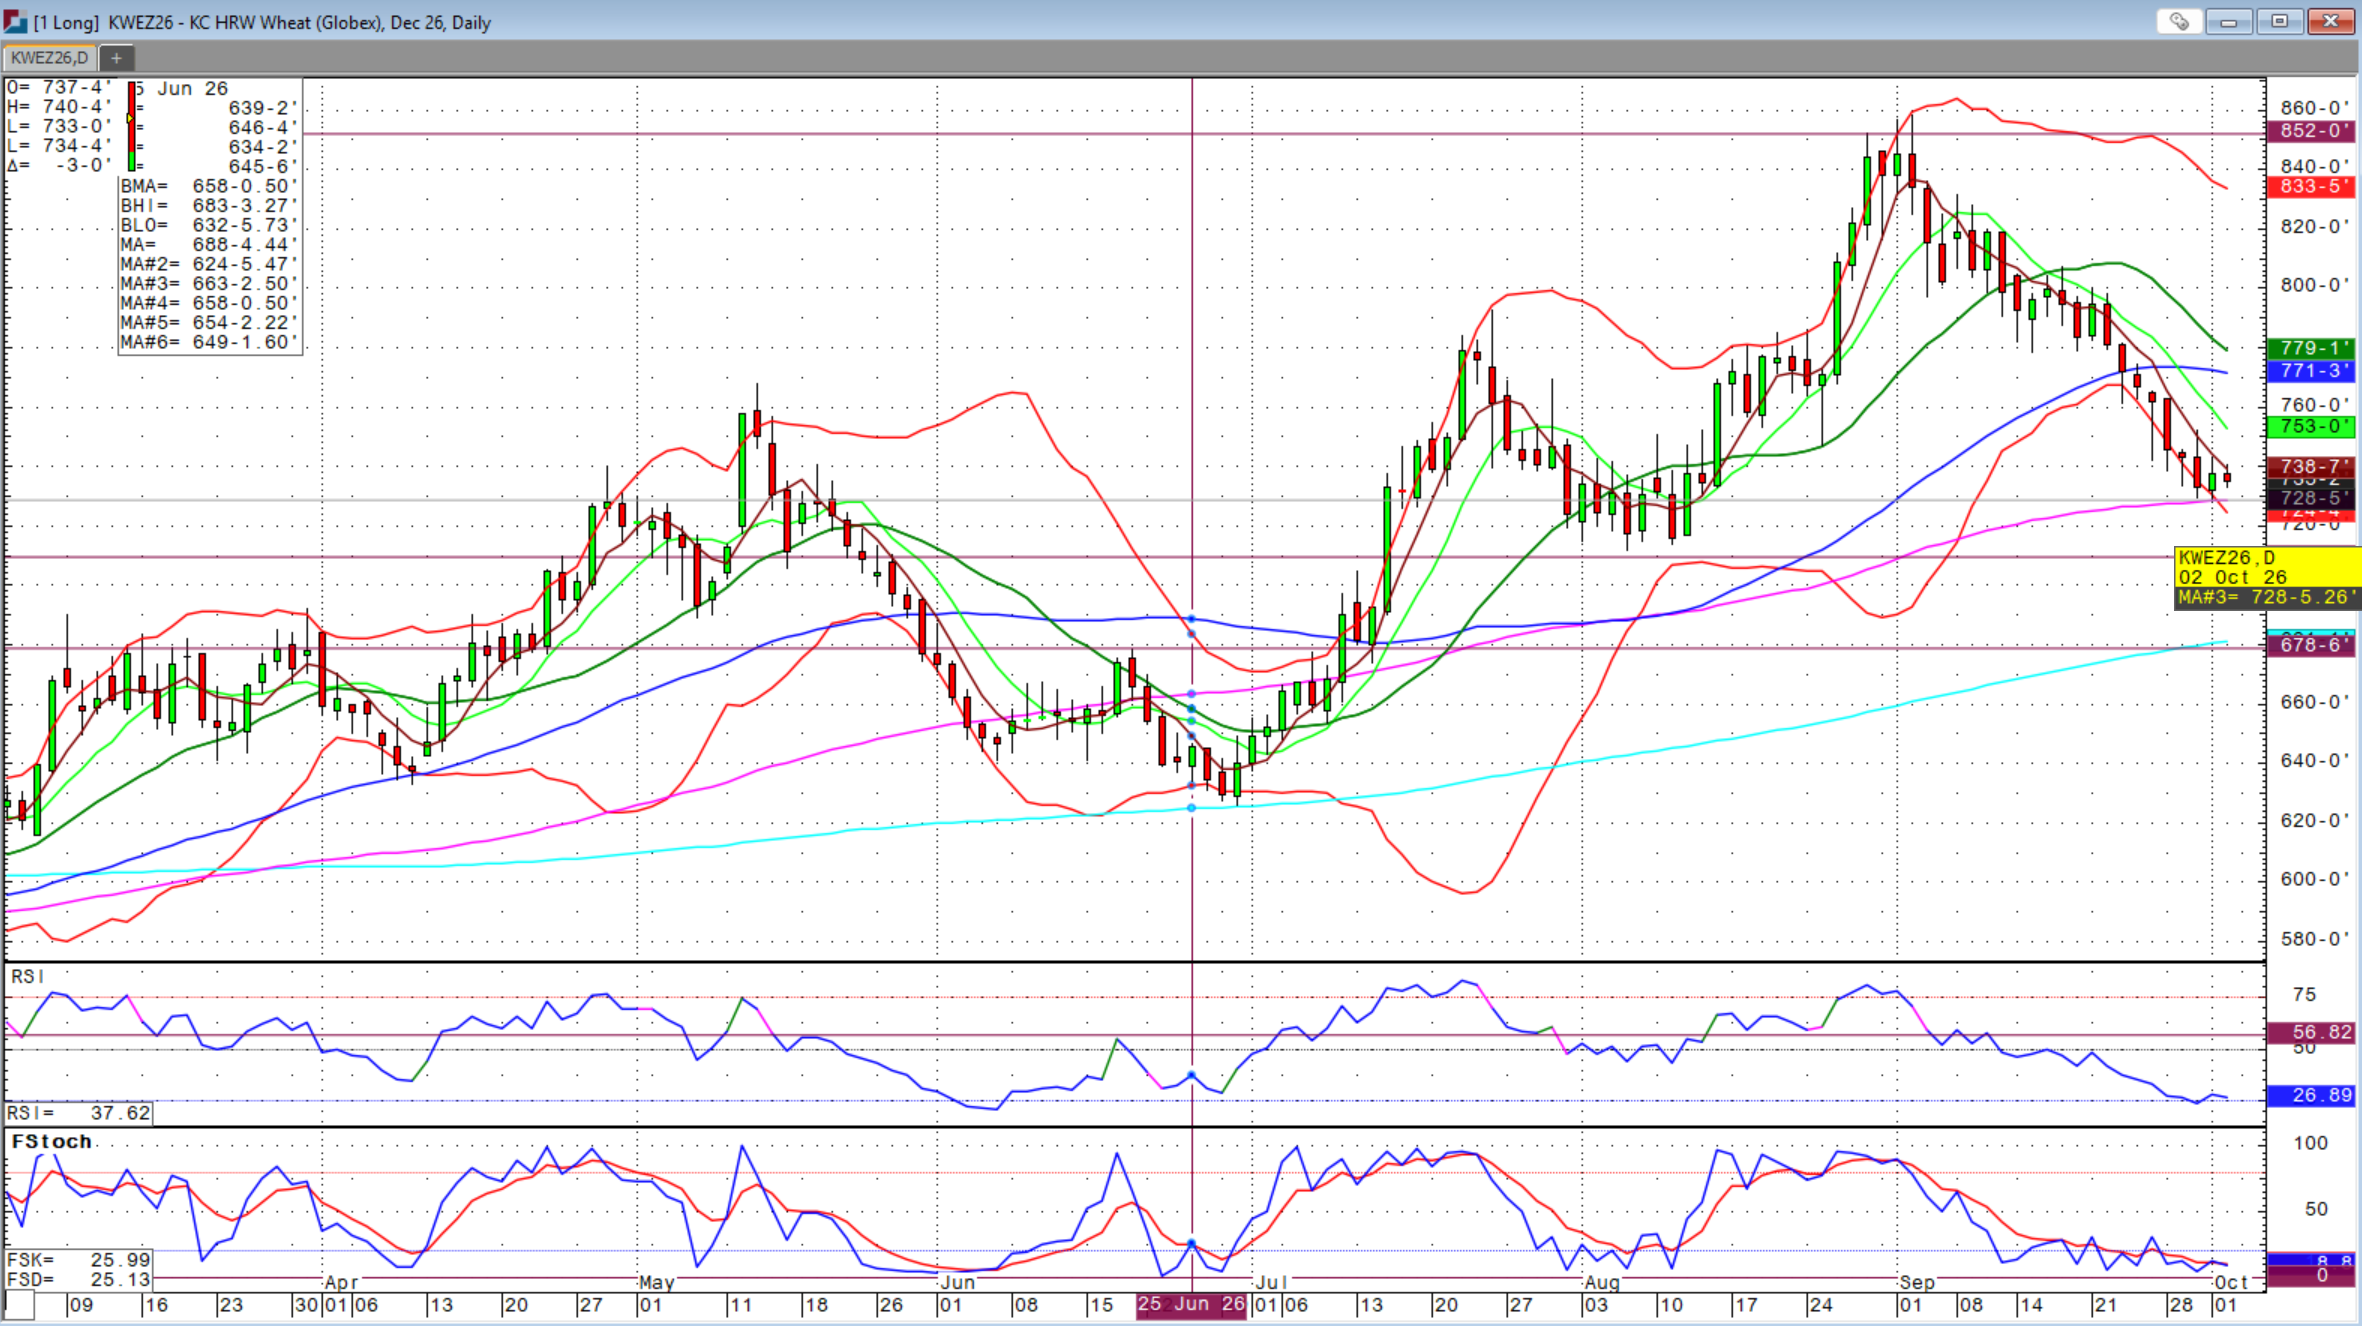
Wheat futures need to hold the 100-day moving averages that we’ve traded down to this week, or we could see another flush lower. However, MATIF wheat futures have put in technical signs of a bottom and Chicago wheat futures made a high above Thursday’s high. Time will tell, but the strong US dollar isn’t helping and we need to see foreign markets begin to buy US origin wheat as Black Sea origin remains disrupted by the ongoing conflict and port closures.
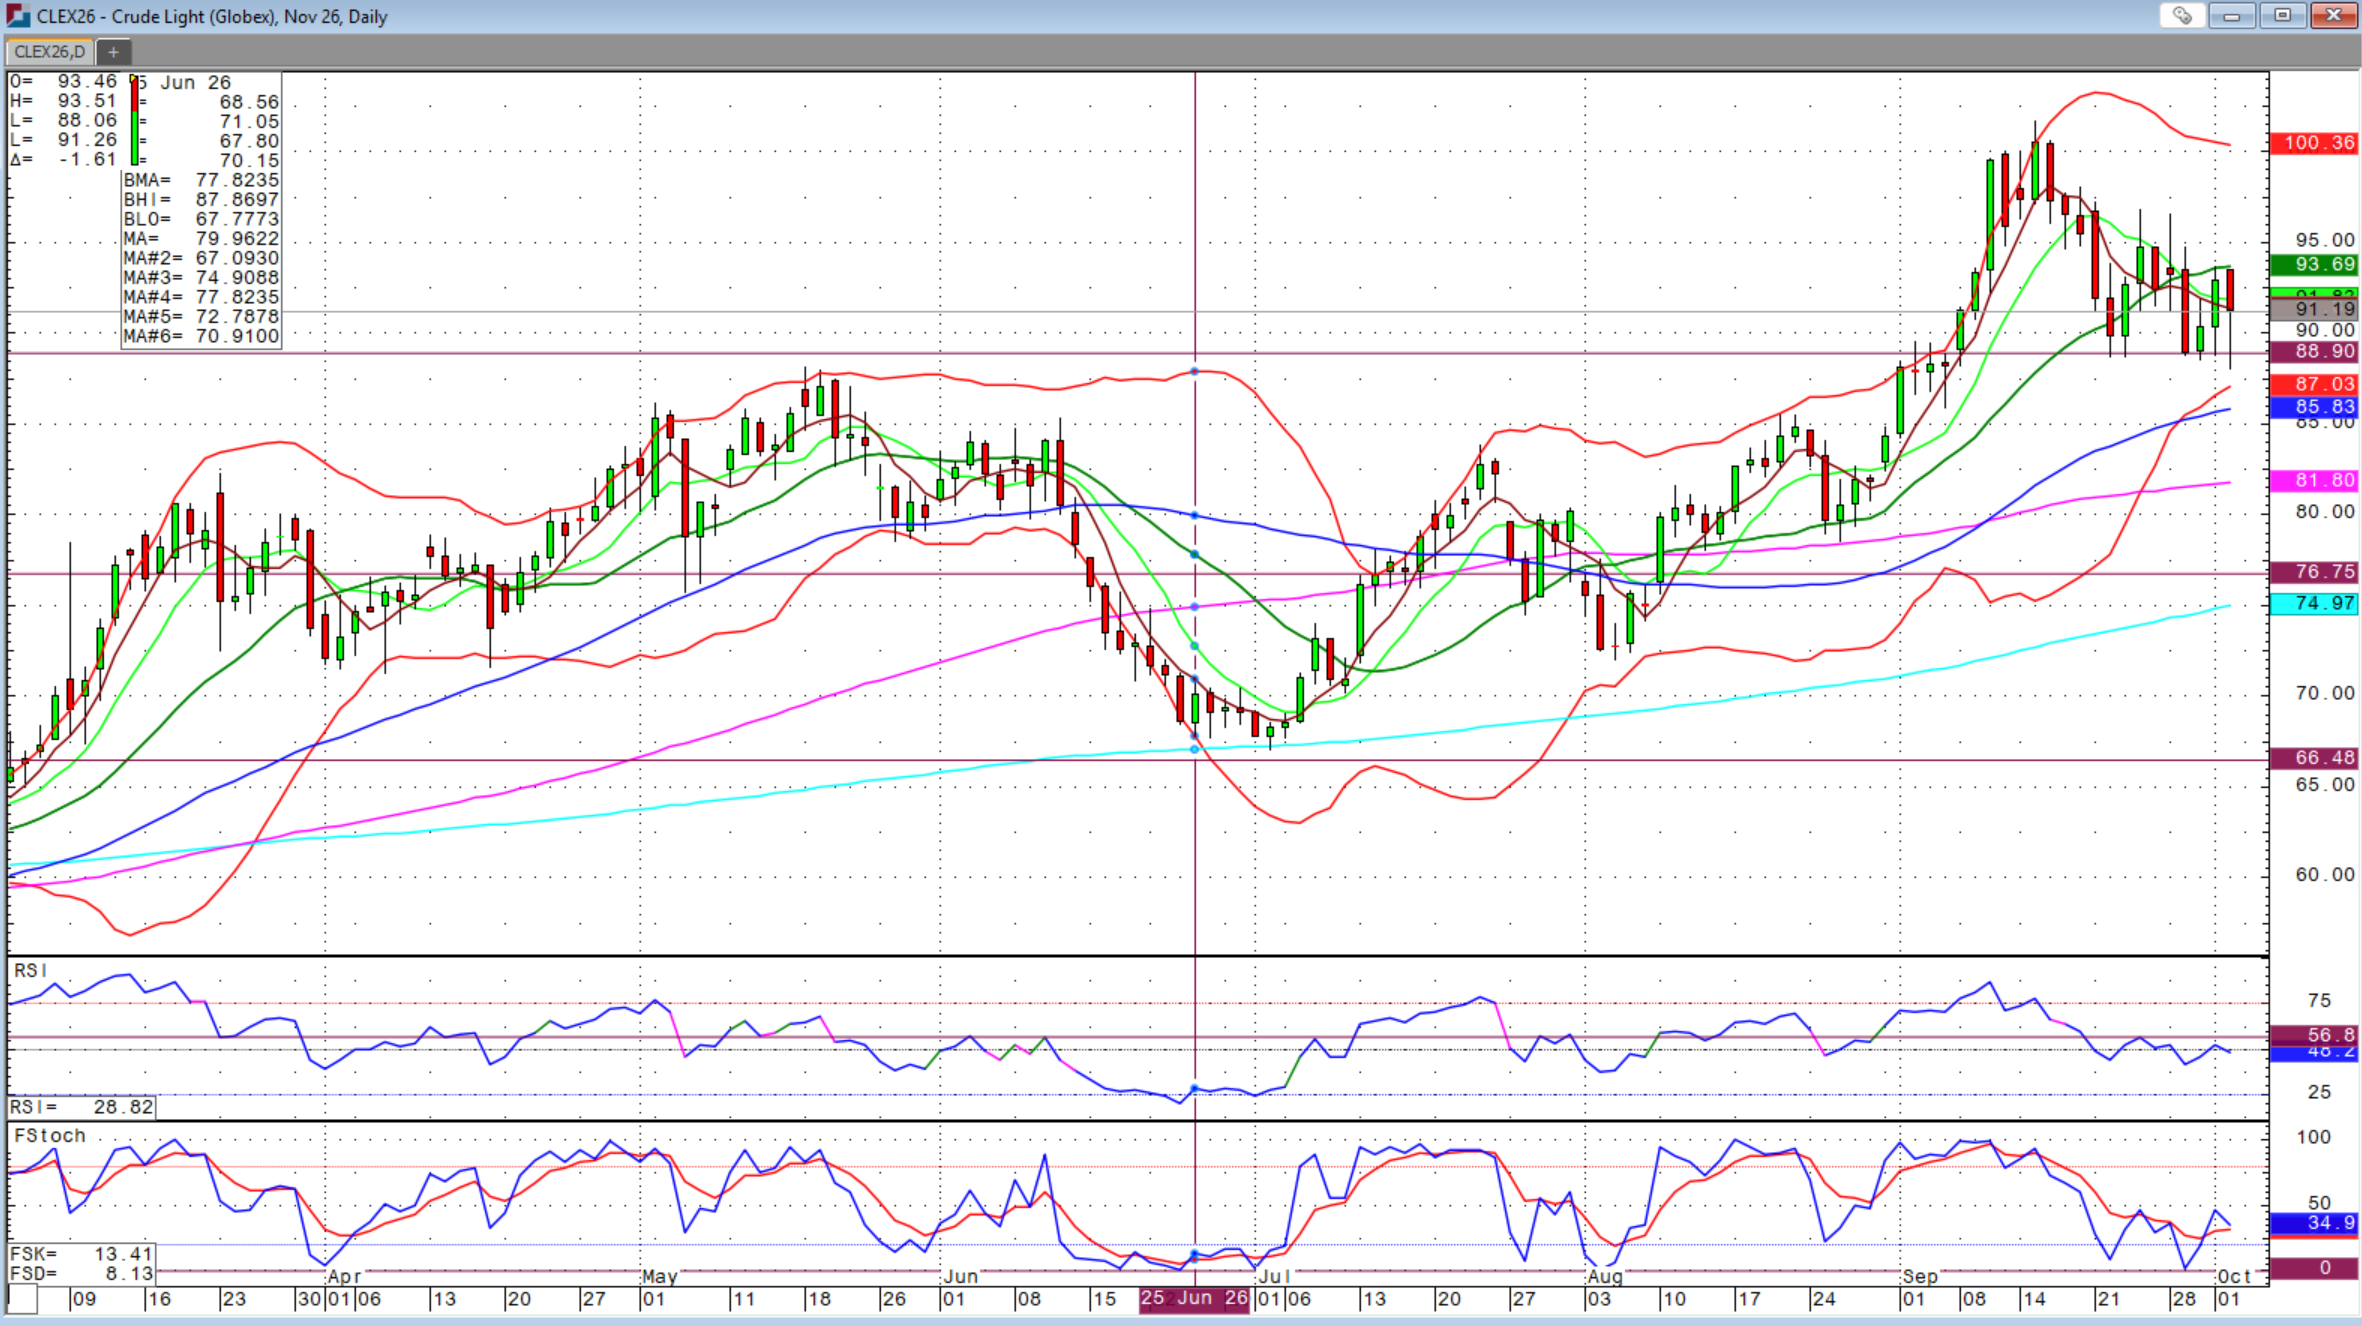
US warships are said to be heading to the Middle East again just as fuel prices reach extremes and add pressure to economies worldwide. Crude oil prices have also sold off on the news, but quickly recovered off the fresh, recent lows put in on Friday with WTI closing back above $91.00 by the end of the session.
As energy and fertilizer prices remain elevated with limited relief on the horizon, politicians and economists are getting nervous at the extent of the pressure being added to all industries around the world that inevitably will get passed on to consumers. Having said that, Friday’s weaker than expected jobs report could put further rate hikes on hold at the next FOMC meeting on October 27-28th.
Nonfarm payrolls increased by only 29,000 jobs in September versus expectations of 84,000 jobs to be added. Unemployment increased to 4.2 percent from 4.1 percent while a steady reading was expected. Also, the August jobs number was revised lower to a gain of 133,000 jobs from 162,000 jobs. US consumer strength has been surprisingly strong over the past several years of increasing costs and tighter financial conditions. In fact, it has confounded many economists at just how resilient the US consumer has been as headwinds have risen.
The all-important holiday spending period is ahead for retailers and we will see how consumer spending progresses as uncertainty increases ahead of the election and the increasing cost of living continues. The strength of consumer spending has benefited the cattle market more than any other sector and it also continues. While market volatility continues whipping, the overall supply and demand fundamentals in the beef market remain strongly intact.
President Trump is beginning to realize just how difficult it is to increase supply in a meaningful way in the short term of an industry that takes years to rebuild while demand rationing has really not occurred much despite higher prices. US consumers want beef even at higher prices. That is the saving grace to incentivize herd rebuilding although the continued political news cycle of surprise announcements damages the ability of cattlemen to operate at a profit.
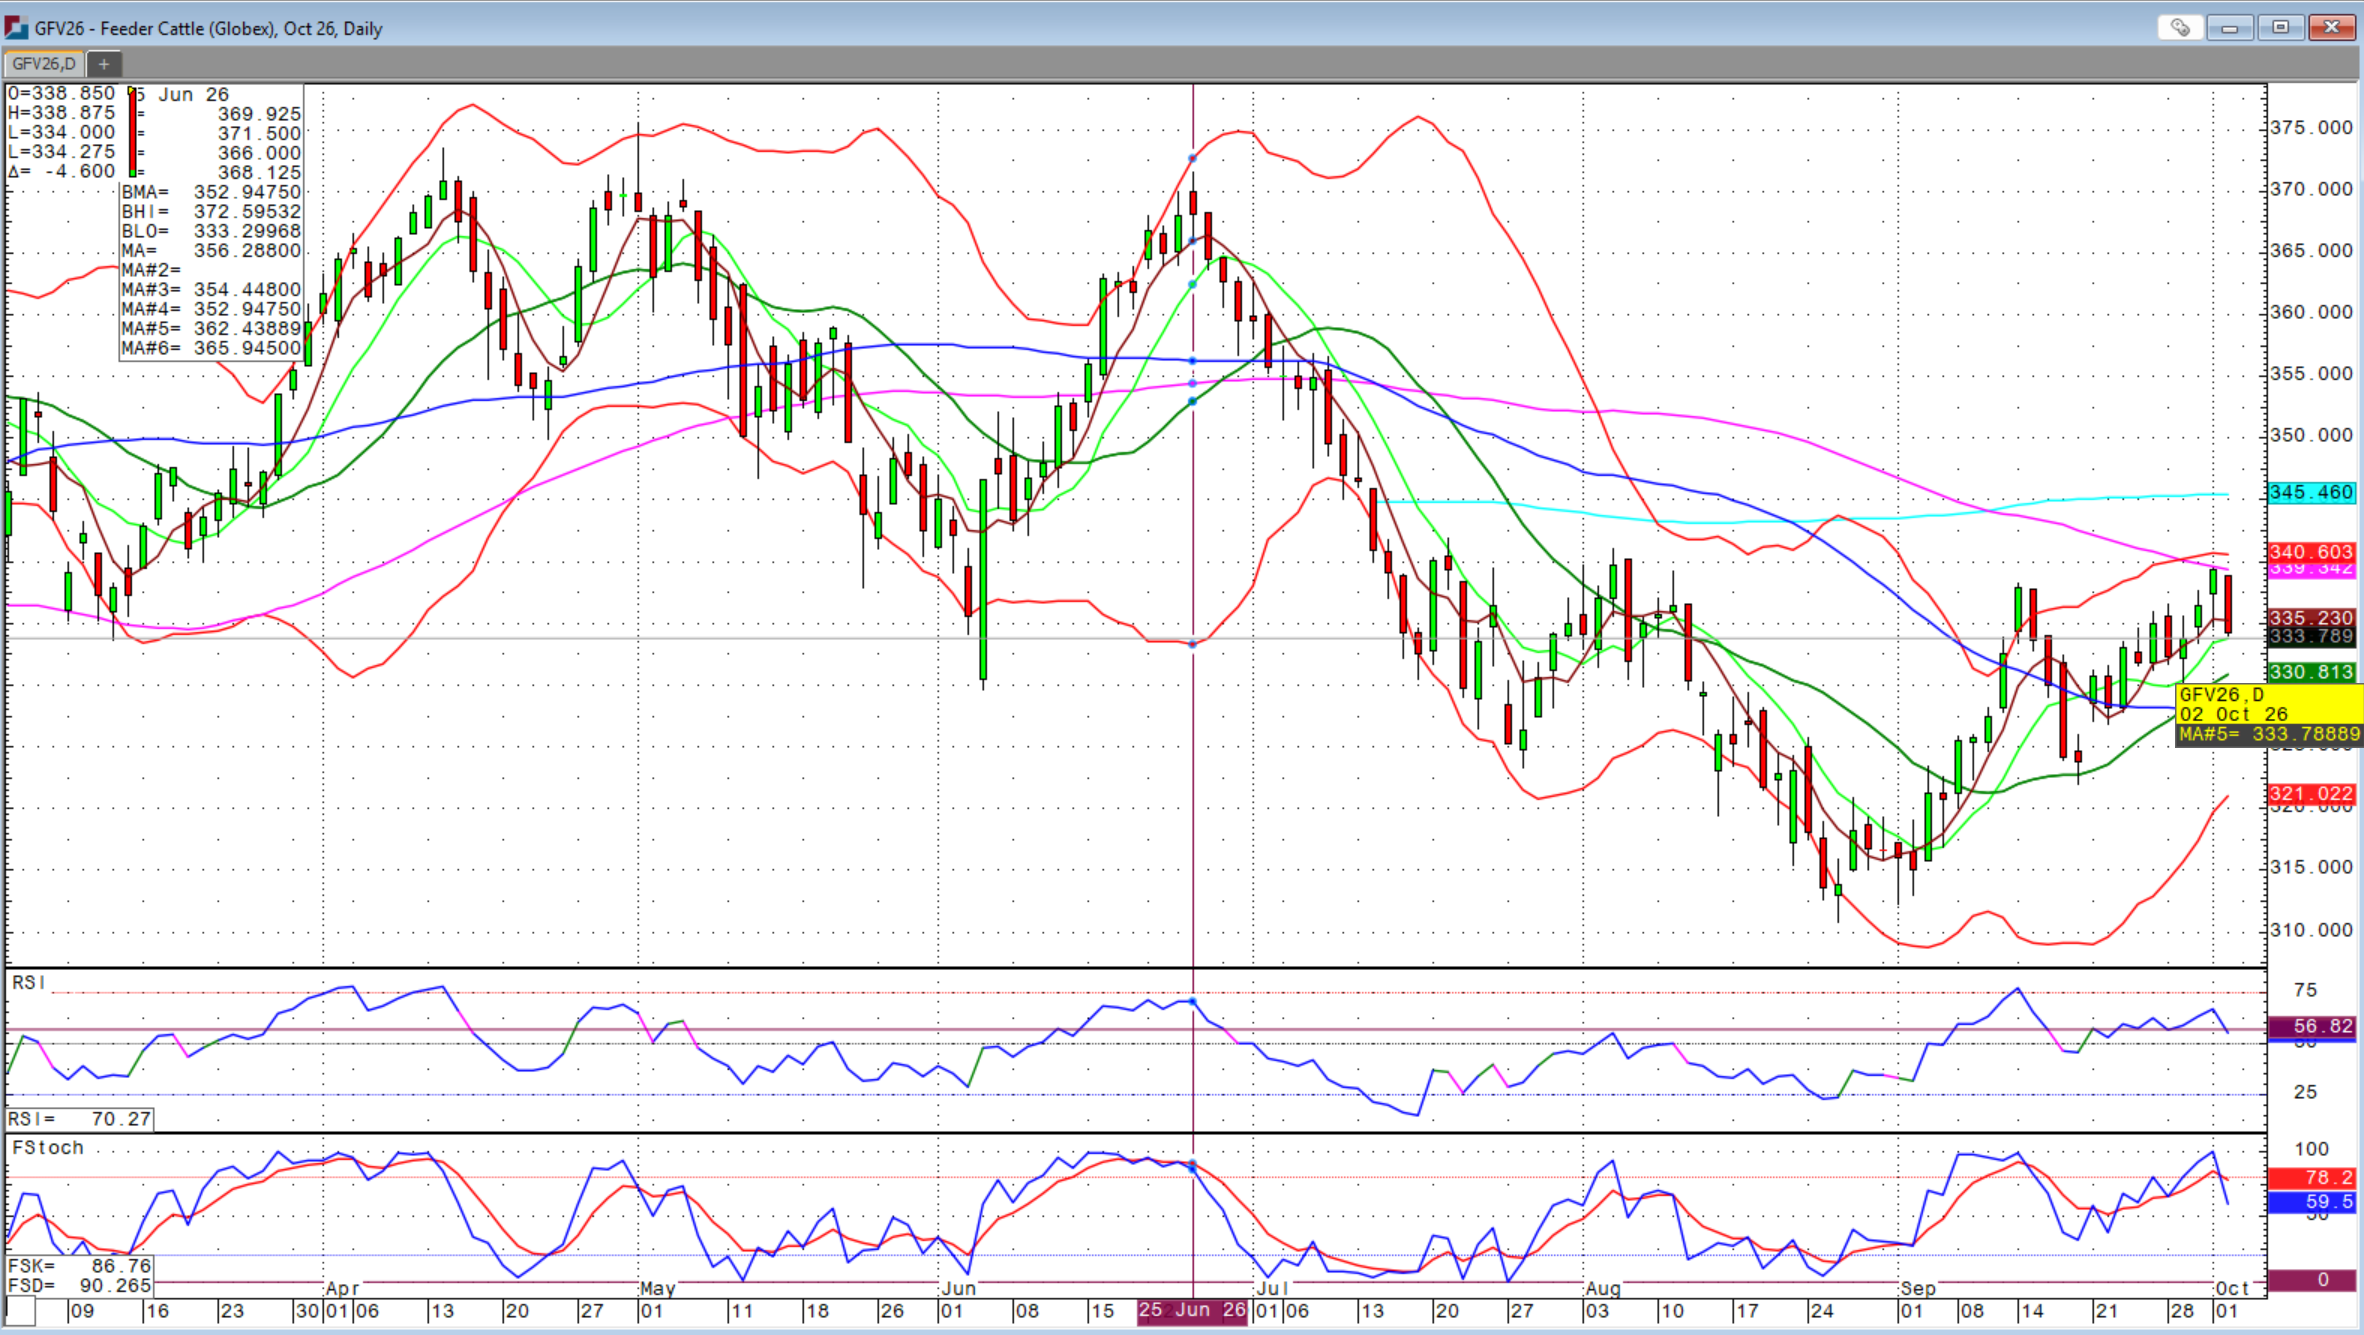
We have rallied $33 per cwt off the lows August 26th to the highs from this Thursday. We saw some profit taking to finish the week, but it could be merely that with the close right down at the 9-day moving average. Should we keep the closes above the 9-day moving average, I think there is still potential to go another $9-10 per cwt higher from Friday’s closes, which would put us up at the 200-day moving average. This week’s highs traded above the former highs of mid-September and so the charts are looking friendlier by the day. If you’re buying cattle here for winter wheat pasture, it is always prudent to protect them along the way and on rallies.
Just remember, you don’t have to do everything at once when it is also difficult to wait for the “right price” to protect them all. Risk protection doesn’t have to be all or nothing. Add protection in increments on major rallies if that’s your bias. As the market has just shown again, major selloffs can happen in bullish markets and you don’t want to get caught waiting on any and all protection on that price that may never come.
Call or come by and let’s discuss a risk management strategy that works for you and let Sidwell Strategies be your guide to incrementally protect your profit margin.
Sidwell Strategies is the one-stop shop to protect cattle with futures, puts, LRP or a combination of all, which is probably the best strategy overall. If you’re ready to trade commodity markets, give me a call at (580) 232-2272 or stop by my office to get your account set up and discuss risk management and marketing solutions to pursue your objectives. Self-trading accounts are also available. It is never too late to start and there is no operation too small to get a risk management and marketing plan in place.
Wishing everyone a successful trading week! Let us know if you'd like to join our daily market price and commentary text messages to stay informed!
Brady Sidwell is a Series 3 Licensed Commodity Futures Broker and Principal of Sidwell Strategies. Open your Trading Account with Sidwell Strategies at https://portal.stonex.com/prefill/index/BradySidwellU52F112P. Contact us at (580) 232-2272 or at trade@sidwellstrategies.com.
Futures and Options trading involves the risk of loss and may not be suitable for all investors. Review full disclaimer at https://www.sidwellstrategies.com/fccp-disclaimer-21951.