
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is CFO Change Altering The Investment Case For CNX Resources Stock (CNX)?
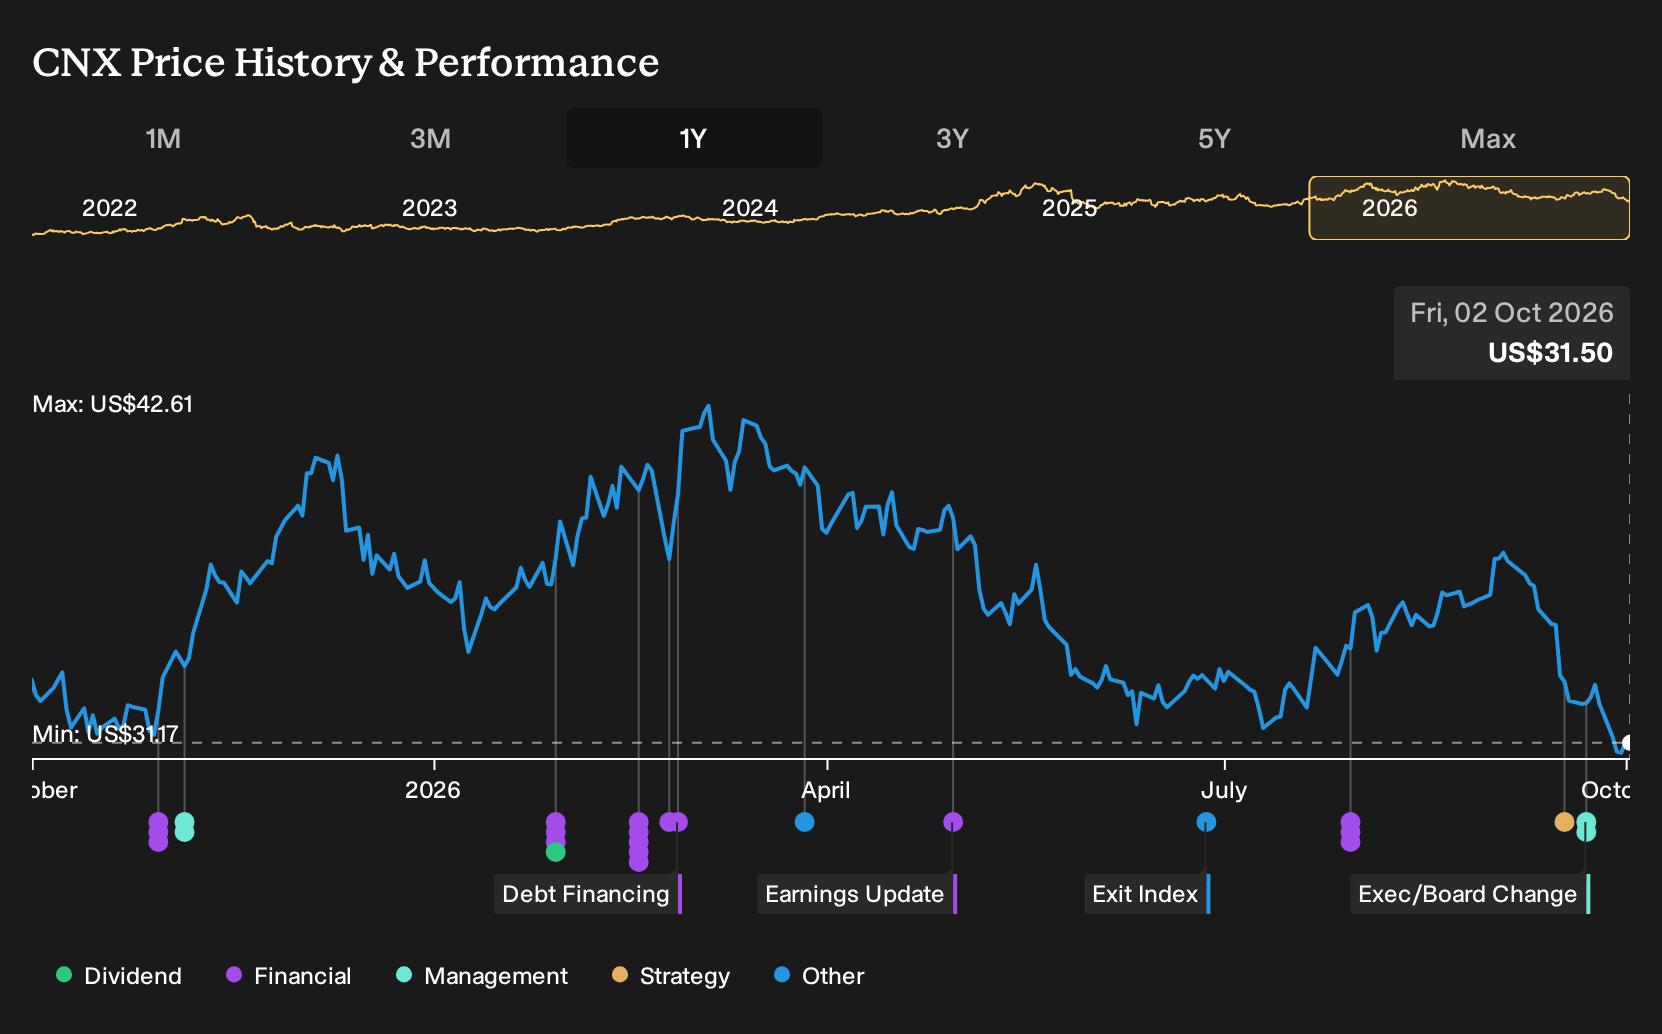
- CNX Resources reported that long-time executive Ravi Srivastava became Chief Financial Officer and principal financial officer in September 2026, while Melissa Long took on the principal accounting officer role and former CFO Everett Good shifted to a short term consulting position.
- The shift places an engineer and data focused operator at the financial helm of CNX Resources, which could influence how the business balances drilling efficiency, technology investments, and capital allocation decisions over time.
- We will now look at how CNX Resources' investment narrative could be influenced by Ravi Srivastava moving into the CFO role.
CNX Resources Investment Narrative Recap
To own CNX Resources, you need to believe the gas producer can keep extracting value from its Appalachian footprint while managing a one rig program, intermittent production lulls, and exposure to evolving tax credit and environmental attribute markets. The short term swing factor remains how efficiently operations convert drilling and gathering activity into cash while demand from power, data centers, and industrial users develops.
The biggest risk still sits around earnings and revenue forecasts that point to declines over the next few years, combined with a high debt load and reliance on higher risk funding. The CFO change itself does not materially alter those near term catalysts or risks, but it does put execution more squarely under scrutiny.
The most relevant announcement is the appointment of Ravi Srivastava as CFO and principal financial officer, with former CFO Everett Good supporting the transition in a consulting role through the end of 2026. Srivastava arrives with a deep operations and technology background across drilling, production, and data science inside CNX Resources.
For investors, that matters most if CNX Resources focuses more on efficiency, cost control, and monetization of environmental attributes while managing forecast earnings declines. The combination of an engineer CFO and a long tenured accounting lead in Melissa Long could influence how rigorously the firm prioritizes Utica results, capital discipline, and regulatory dependent revenue streams against its existing debt profile.
CNX Resources' narrative points to US$2.3 billion in revenue and US$499.8 million in earnings by 2029. This aligns with analyst assumptions of 1.3% yearly revenue growth and an earnings decline of about US$700 million from US$1.2 billion today.
Uncover why CNX Resources' fair value indicates a 19% potential upside to its current price before the discount closes.
Exploring Other Perspectives
Some of the most optimistic analysts framed the real catalyst around CNX Resources ramping low carbon monetization, not just gas volumes, with forecasts before this CFO news that still had earnings sliding from about US$949.4 million to US$478.7 million by 2029 on roughly US$2.3 billion of revenue. You can treat Srivastava’s appointment as a fresh signal to recheck those assumptions and compare different viewpoints before deciding what you think the story looks like from here.
Explore 2 other CNX Resources fair value estimates, including one that suggests as much as 291% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CNX Resources research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CNX Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CNX Resources' overall financial health at a glance.
Looking For More CNX Resources Style Ideas?
If the CNX Resources story has you thinking about other opportunities where execution, balance sheet strength, and cash generation really matter, the Simply Wall St Screener can help you line up comparable candidates quickly.
- If you want sturdier balance sheets to compare against CNX Resources, start with a list of solid balance sheet and fundamentals (26 results) that can better withstand swings in cash flow.
- If your focus is on mispriced quality, line up potential bargains with a 31 high quality undervalued stocks that share a mix of fundamentals and pricing that looks interesting on paper.
- If resilience matters more than excitement, narrow your watchlist to a 31 resilient stocks with low risk scores that may offer a smoother ride through future cycles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com