
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Werner Enterprises Investors Had To Stomach, And Where It’s Playing Out Again
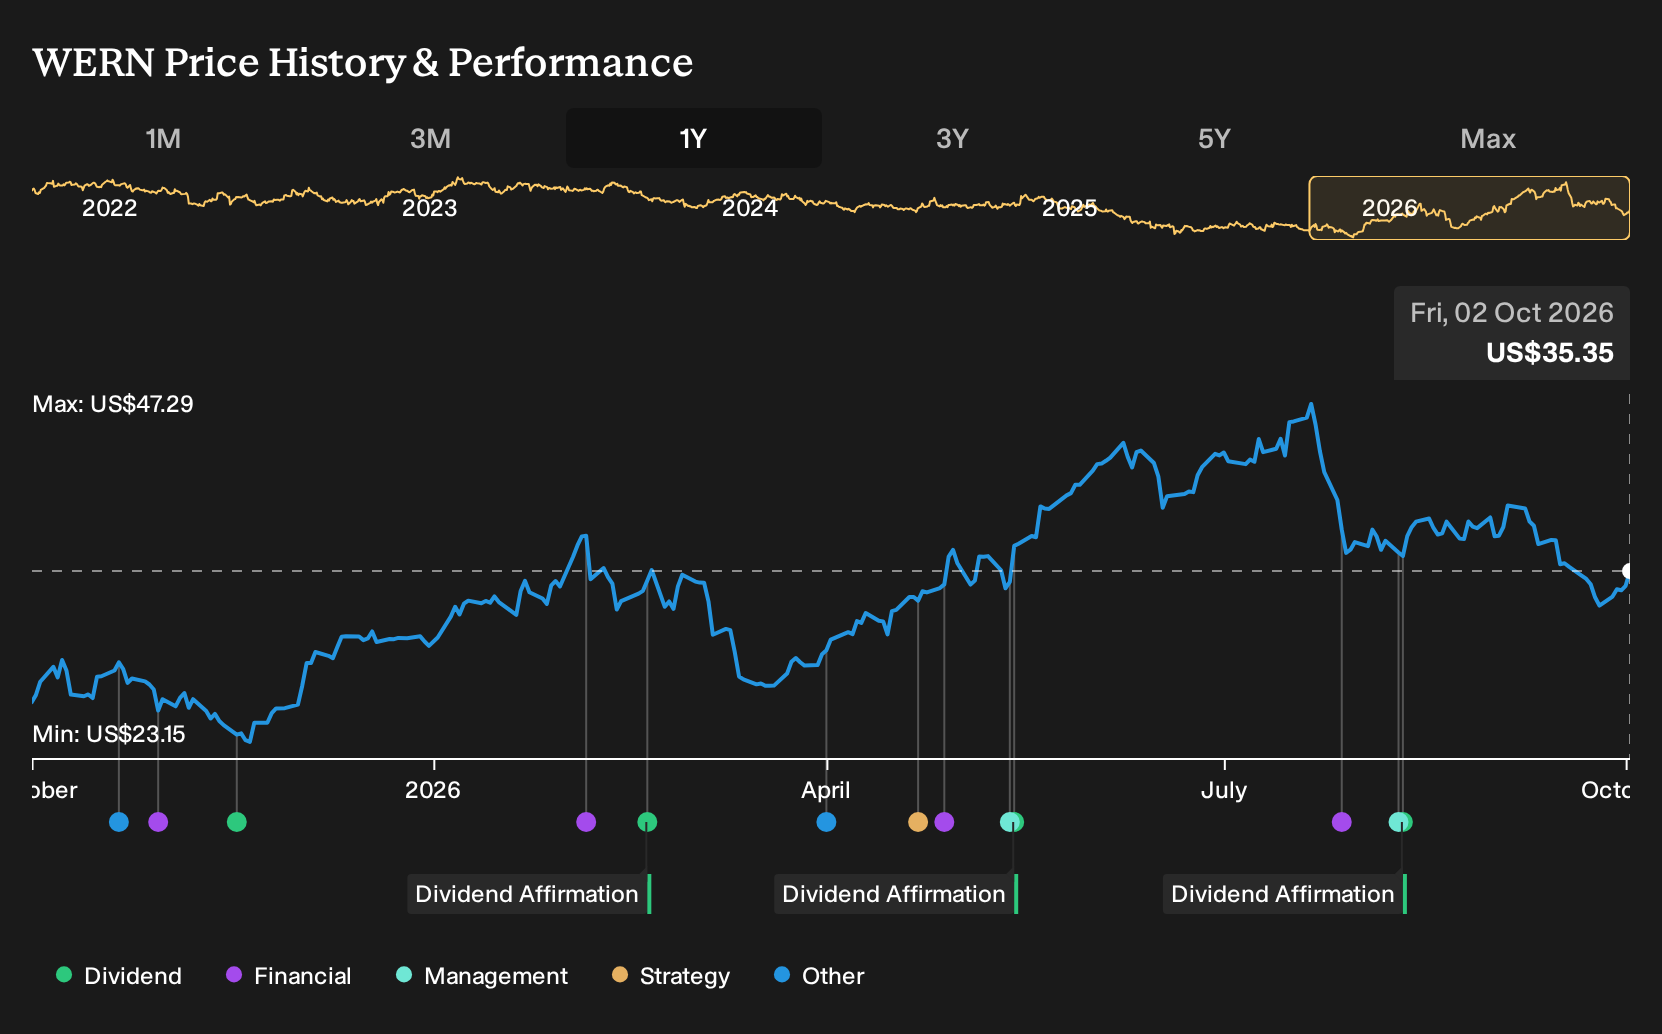
If you had been weighing Werner Enterprises in early October 2025, the headlines were already split between tech driven efficiency, regulatory cost risks and questions about long haul trucking’s future. Investors who held Werner Enterprises over the past year are up 31.0%, including dividends. That outcome makes the original fork in the road more interesting. Were early buyers mainly betting on integrated logistics, intermodal expansion in Mexico, or simply trusting that a compressed P/E would be enough?
If the move has made Werner Enterprises harder to judge, start where the gap is still open and scan 31 high quality undervalued stocks.
The Argument Werner Investors Were Really Having
The shares cost US$26.49 at the start of the period, and Werner Enterprises sat between two very different stories about what might come next.
The bullish view saw Werner evolving into a more tech heavy logistics platform. That side pointed to a Fair Value of US$29.19, the price those assumptions implied, based on investment in automation and tools like EDGE TMS helping cut structural costs and support more stable, recurring contracts.
The bearish camp worked off a Fair Value of US$23.17 and focused on pressure from automation, electric vehicles, and tougher environmental rules. Their concern was that keeping up would demand heavy, ongoing capital spending that could compress net margins over time.
What The Werner Enterprises Results Actually Tested
Werner Enterprises delivered higher sales of US$933.93m in Q2 2026 compared with US$753.15m a year earlier, which backed the bullish focus on network restructuring and revenue per truck. Net income moved the other way, dropping to US$6.35m from US$44.06m as net margin fell from 5.9% to 0.7%. The evidence cut both ways.
The key assumption was that efficiency investments would translate quickly into stronger profitability. When you assess another hauler, track whether rising revenue per asset shows up in net margin rather than only in headline sales.
What Werner Enterprises Buyers Are Paying For Now
Werner Enterprises now trades at US$35.35. The selected Narrative’s Fair Value sits above the current price and leans on a story about mix shift, safety gains and logistics contracts rather than just truck count or spot rates.
On that view, today’s price still assumes only limited credit for Werner Enterprises converting safety, Intermodal and Dedicated momentum into steadier, higher quality earnings.
"Record growth in Intermodal and Final Mile within Logistics, with intermodal revenue up 18% on 17% higher loads and final mile revenue up 14% year over year and 13% sequentially in Q2 2026, gives Werner Enterprises a base to scale a higher mix of fee based, less capital intensive revenue that can lift segment level margins and support more resilient earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Werner And A Different Freight Bet
Werner gives you one view of freight, with contracts, fleets and long distance routes. Yet your watchlist does not need to stop there.
Another player is trying to turn freight into a digital marketplace. It connects shippers and carriers through software rather than owning large truck fleets.
The focus there is matching loads efficiently, handling pricing and automating paperwork. Where Werner leans on assets, this platform leans on code and network effects.
If that model gains more share of freight spending, the economics may look very different from a traditional carrier’s balance sheet.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 70% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com