
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Boise Training Center Might Change The Case For Investing In ABM Industries (ABM)
- ABM Industries has opened the ABM Technical Training Center in Boise, Idaho, offering SEMI endorsed, semiconductor focused training for about 500 participants a year, including classroom, lab, VR components and Swagelok certification.
- This employer agnostic program expands ABM Industries' semiconductor workforce development footprint and builds on the WGNSTAR acquisition to address talent bottlenecks across chip manufacturers, equipment providers and facilities operators.
- We will now assess how ABM Industries' investment narrative could be influenced by this Boise semiconductor training center expansion.
ABM Industries Investment Narrative Recap
To own ABM Industries you need to believe the facilities and technical services engine can turn modest revenue growth into steadily improving profitability. The Boise semiconductor training center leans into that idea by pushing ABM deeper into higher value technical work. It does not remove the near term swing factor, which is still margin execution across Business & Industry and Manufacturing & Distribution.
The biggest risk remains pricing pressure and shorter term contracts, especially where ABM accepts tighter margins to defend large clients or enter growth verticals like the semiconductor supply chain. Boise adds capacity and credibility, but the financial impact looks incremental against the broader challenges of contract renewals and cost control.
The WGNSTAR acquisition is the clearest companion to this Boise announcement. Management is stitching together WGNSTAR’s semiconductor know how with ABM Industries’ existing Technical Solutions segment and training footprint in Austin. For you as a shareholder, the central question is whether this build out turns into durable, higher quality work attached to long running semiconductor infrastructure deals.
If the WGNSTAR assets and the new training centers support more wins in electrification, microgrids, data centers and semiconductor plants, they feed directly into the existing catalysts around Technical Solutions growth and cost efficiencies. Execution risk also rises, however. ABM is leaning into more technical, often lower margin entry work, which could pressure earnings quality if contracts do not scale or pricing stays tight.
ABM Industries' current annual earnings are US$166.4 million, with analyst consensus pointing to US$272.9 million by 2029. This implies an increase of about US$106.5 million, and those same forecasts call for revenue growth of 3.3% per year and total revenue of US$10.1b by 2029.
Uncover why ABM Industries' fair value indicates a 13% potential upside to its current price that could narrow quickly.
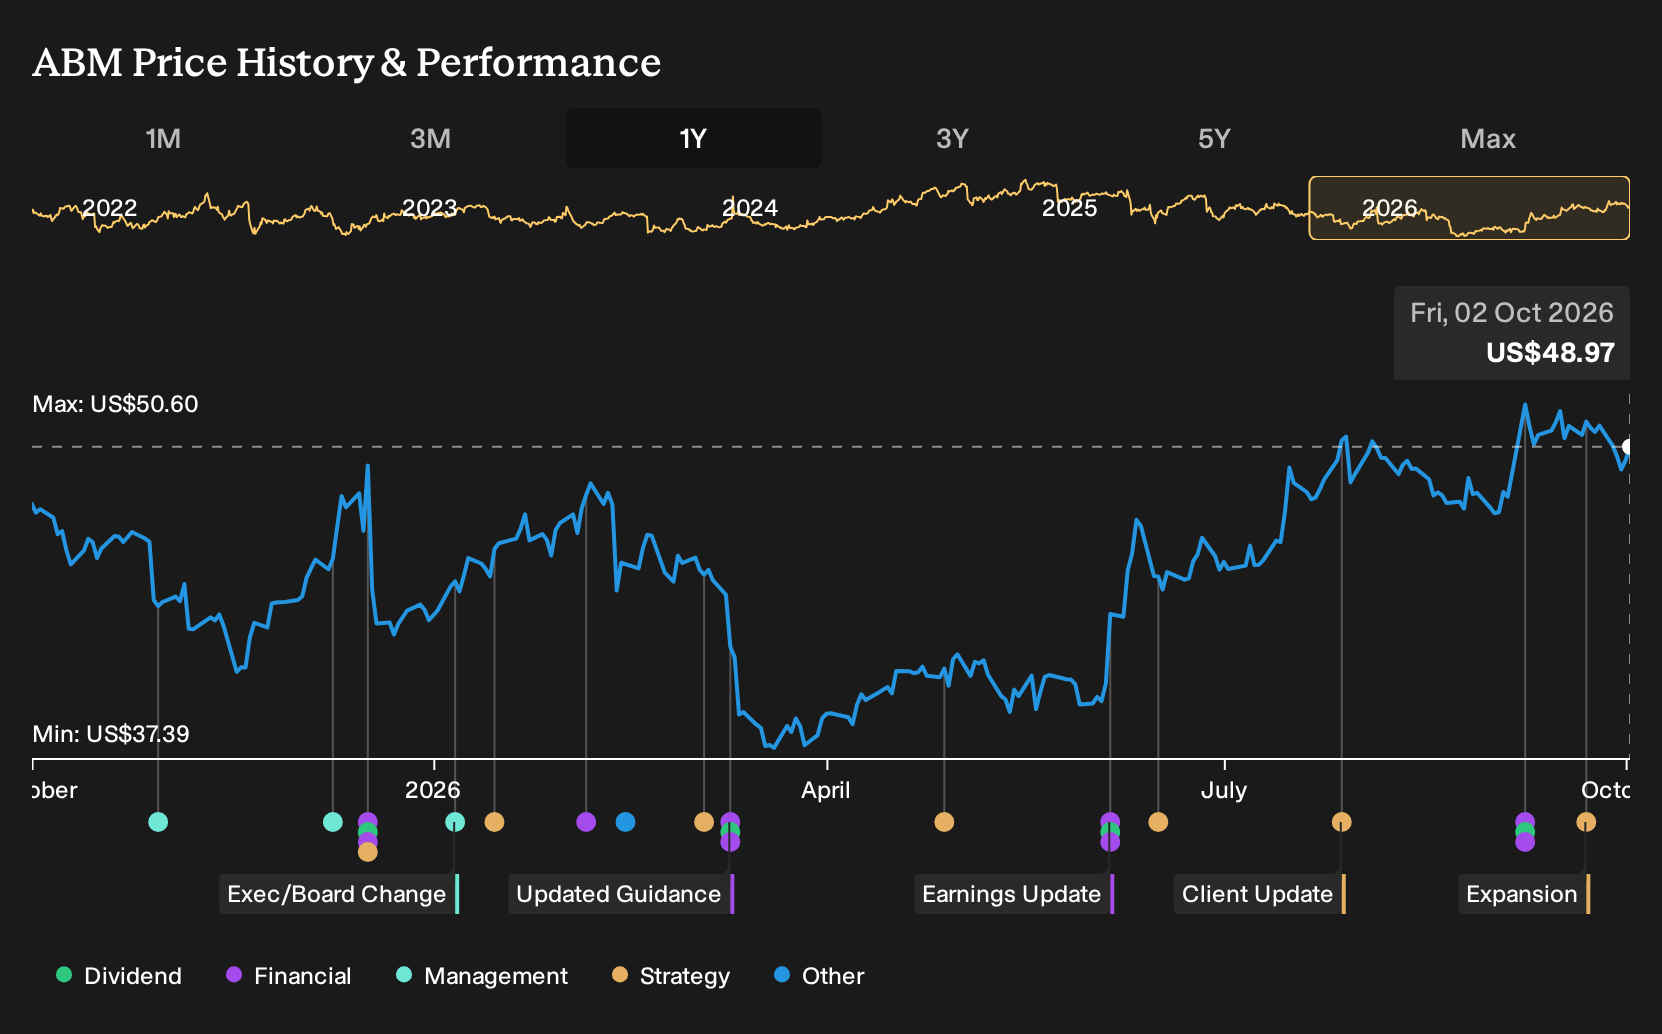
Exploring Other Perspectives
Some of the lowest ranked analysts lean hard into project timing risk in Technical Solutions. They see weather delays and construction pauses as a core threat, which is why they pencilled in only 2.6% annual revenue growth to about US$9.9b and a lower 11.8x P/E by 2029. The Boise semiconductor training news could nudge that story in either direction, so it may be useful to compare several viewpoints before deciding what you believe about ABM Industries.
Explore another ABM Industries fair value estimate, including one that suggests it could be worth just $55.36.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ABM Industries research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ABM Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABM Industries' overall financial health at a glance.
Looking For More Ideas Beyond ABM Industries?
If ABM Industries has sharpened your focus on where long term value might come from, it can help to line it up against a broader watchlist built around clear fundamentals. The Simply Wall St screener lets you filter for the traits that matter most to you, then compare how ABM stacks up beside a wider set of opportunities.
- If capital protection comes first for you, start with companies that our models flag for resilience and stability through the 31 resilient stocks with low risk scores.
- If you want to back businesses that may be priced below what their fundamentals imply, scan the 31 high quality undervalued stocks and see which tickers match your preferred quality bar.
- If balance sheet strength is non negotiable in your process, filter for robust finances using the list of solid balance sheet and fundamentals (26 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com