
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ubiquiti (UI) UniFi Protect Update Puts Valuation Back In Focus
Ubiquiti (UI) is back in focus after the release candidate of UniFi Protect 7.3 introduced Super Encoding, storage budgeting, and remote camera adoption via Teleport VPN, sharpening its pitch to surveillance heavy enterprise and service provider customers.
Ubiquiti’s recent UniFi Protect update lands as momentum in the shares has been building, with a 10.67% 7 day share price return and an 18.11% 90 day gain contributing to a 9.58% year to date move. Over a longer horizon, the 1 year total shareholder return declined 5.8%, compared with a much stronger 3 year total shareholder return of about 4x and a 5 year total shareholder return above 100%, which highlights a powerful longer run story.
Scan how Ubiquiti’s surveillance push compares with peers by jumping into our hand picked 40 power grid technology and infrastructure stocks that is aligned with secure, high bandwidth infrastructure demand.
The recent surge in Ubiquiti looks like a test of whether investors are responding to business delivery or just chasing a hot ticker. The valuation section is where that tension really shows up.
Price-to-Earnings of 39.1x: Is it justified?
Ubiquiti trades on a P/E of 39.1x, which prices the stock at a premium to its sector while still below the peer group average.
The P/E ratio compares the current share price with earnings per share and shows how much investors are willing to pay for each dollar of profit. For a business like Ubiquiti, which generated $3.27b in revenue and $960.3m in net income, that multiple reflects both its current profitability and expectations already embedded in the quote.
Against direct peers, a 39.1x P/E sits below the 54.9x peer average, so the stock trades at a discount to that group on earnings. Compared with the broader US Communications industry average of 34.7x and an estimated fair P/E of 35.4x, the current multiple looks more demanding. This indicates that the market is assigning a higher earnings value than the level suggested by the fair ratio.
Explore the SWS fair ratio for Ubiquiti.
Result: Price-to-Earnings of 39.1x (OVERVALUED)
Still, Ubiquiti’s rich 39.1x P/E and reliance on enterprise and service provider networking budgets leave little room for disappointment if demand or profitability weakens.
Find out about the key risks to this Ubiquiti narrative.
Another View on Ubiquiti’s Valuation
A different lens on Ubiquiti comes from the SWS DCF model, which estimates the future cash flow value at $482.65 per share versus the current $620.52 price. That points to an overvalued result and raises a simple question for investors: How much of tomorrow is already priced into today?
Look into how the SWS DCF model arrives at its fair value.
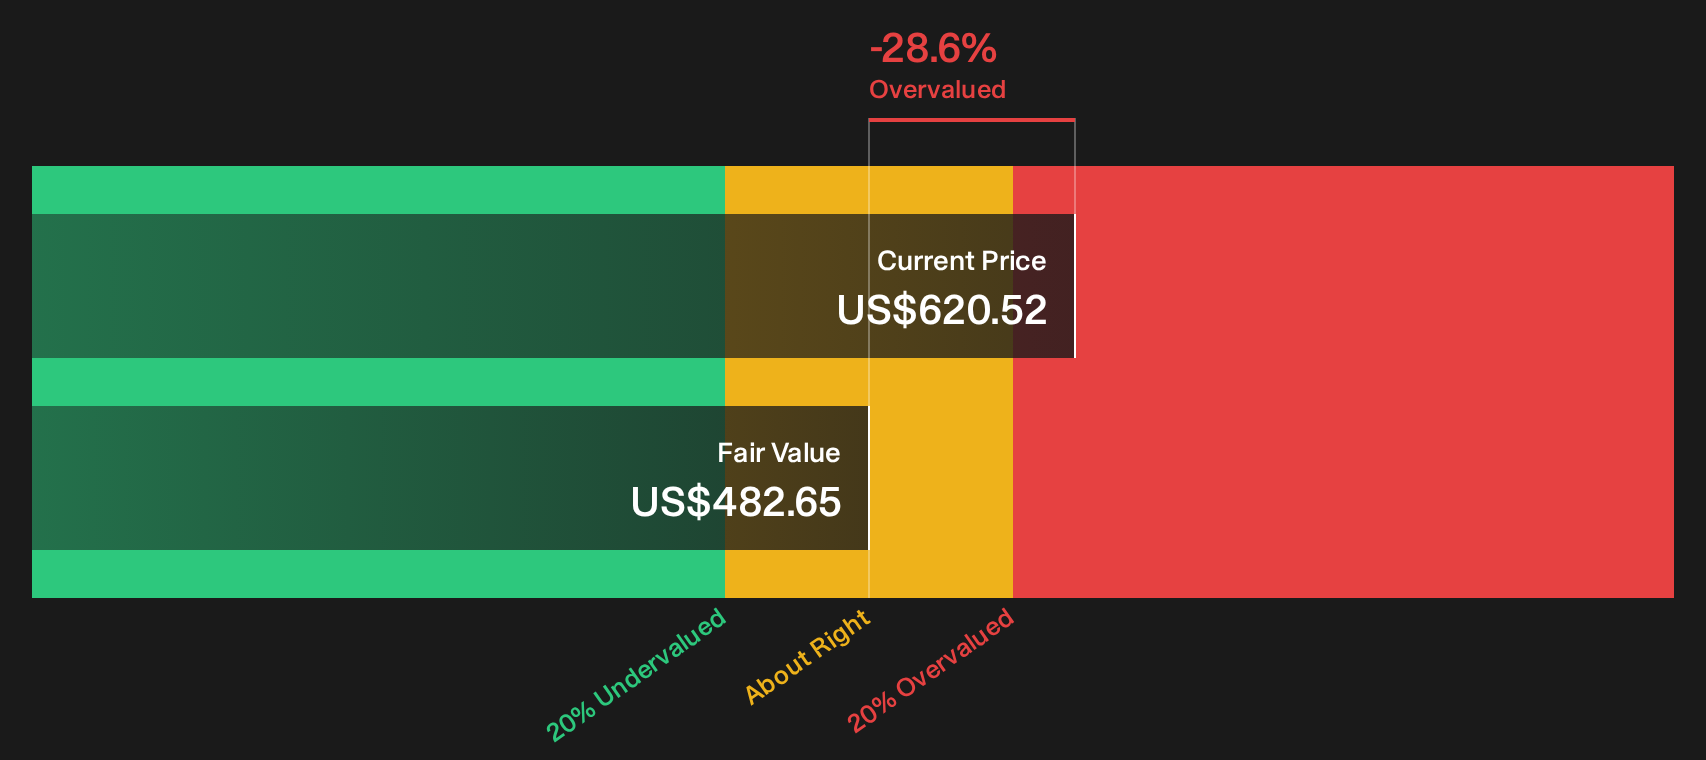
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ubiquiti for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So is the recent excitement around Ubiquiti justified or overdone? If you want to move beyond the headline multiples and sentiment, explore the upside case for yourself by reviewing the 2 key rewards.
Looking for more investment ideas beyond Ubiquiti?
If Ubiquiti has sharpened your focus on quality, do not stop here. Broaden your watchlist with a few targeted screeners that surface very different types of opportunities.
- Target quality at a discount by checking companies that combine strong fundamentals with appealing valuations through the 31 high quality undervalued stocks.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (26 results) that can better withstand funding shocks and tighter credit conditions.
- Hunt for underfollowed potential by scanning 19 high quality undiscovered gems before the broader market turns its attention there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com