
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Loyally Launch Change Ally Financial (ALLY) Narrative
- Ally Financial recently rolled out Loyally, a no fee rewards experience that replaces complex points and minimum balance rules with trackable perks, including offers that management values at up to $1,000 a year and access to VIP experiences valued at up to $10,000.
- Loyally ties directly into Ally Financial's digital banking app and broader push to personalize everyday money management, linking customer rewards, new account bonuses, and entertainment partnerships to the same data driven ecosystem that has supported customer growth and higher satisfaction scores.
- We will look at how Ally Financial's investment narrative is shaped by the Loyally launch and its app based loyalty model.
Scan how Ally Financial’s push into app based rewards compares with other digital first banks by reviewing our curated list of list of solid balance sheet and fundamentals (26 results).
Ally Financial Investment Narrative Recap
To own Ally Financial, you need to be comfortable with a bank that leans heavily on auto finance while trying to deepen its digital banking edge. In the short term, the key swing factor remains how efficiently Ally prices and gathers deposits while growing higher yielding loans. Loyally appears more like incremental support for customer stickiness than a near-term earnings needle mover.
The biggest risk still sits in credit and concentration. Any deterioration in consumer credit, pressure on auto volumes, or tougher competition for prime borrowers could weigh on returns, especially with earnings growth expectations already built in. Loyally does not fundamentally change those core exposure points.
The most relevant recent development around this story is Ally Financial’s consumer banking reset under Yasmin Tailor in 2025. Management focused on interest rate sensitivity and deposit costs, and reported a 60 basis point reduction in deposit costs and 62% EPS growth year over year, alongside 5% customer growth and strong satisfaction metrics.
That operational backdrop matters for Loyally. A lower cost deposit base and high retention rates give Ally more room to experiment with rewards without relying purely on higher pricing or balance sheet risk. Execution risk remains if perks fail to translate into deeper product adoption while the auto-heavy loan book still drives capital needs and credit sensitivity.
Ally Financial's analyst narrative points to US$9.9b in revenue and US$1.8b in earnings by 2029, which implies revenue growth of 7.7% per year and an earnings increase of about US$0.5b from earnings today of US$1.3b.
Uncover how Ally Financial's fair value indicates a 37% potential upside to its current price before the market closes the gap.
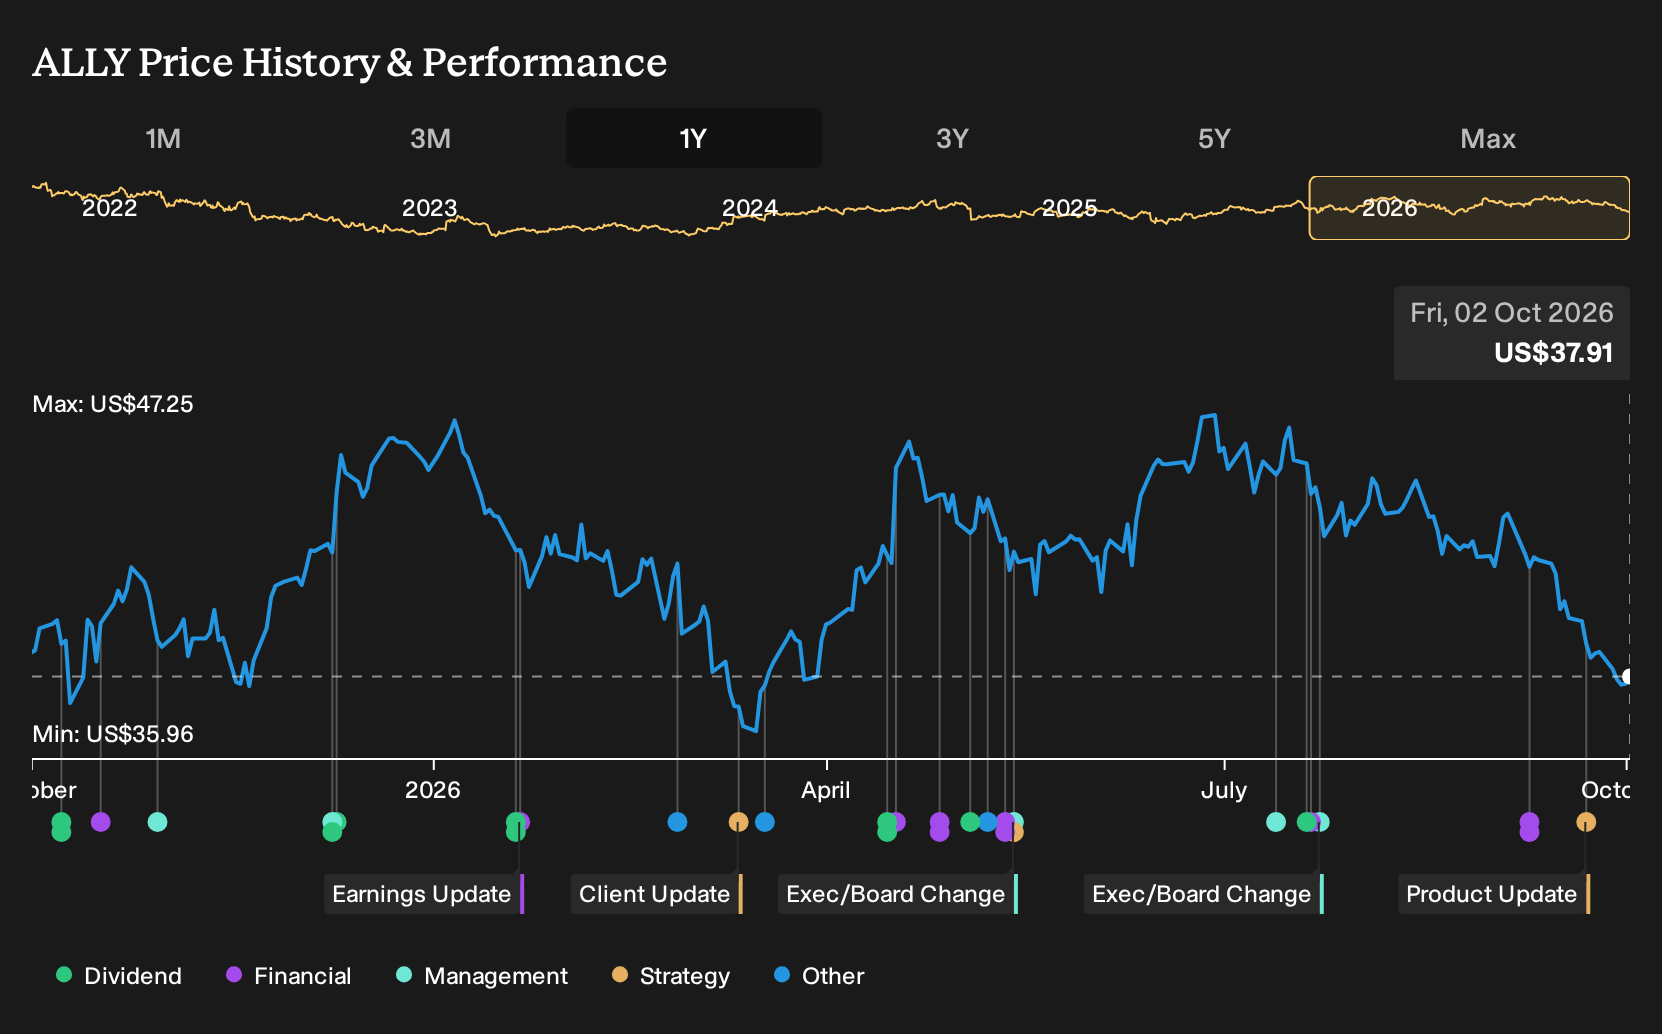
Exploring Other Perspectives
Some of the most optimistic analysts frame Ally Financial very differently. They focus on the Corporate Finance unit as the real swing factor, pointing to forecasts of US$11.0b in revenue and US$2.2b in earnings by 2029, before Loyally existed. Those views may evolve as this new rewards program beds in.
Explore 4 other Ally Financial fair value estimates, including one that suggests as much as 53% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Ally Financial research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Ally Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Ally Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ally Financial?
If you want to stress test your view on Ally Financial and broaden your watchlist at the same time, the Simply Wall St Screener can help you line up comparable opportunities in a more structured way.
- If you care most about paying a fair price for quality, start with a curated set of potential value ideas through 31 high quality undervalued stocks.
- If resilience and balance sheet strength matter more to you than headline growth, filter for financially sturdy businesses using the 31 resilient stocks with low risk scores.
- If you are hunting for strong businesses that are not widely followed yet, scan through a focused pool of lesser known opportunities via 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com