
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Spain Housing Shortage Puts Aedas Homes Stock And 2 Madrid Builders In Focus
Spain’s housing debate has moved from dinner tables to the streets, and markets are reacting. Political risk is rising just as talk of rent controls, investor bans and a housebuilding push collides with chronic housing scarcity. That mix can punish some assets and reward others. This article explains how that story links to three Madrid listed construction and materials stocks that are exposed to these headlines and why their next chapter could matter for your portfolio.
The three Madrid listed stocks that follow are only a sample of what this housing story touches, and the full screen surfaced 8 more Spain focused construction and building materials businesses with equally compelling narratives that are not covered below. To go wider than this shortlist and identify which Spanish residential construction and building materials stocks best fit your own thesis, head straight into the Spanish Residential Construction & Building Materials screener
Elecnor (BME:ENO)
Elecnor plugs this housing themed screen into the nuts and bolts of Spain’s grid, telecoms and construction work, giving you exposure to the networks and infrastructure that need to keep pace if a housebuilding push actually happens.
Elecnor is a Madrid based engineering and construction group focused on energy, networks and infrastructure, generating about €1.8b from Projects and €2.6b from Services, with a market value of roughly €2.6b.
"Energy transition and electrification are supporting a large international projects pipeline."
What really moves the dial for Elecnor now hinges on how one pressure on future returns plays out beneath those headline projects.
That pressure point is exactly what the full full narrative for Elecnor unpacks, showing where Elecnor’s project engine could accelerate returns or leave value masked.

Aedas Homes (BME:AEDAS)
Aedas Homes is a pure-play Spanish residential developer tied closely to the housing shortage theme, with roughly €847 million from development and €22 million from asset management, all earned in Spain, and a market value of about €1.0 billion.
Aedas Homes matters for this housing focused screen because it directly converts Spain’s shortage of new homes into build to sell and build to rent projects that households and institutions actually buy, turning policy talk into brick and mortar execution.
"Aedas Homes' strong exposure to the structural undersupply of new housing in Spain and urbanization trends continues to provide exceptional revenue visibility, as reflected in a consolidated order book of nearly €1.7 billion and a landbank sufficient to maintain over €1 billion in annual revenue through 2029, positioning the company to benefit from sustained top-line growth as demand outstrips supply."
What really decides how that promise translates for investors now hinges on how one quiet pressure on future profitability and funding costs resolves over the next few years.
That funding squeeze is exactly where the full narrative for Aedas Homes shows how Aedas Homes' order book, landbank and capital choices could be accelerating or quietly masking long term value.

CLERHP Estructuras (BME:CLR)
CLERHP Estructuras is a Murcia based structural engineering and construction group tied to Spain’s residential build theme, earning about €7.2 million from calculation and execution of structures, €6.5 million from sale of goods and land, and €0.4 million from technical assistance and consulting, with a market value of roughly €375 million.
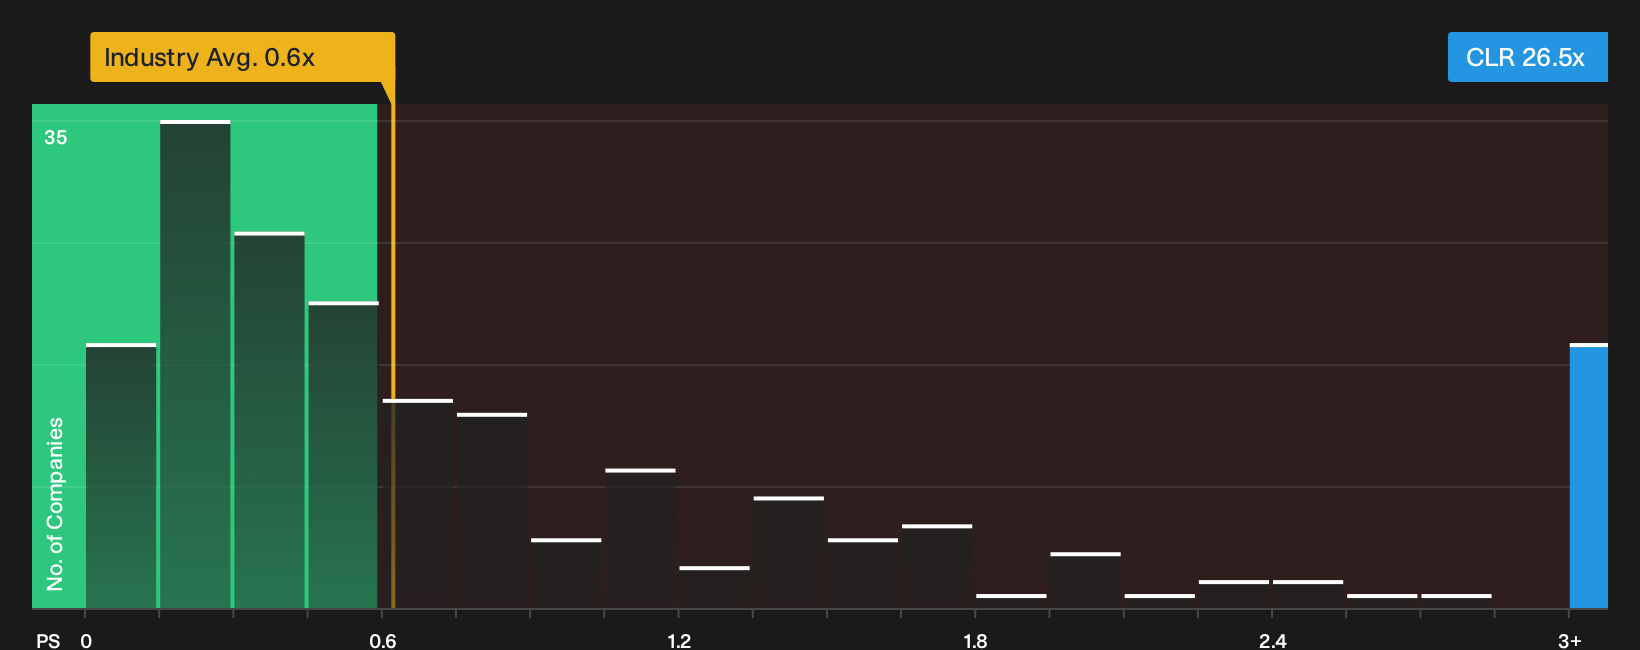
Investors looking at Spanish residential construction may find CLERHP Estructuras interesting because it designs and builds structures that sit at the heart of new housing projects, yet trades on a very high P/S multiple that would require a favorable resolution of a potential pressure on future returns.
That lofty P/S expectation makes it worth running through the 1 key reward and 2 important warning signs (1 is major!) to see where CLERHP Estructuras' next big swing might come from.
Seeking Alternatives Before The Crowd?
Fresh themes can gain momentum quickly and early movers may participate in breakouts while others watch prices move. Scan curated ideas that may be under the radar for now, then consider whether they fit your strategy.
- Target resilient compounding potential by running the 228 resilient stocks with low risk scores and focusing on businesses where balance sheets and risk profiles aim to keep drawdowns from spiraling.
- Explore upside where pricing power still matters through the 196 high quality undervalued stocks and focus on cash generative companies that screens flag as trading below underlying fundamentals.
- Track capital flowing into future infrastructure by scanning the 90 AI infrastructure stocks and watching which enablers of data centers and networking build early lead positions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com