
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Veidekke (OB:VEI) Fully Valued After Its New Bryggebyen Contract Win?
Veidekke (OB:VEI) just picked up a new design and build contract for phase four of the Bryggebyen housing project in Arendal, a NOK 190 million addition to its order book.
Veidekke’s latest contract win comes as the share price trades at NOK214.0, with a 90 day share price return of 10.54% and a year to date share price gain of 22.15%. The 1 year total shareholder return of 46.33% and 3 year total shareholder return of 167.62% point to strong longer run momentum that recent news may help to reinforce.
Scan beyond Veidekke and this Bryggebyen contract win by lining up other construction exposed opportunities that are screened for list of solid balance sheet and fundamentals (208 results)
Veidekke looks like a solid operator with fresh contract momentum and a strong recent share price run. The next step is working out whether that quality is already fully reflected in today’s NOK214 tag.
Price-to-Earnings of 17.2x: Is it justified?
On current numbers, Veidekke trades on a P/E of 17.2x, which screens as expensive against both peers and an internal fair value benchmark, even with the share price at NOK214 and the SWS DCF model suggesting the stock trades about 6.2% below its cash flow based fair value estimate of NOK228.13.
The P/E ratio compares what investors pay today for each unit of earnings. For a construction and infrastructure group like Veidekke, that metric often reflects how confident the market is that profits can be sustained through cycles and project risk.
Here, the market is placing a richer tag on Veidekke than on comparable construction stocks, with the P/E above the peer average of 15.3x and also higher than the European industry average of 15.5x. The multiple also sits above an estimated fair P/E of 15.8x, which indicates investors are paying more than the level the model suggests the valuation could gravitate toward if pricing became more in line with earnings power.
Explore the SWS fair ratio for Veidekke.
Result: Price-to-Earnings of 17.2x (OVERVALUED)
Still, the Veidekke story can change quickly if construction demand weakens or if project execution issues start to compress the earnings that underpin that 17.2x P/E.
Find out about the key risks to this Veidekke narrative.
Another View on Veidekke’s Value
The P/E suggests Veidekke is priced richly, yet our DCF model points the other way. On that cash flow view, NOK214 screens about 6.2% below an estimated fair value of NOK228.13, which indicates the multiple might not fully reflect the cash generation profile.
That difference leads to a simple question. Is the P/E pointing to valuation risk, or is the SWS DCF model highlighting an opportunity that the market has not fully priced?
Look into how the SWS DCF model arrives at its fair value.
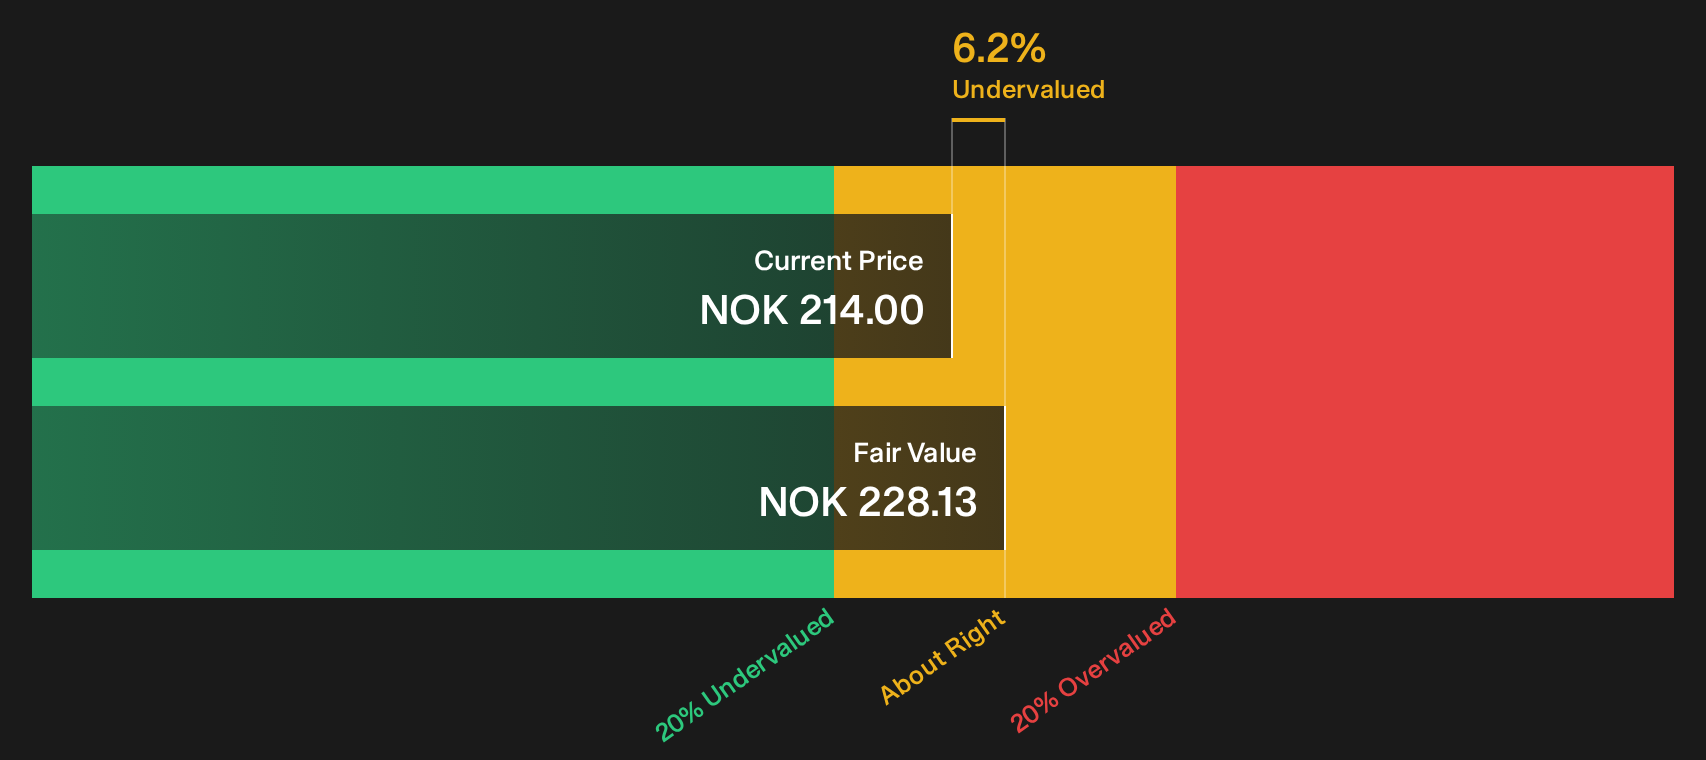
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Veidekke for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by Veidekke’s premium P/E and that DCF gap. Treat this as a prompt to move quickly, stress test the numbers, and weigh 3 key rewards and 1 important warning sign.
Looking for more Veidekke sized ideas?
If Veidekke has you thinking harder about price, quality, and risk, broaden your watchlist with well screened alternatives that could sharpen your next move.
- Target strong fundamentals and sensible pricing by reviewing a 196 high quality undervalued stocks that may deserve a closer look before the crowd catches on.
- Balance opportunity with resilience by scanning a 228 resilient stocks with low risk scores that could help steady your portfolio when conditions turn choppy.
- Hunt for underfollowed potential by checking a 615 high quality undiscovered gems that might not stay under the radar for long.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com