
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Where Does Biotest (XTRA:BIO3) Value Sit Against Its Sales?
Biotest has delivered mixed share performance over recent years, which raises a simple question for anyone looking at the stock today. Is the current price you see on screen well supported by the sales the business is generating?
- Over the past 3 years the share price has fallen 19%, which puts the focus squarely on whether the revenue base can justify where the stock trades now.
- The company relies on its plasma based therapies and related products to convert demand into revenue, so any change in volumes, pricing or production efficiency can directly affect how much investors are paying for each euro of sales.
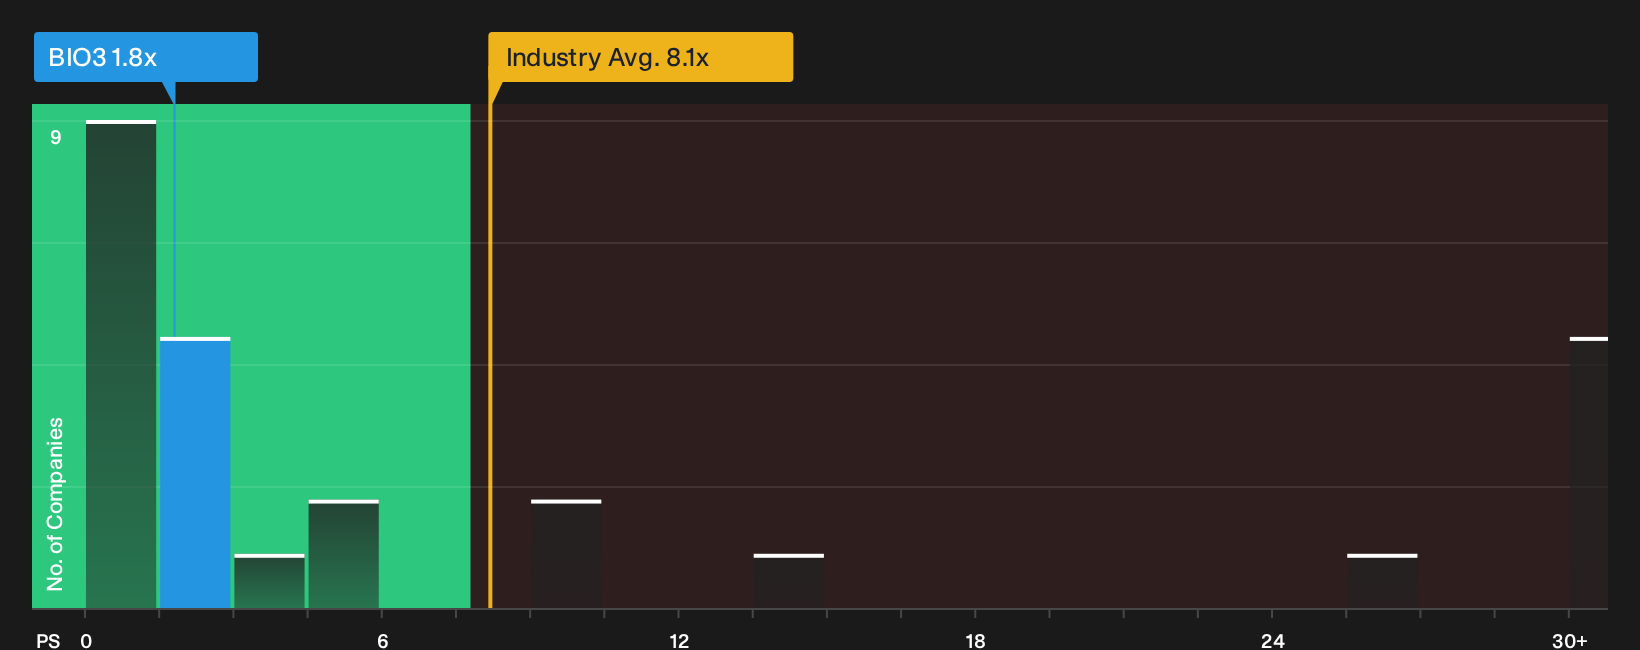
- Before you settle on a price for Biotest, see what its peers cost. See how Biotest's 1.8x P/S compares with its peers.
The issue now is whether Biotest's current market value is well aligned with its sales when compared with the broader industry average.
If you are weighing Biotest against other businesses where valuation is based more heavily on current sales, it can be useful to compare it with companies in 196 high quality undervalued stocks
Is Biotest Still Cheap on Sales?
P/S is a clean way to look at Biotest because sales are a key reference point for a plasma focused group where earnings can swing around reported investments and research costs. On this measure, the stock trades on a P/S of 1.8x, far below the broader Biotechs industry average of 10.5x.
That gap means the market is currently valuing each euro of Biotest revenue at a substantial discount to typical peers. For you as an investor, the key question is whether that markdown reflects genuine concerns about the quality, durability or growth potential of those sales, or whether sentiment has simply reset too far. The answer depends on how you view Biotest's pipeline risk, pricing power in plasma products and the capital needed to keep its facilities running efficiently. These are the real drivers sitting behind that low headline multiple. Explore the numbers behind Biotest's P/S valuation.
The Biotest Narrative: What Would Justify Today's Price?
Biotest's valuation puzzle only really comes into focus once you set out what would need to happen to its future growth, margins and earnings for the stock to be worth materially more or materially less than it trades for today on the market. Narratives on Simply Wall St's Community page are built around that idea, since each one spells out the assumptions that sit behind its view of fair value so you can compare those expectations with the actual numbers as Biotest's results arrive over time.
A clear, number driven narrative on Biotest gives you a single reference point for where you think its growth, margins and execution might head next, based on the current P/S discount to the broader Biotechs group. Once that view is written down, it becomes easier to test those assumptions against each set of reported figures and adjust your thesis as the story unfolds.
Share your own Narrative for Biotest and set out the assumptions behind your valuation.
Before leaving Biotest, one more check deserves your attention
Price tags and sales multiples only tell part of Biotest's story. Separate fundamentals checks have raised specific concerns that are worth weighing carefully once you see exactly what they flag. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com